TMI: The Age of Information Overload

In raising the issue of TMI (“Too Much Information”), I’m not referring to your parents talking about their sex life, but rather the explosion of data that is flooding our society.
How much data is creeping into our daily lives? The issue impacts all professions, but is especially acute in the investment world. A recent study, co-authored by Roger Bohn and James Short (Directors at the Global Information Industry Center at UC San Diego’s School of International Relations and Pacific Studies), tackles this elusive measurement problem of TMI.
Everyday Life1
One need not become a rocket scientist to figure out we are being inundated with information. The average household already receives 120 TV channels, with no signs of slowing. I love sports just as much as the average person, but do I really need six flavors of ESPN? Or seven different HBO channels? Our TVs (a.k.a., “god box”) even carries the “GOD TV” channel. Does this mean I don’t have to go to church anymore?
Data is permeating other areas as well. Microchips are infiltrating our microwaves, refrigerators and automobiles. The average car now contains more than 50 processors, including a butt-warming car seat chip. Suffice it to say, information is becoming pervasive.
Gorging on Information – Zettabytes at a Time
I think most reasonable people would agree the typical person is consuming more information, but exactly how much? Through Bohn and Short’s rigorous study, they determined Americans consumed 3.6 zettabytes in 2008. A zettabyte is equivalent to 1,000,000,000,000,000,000,000 bytes (21 zeroes), equating to about 10,845 trillion words. This statistic translates into the consumption of approximately 34 gigabytes (about 1/5 the storage in a standard laptop) per day by each American.
Put another way, Kathleen Parker at the Washington Post, calculated the total amount of data produced in 2006 was 3 million times more data than the information contained in all the books ever written.
Investor Dilemma: Paralysis from Analysis
There’s no question in my mind that data can become overwhelming in the investment world. Focusing on the endless concerns spewed over the media can lead to investment paralysis. Each in every day I hear why the world is going to end, or why an investment du jour will rocket to the moon. Not only are the messages schizophrenic, but the quantity is unending. As I mention in my book, while I managed a $20 billion fund, I could receive 500 e-mails, 100 voicemails, and hundreds of pages of hard copy reports and faxes on a daily basis. Completely reviewing the data received in a day’s work could theoretically take weeks, if not months.
Today, the voluminous flow is not retreating, but instead we are seeing new avenues of information distribution, including, Twitter, Facebook, blogs, instant messaging, YouTube, LinkedIn, and numerous other social networking outlets. With the 24/7 daily news cycles, and instantaneous transferability of information, the internet has become a convenience but also a source of heightened anxiety levels. Rather than giving up and throwing in the towel, I willfully accept the challenge to navigate through the masses of data. Automated spam filters, topic alerts, and aggregated news readers are a few basic examples of managing data through technology.
The Surplus Solution
The simple solution to TMI is ignoring and filtering the data. This objective is easier said than done, especially for the inexperienced. Deciphering and tracking the endless creation of new acronyms, alone, can become a full-time job for the less familiar.
The best advice, which I continually take to heart, comes from legendary investor Peter Lynch who states:
‘‘If you spend more than 14 minutes a year worrying about the market, you’ve wasted 12 minutes.’’ He hammers home the point that timing the market based on noisy data is a losing cause. “Anyone can do well in a good market, assume the market is going nowhere and invest accordingly,” adds Lynch.
The other option is to simply outsource the responsibility. Time-strapped professionals follow this strategy when it comes to tax and legal advice, but for some reason many ill-equipped individuals feel they can adequately handle the arguably most important aspect of their financial existence…their investments. While finding an experienced and trusted professional can take some time, it is not an insurmountable task (see my article on selecting an advisor).
Follow a Plan
As the accelerating amounts of data rise in volume, individuals can choose from the following options: 1) Embrace the power of technology to efficiently manage, organize, and filter our consumption of data; or 2) Become slaves to its overwhelming control. I choose the former. Gaining perspective in light of the daily vortex of data we plug ourselves into can be challenging. Taking a step away from the emotional pressures of the daily grind, and exhaling will help you see the forest from the trees. After taking a breather from the chaos, returning to your long-term, disciplined, systematic plan – designed by you or your advisor – will assist you in taming the TMI monster.
Read Full Article from Roger Bohn and James Short
1. Data from Roger Bohn and James Short’s 2009 How Much Information? Report.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds and shares of GOOG, but at time of publishing had no direct positions in DIS, WPO, Twitter, Facebook, or LinkedIn. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
NVEC: Profiting from Electronic Eyes, Nerves & Brains

Recently, Seeking Alpha Editor-in-Chief Mick Weinstein interviewed me with the purpose of reviewing an equity investment I find attractive. For the “stock-jock” Investing Caffeine followers, I am publishing the January 5th interview below.
What is your highest conviction stock position in your fund – long or short?
I don’t really have a highest conviction stock, per se, in my fund since I treat all my stocks like children – I love them all. Having said that, NVE Corp. (ticker: NVEC) is a holding of mine that exhibits many of the characteristics I look for in an investment. The Eden Prairie, Minnesota based company is named after “Nonvolatile Electronics,” which refers to memory technology that retains data even when power is removed – a critical attribute for certain applications.
Tell us a bit about the company and what it does.
NVE Corp. is a market leader in nanotechnology sensors, couplers, and MRAM intellectual property (Magnetoresistive Random Access Memory). NVE’s microscopic technology enables the transmission, acquisition, and storage of data across a broad array of applications, including implantable medical devices, mission critical defense weapons, and industrial robots. Major customers include: St. Jude Medical, Inc. (STJ), Starkey Laboratories, Inc., and the U.S. Government.
The company’s coupler and sensor businesses have been ridiculously profitable. Even over a period covering one of the worst global financial crisis in decades, NVE managed to increase its operating margins from an already very respectable 40% range in Fiscal 2007 (ending March) to a stunning 56%+ level in Fiscal 2009.
Beyond sensors and couplers, NVE Corp. is optimistic about the potential for the MRAM market. However, outside of a few one-time licensing fees, NVE is currently generating effectively $0 revenues from this nascent storage technology. Outside of producing small MRAM devices for niche applications such as tamper prevention, NVE Corp. is looking to leverage their IP portfolio by licensing out the patents and subsequently receiving royalties from MRAM device manufacturers. MRAM technology uses magnetic fields to record information, but unlike tape recorders in which a short section of tape holds magnetic information, with MRAM data is held by electrons with out the need of moving parts to read or write data. Believe it or not, this method is highly reliable and is very power-efficient relative to other storage technology alternatives. Currently, the problem with MRAM is the cost prohibitive manufacturing requirements relative to other memories (such as DRAM, SRAM, and Flash), but costs are expected to come down over time. For some MRAM believers, the technology is considered the “Holy Grail” because it may have the potential to combine the speed of SRAM, the density of DRAM, and the non-volatility of Flash memory in a universal source.
If the unproven potential of MRAM ever blossoms, the broad portfolio of NVE Corp.’s MRAM patents should represent a very sizeable profit opportunity. Of course, NVE Corp. must first establish the validity of its MRAM intellectual property and appropriately charge and collect royalties for IP usage. How big can the MRAM market be? Some size the MRAM market in the billions and Toshiba has stated they expect the MRAM market to surpass the size of the traditional memory markets by 2015.
No matter how one measures the size of the market, there will be a substantial revenue opportunity for NVE Corp. if every smart-phone, gaming device and laptop exclusively uses universal MRAM – rather than a combination of DRAM, SRAM, and Flash technologies.
Can you talk a bit about the industry/sector? How much is this an “industry pick” as opposed to a pure bottom-up pick?
Generally speaking, I am a bottom-up investor. I may have concrete views on a particular industry, but the fundamentals of a company will be the main determinant of my investment thesis. Overall, I am looking for market leading franchises that can sustain above-average growth rates for extended periods of time. These traits can come from either a company operating in a mature, sleepy industry (take for example Google in the advertising world) or from a more dynamic growth industry like nanotechnology in the case of NVE Corp.
I believe the nanotechnology industry is in the very early innings of an innovation revolution with regard to new applications and products. Like semiconductors, the economies of scale and technological advances of NVE Corp.’s “spintronic” technology should continually allow faster, smaller, more reliable solutions at lower bit prices. In my view, this snowballing effect will only increase the penetration of nanotechnology solutions and introduce an ever increasing list of new applications.
Can you describe the company’s competitive environment? How is this company positioned vis a vis its competitors?
NVE Corp. has competitors along all three of its spintronic businesses. In their sensor business, most of the competition comes from the makers of legacy electromechanical magnetic sensors, including HermeticSwitch, Inc., Meder Electronic AG (Germany), and Memscap SA (France).
In the coupler space, NVE Corp. faces a larger list of well capitalized, household semiconductor names, including Avago (AVGO), Fairchild Semiconductor International (FCS), NEC Corporation, Sharp Corporation, Toshiba Corporation, Vishay Intertechnology (VSH), Analog Devices, Inc. (ADI), Silicon Laboratories Inc. (SLAB), and Texas Instruments Incorporated (TXN).
A different set of competitors are searching for the MRAM holy grail, including the following companies: Crocus Technology SA (France), Grandis, Inc., MagSil Corporation, Spintec (France), Spintron (France), Spintronics Plc (UK), and IBM.
There is undoubtedly a ton of competition in the spintronics space, but as of October 2009, NVE Corp. has 52 issued U.S. patents and over 100 patents worldwide (either issued, pending, or licensed from others) – many focused on the potentially lucrative MRAM field. Although NVE Corp. has many competitors, they have dominant share in the coupler/sensor market when it comes to high-end, merchant supplied solutions. Moreover, on the MRAM side of the business, the company has already licensed its intellectual property to several companies, including Cypress Semiconductor (CY), Honeywell International Inc. (HON), and Motorola, Inc. (MOT).
Can you talk about valuation? How does valuation compare to the competitors?
Valuation is a key component for all my stock investments. In my valuation work I pore over the income statement, balance sheet and cash flow statement in deriving my price targets.
One area helping NVE Corp.’s valuation case is its improving trend-line of profitability. Over the last 5 years alone, gross margins have gone from 40% to over 70% – not a bad business model if you can execute it. The company also has a pristine balance sheet. Not only does NVE Corp. have no debt, but it also is sitting on a growing mound of cash/investments (over $43 million), representing more than 20% of the company’s market capitalization. Lastly, the company in my view is attractively priced on a free cash flow basis (cash from operations minus capital expenditures), yielding around 6% of the total company value.
What is the current sentiment on the stock? How does your view differ from the consensus?
With small cap stocks like NVE Corp., sentiment and lack of liquidity can create gut-wrenching volatility. Unlike many growth investors who pay more attention to positive momentum factors (price direction), I welcome volatility as it allows me to find more attractive entry and exit points.
With that said, NVE Corp. hit a peak stock price north of $63 per share in early September fueled by 41% revenue growth in their June quarter (fiscal Q1). Subsequently, in fiscal Q2 (ending September 30th), revenue growth decelerated to +14% causing momentum investors to take NVE Corp.’s shares to the woodshed. With the stock down about -35% from its recent crest, I find the valuation only that much more attractive.
Wall Street estimates are calling for further slowing in revenue growth in the coming quarter, so the short term sentiment may or may not continue to sour? Timing bottoms is inherently dangerous and not something I consider myself an expert at. Absent a major deterioration in fundamentals, I stand ready to add to my position if NVE Corp.’s share price falls and valuation metrics improve.
I would argue the typical consensus view advocates selling shares when revenue growth slows. Many of my best performing stocks have been purchased during transitory periods of slowing or cyclical downturns. Let’s hope that’s the case with NVE Corp.
Does the company’s management play a role in your position? If so, how?
Absolutely. There is a continual debate over what is more important, the jockey or the horse? My investment philosophy puts more weight on the jockey than the horse. Obviously, I’m looking for the combination of a talented management team and a solid business model.
When it comes to NVE Corp., Daniel Baker, Ph.D. has done a phenomenal job managing the hyper-growth profile of the company, while preserving prudent and conservative financial values. For the third year in a row, Dr. Baker was also recognized as one of the best U.S. CEOs in the semiconductors and semiconductor equipment industry by investment research and financial consulting firm DeMarche Associates.
At the end of the day, it’s difficult to argue with a track record of success. Since Dr. Baker took over, revenues have more than tripled and earnings have grown from $0.05 in fiscal 2001 to $2.04 in Fiscal 2009.
What catalysts do you see that could move the stock?
Since I hold a longer term investment horizon, catalysts are not a driving aspect to my investment process. But clearly, any additional evidence unearthed in the marketplace validating the growth in the MRAM market, or announcements confirming the value of NVE Corp.’s MRAM intellectual property, should provide support to the stock price.
Beyond that, given where the stock is trading now, I believe merely continuing the execution on their sensor and coupler business provides adequate upside prospects.
What could go wrong with this stock pick?
Investing in small cap technology stocks comes with a whole host of risks. Although I don’t believe the positive scenario of critical mass MRAM commercialization is baked into the current stock price, nevertheless I understand any setbacks announced relative to NVE Corp.’s MRAM prospects or the industry’s MRAM expectations, will likely result in stock price pressure.
NVE also has significant customer concentration, therefore a loss or cutback in sales from a lead customer will probably contribute to price volatility.
From a macro perspective, the company has battled successfully through the economic crisis and proven itself somewhat recession resistant. Nonetheless, the company has sizeable exposure to the industrial segment and would not be immune from the “double-dip” economic recession scenario.
Surely there are additional hazards to this investment, however these are some of the risks I am currently focused on.
Do you have any closing thoughts?
NVE Corp. is not a stock for the faint of heart. However, for those who can stomach the volatility, I encourage you to do some more homework on NVE Corp. Not only will you learn about a phenomenally managed, very profitable, attractively priced nanotechnology company, but you will also gain insight into a leading force behind the eyes, nerves, and brains powering the electronic systems of our future.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own shares in NVEC (and certain exchange traded funds), but did not have any direct positions in the following companies or stocks mentioned in this article at time of publication: STJ, HermeticSwitch, Inc., Meder Electronic AG, and Memscap SA, AVGO, FCS, NEC Corporation, Sharp Corporation, Toshiba Corporation, VSH, ADI, SLAB, TXN, Crocus Technology SA, Grandis, Inc., MagSil Corporation, Spintec, Spintron, and Spintronics Plc, IBM, CY, HON, and MOT. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Bashful Path to Female Bankruptcy
The unrelenting expansion in bankruptcies does not discriminate on gender – you either have the money or you do not. Naomi Wolf, author of Give Me Liberty: A Handbook for American Revolutionaries, recently shed light on the underbelly of those suffering severe financial pain in this economic crisis…middle-class women.
How bad is it for middle class women?
“A new report shows that a million American middle-class women will find themselves in bankruptcy court this year. This is more women than will ‘graduate from college, receive a diagnosis of cancer, or file for divorce,’ according to the economist Elizabeth Warren.”
Wolf explores multiple factors in trying to explain this phenomenon. Surprisingly, higher education levels does not appear to prevent a higher percentage of bankruptcies in this large demographic.
If education levels are not a contributing factor, then what is? Here are some Wolf’s findings:
1) Awash in Debt: One explanation for the extra debt reliance is many of these positions occupied by this class of women are lower-paying, which requires women to tap credit lines more frequently. Also, many women have been targeted by luxury-goods manufacturers and credit-card companies. Repeated contacts by the marketers have led to more women succumbing to the consumerism messages shoveled to them.
2) Credit Card Legislation: Wolf makes the case that financial credit card legislation introduced in 2005 disproportionately negatively impacts divorced wives because credit card companies get priority in the repayment line over critical child support payments. In other words, child support payments go to the credit card company rather than to the child, thereby creating an undue financial burden on the female caregiver.
3) Skewed Emotional Beliefs about Money: The biggest issue regarding the emotional connection to finances is working-women “find it embarrassing to talk about money.” The article even acknowledges that many current generation women earn more than previous generations, but financial security has largely not improved because of the “money taboo.” I discover this taboo dynamic in my practice all the time. Part of the blame should be placed on the financial industry’s use of endless acronyms as smoke and mirrors to confuse and intimidate clients on the subject of money. I believe the better way to financial success is to empower clients through education and understanding, not deception and misinformation.
Wolf goes onto explain some of the confused financial thought processes held by this segment of women:
- Negotiating salary increases is difficult for these women because it makes them feel “unfeminine.”
- This class often fails to save because they falsely assume marriage will save them financially.
Unfortunately, the lack of financial literacy and dependence on the spouse leaves these women vulnerable to divorce and widowhood.
Working Class Women Better Prepared
Interestingly, Wolf’s findings point to working class women being much more financially literate and prepared in part because they have erased the notion of a knight in shining armor saving the day from their financial responsibilities. Bolstering her argument, Wolf references the success of the micro-finance programs being instituted to lower-class, working women in developing countries.
Wolf’s Solution
How do middle-class working women break this negative financial cycle? Wolf delivers the medicine directly by directing these women to break the “social role that casts middle-class women as polite, economically vague, underpaid, shopping-dazed dependents.” Opening their eyes to these issues will not erase all of the contributing factors, but women will be better equipped to deal with their financial problems.
From my perspective, there is no quick fix for immediate financial literacy. For those interested in learning more, I encourage you to read my article on personal finance, What to Do Now? Time to Get Your House in Order.
Regardless of your financial knowledge maturity, like any discipline, the more time you put in to it, the more benefits you will receive.
Read Complete Naomi Wolf Article Here
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at time of publishing had no direct positions in any company mentioned in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Our Nation’s Keys to Success
Politics is not a subject I love to debate, but unfortunately politics has a significant impact on economics, which I do care about dearly. I’m no expert on the politics of New York City’s Mayor Michael Bloomberg, but in reflecting on the past decade he highlights a few key areas of focus needed to advance our great nation:
“There are two things that we did not work on and, in fact, have gone the wrong direction during the last decade, which will dictate the economy for the next decade, and that’s immigration and education.”
I couldn’t agree more. With regard to the country’s stimulus program, we hear so much about shovel-ready projects and infrastructure spending. Rather than centering on the immediate gratification of low-paying job creation and building bridges to nowhere, more resources should be invested in education and recruitment of leading edge human capital. Without a competitive and educated workforce, high-paying 21st Century jobs of the future will be lost and outsourced to global challengers.

Bloomberg emphasizes this point by stating:
“Unless we give our young people the kind of education to compete in the global world, we cannot survive.”
Sure, education is a longer-term investment with no immediate pay-off, but in order to become (remain) competitive with other hungry nations, we need to improve our high school education system, which Microsoft Founder and Chairman Bill Gates calls “obsolete”.
National Suicide
I agree with Mayor Bloomberg that the isolationist immigration pendulum has swung too far in the paranoid direction. The recent airline bombing attempt by Yemeni Umar Farouk Abdulmutallab only fans the flames of fear more intensely. However, in order to attract the best and brightest, we need to relax immigration policies – at least loosen policies as they pertain to educated, law-abiding citizens who can assist our dynamic growing economy. I have no problems with “cherry-picking” immigrants. The foundation of capitalism is based on attracting and retaining the best cherries. Bloomberg notes the following:
“And immigration, we’re committing what I call national suicide. Somehow or other, after 9/11 we went from reaching out and trying to get the best and the brightest to come here, to trying to keep them out. In fact, we do the stupidest thing, we give them educations and then don’t give them green cards.”
If fear of job loss is scaring us from letting foreigners in our country, then we need ask ourselves who will pay for our massive debts, deficits and entitlements (i.e., Social Security and Medicare)? Aging demographics is a huge headwind we face (see demographics article) and a quick glance across the Pacific Ocean to our Japanese allies is proof enough of how destructive the graying of society can become.
Also, many ask the question, “Why should we give American jobs to foreigners?” The reality of the situation is we need a competitve work-force to create a competitive country, which can create more sustainable jobs. How many jobs (and tax-dollars) do you think Google co-founder Sergey Brin (Russian-born) has created for American workers? Or Intel’s former CEO Andy Grove (Hungarian-born); Yahoo’s co-founder Jerry Yang (Taiwanese-born); and Sun Microsystem’s co-founders Vinod Khosla (Indian-born) and Andreas von Bechtolsheim (German-born)? More than a few.
Energy Independence
In his Meet the Press Interview, Bloomberg weaves in another issue dragging down the economy – our dependence on foreign oil. Importing more than 2/3 of our oil from foreign nations, many of which harbor or sponsor U.S.-hating terrorists, is not a prudent long-term strategy when it involves such a critical and strategic resource.
“We’ve got to get, somehow or other, energy independence. And so regardless of whether you’re a greenie or not, the bottom line is we cannot keep funding our enemies,” Bloomberg adds.
As the saying goes, the three most important political issues for re-election are: 1) the economy; 2) the economy; and 3) the economy. Unfortunately, short-term sugar-high stimulus spending may help the economy in the short-run but can wear off quickly if not implemented properly. On the other hand, three key strategic areas of investment will lead to sustainable economic expansion, including education, immigration, and energy independence. With new bitter mid-term Congressional elections waiting for us in 2010, let’s hope the candidates take a lead from Mayor Michael Bloomberg by building on his ideas for a firmer economic foundation in the decade to come.
View Meet The Press Roundtable Interview with Mayor Bloomberg (Minute 2:40)
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds and GOOG, but at time of publishing had no direct positions in MSFT, JAVA, YHOO, or INTC. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Top 10 Predictions for 2010
#10. Federal Reserve Chairman Ben Bernanke decides pundits were wrong on the housing bubble, so he sets Fed Funds target rate at negative -3.0%. Small businesses start receiving loans.
#9. As part of healthcare reform, Medicare is extended to teens for collagen lip augmentation.
#8. Goldman Sachs, Morgan Stanley, and Citigroup form tri-merger to guarantee they are too big to fail.
#7. Tiger Woods poses in Playgirl to pay for pricey revised terms in his prenup. (see previous post)
#6. Gold spikes to $3,000 per ounce as government subsidizes dental chains in “cash for crowns” gold melting campaign. Consumers get extra cash, but Jujube candy sales plummet. (see previous post)
#5. Bernie Madoff escapes from prison. A cigarette Ponzi Scheme created by Madoff generates enough money to bribe guards.
#4. Apple introduces iPot – a combination iPhone and toilet.
#3. Kazakhstan pays Brazil, Russia, India and China a 5% GDP royalty to be added to the emerging B-R-I-C-K countries. A win-win for all parties, including spelling teachers around the world.
#2. Timothy Geithner retires from Treasury after making millions for being cast as Eddie Haskell in new remake of Leave It to Beaver movie. (see previous post)
#1. Oprah decides to halt her retirement plans. Instead, she signs me to a multi-million dollar deal to co-host a stock & gossip show with her.
HAPPY 2010!!
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (including BKF) and AAPL, but did not have any direct positions in any stock mentioned in this article at time of publication (including GS, MS, C, and GLD). No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Decade in Review

We laughed, we cried, we kissed another ten years goodbye. It is virtually impossible to cram ten years into one article, nonetheless I will attempt to chronicle some of the central and silly events that bubble up in my memory bank.
2000
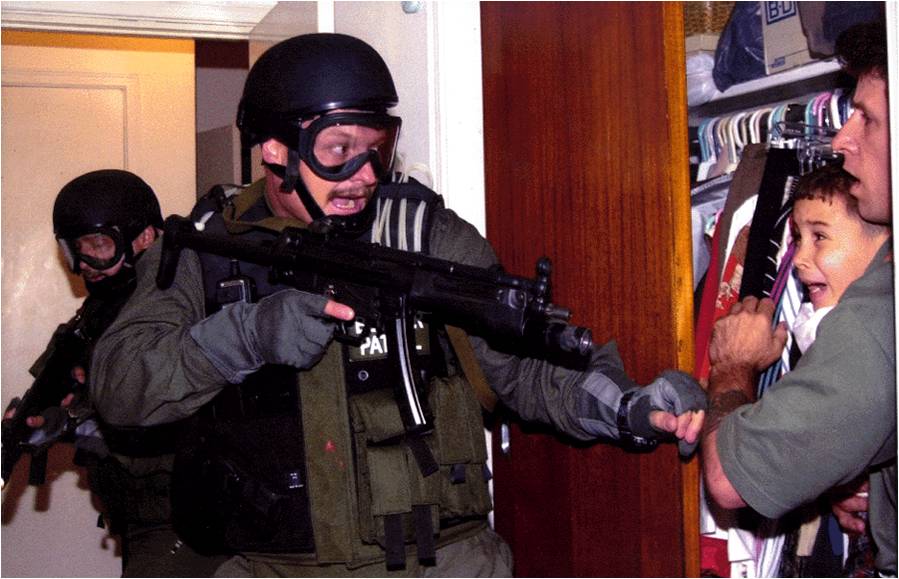
Capture of Elian Gonzalez
- Technology-heavy NASDAQ index peaks at 5,132 before completing its -78% decline by late 2002.
- Y2K (Year 2000) fears do not materialize and technology orders begin downward slide.
- AOL buys Time Warner for $164 Billion in hopes of converging media and internet worlds.
- Al Gore Democratic nominee for the Presidency wins popular vote but loses election to George Bush after effort for Florida recount fails.
- Elian Gonzalez, six-year old boy returned to Cuba.
- Reality TV show Survivor finishes first season with Richard Hatch winning prize.
2001
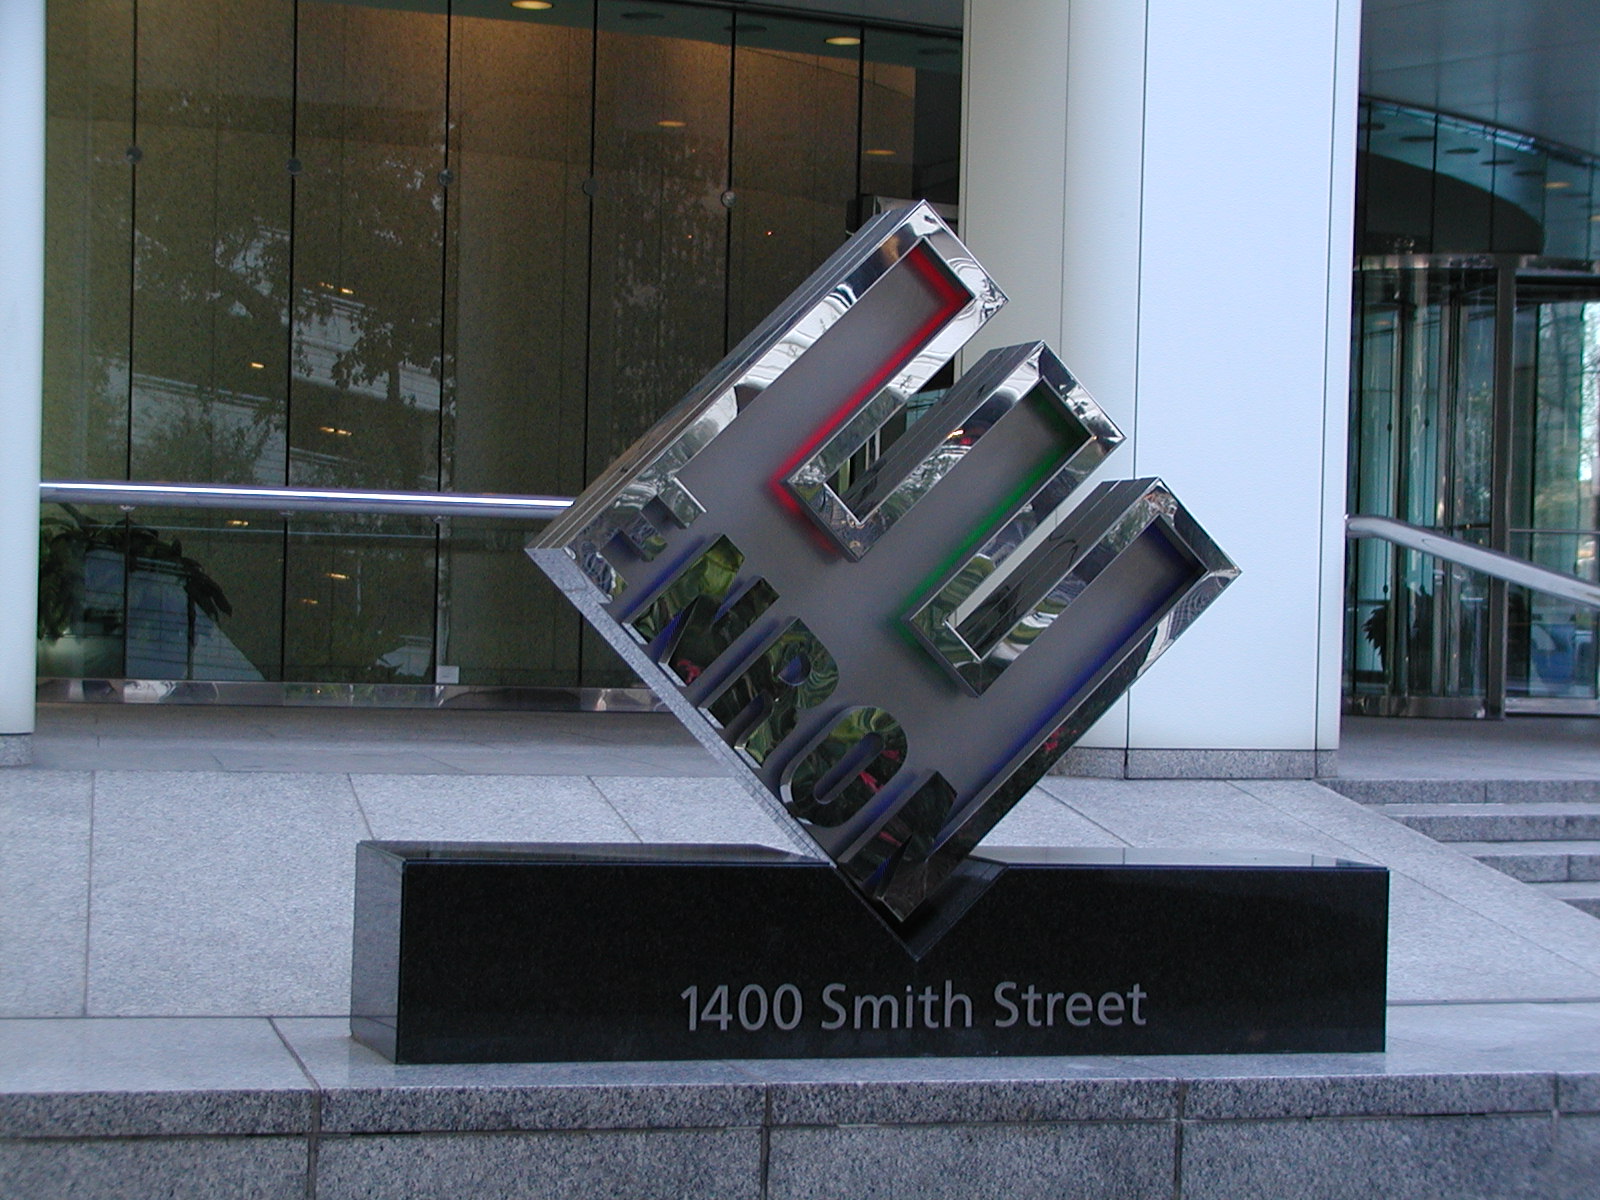
Enron Logo at Headquarters
- Apple introduces iPod digital music player.
- Enron files Chapter 11 bankruptcy.
- Wikipedia online community encyclopedia launches.
- 9/11 attacks occur pushing economy further down.
- Alan Greenspan starts 1st of 11 rate cuts in 2001.
- China joins WTO (World Trade Organization).
2002
- Severe Acute Respiratory Syndrome (SARS), an atypical form of pneumonia, rears its ugly head in the Guangdong Province of China.
- SEC files charges against WorldCom and Tyco international in connection with accounting irregularities
- United Airlines files for bankruptcy.
- American Idol television singing contest begins first season.
- Guantanomo Bay detention camp is opened.
2003
- Federal Funds rate reaches a 45 year low at 1.00% – fuel for future credit bubble.
- $350 billion in tax cuts approved, spanning a ten year period.
- Iraqi Gulf War II commences with “shock and awe” military campaign.
- Space Shuttle Columbia disintegrates upon attempted reentry into the Earth’s atmosphere.
- Broad stock market recovery (>90% of stocks in S&P500 climb), including a +50% rise in the NASDAQ index.
- Martha Stewart indicted for using privileged investment information and then obstructing a federal investigation.
- Arnold Schwarzenegger, movie star, becomes governor of California.
2004

- Google (GOOG) goes public with IPO at $85 per share.
- Mark Zuckerberg unveils Facebook and people begin “friending” each other.
- Comcast makes failing unsolicited bid for Disney. K-Mart buys Sears with aid of Eddie Lampert
- Ronald Reagan, 40th President, dies at 93.
- Janet Jackson and Justin Timberlake experience “wardrobe malfunction” on Super Bowl halftime show.
- Boston Red Sox win their first World series since 1918.
2005
- P&G announces $57 billion acquisition of Gillette. Conoco Philips buys Burlington Resources for over $30 billion. Bank of America buys credit card company MBNA.
- Ben Bernanke is nominated as new Federal Reserve Chairman.
- Hurricane Katrina overwhelms New Orleans as 80% of city becomes covered with water.
- North Korea announces its nuclear weapons arsenal.
- YouTube starts sharing online videos before Google Inc. eventually buys company.
- Lance Armstrong wins 7th consecutive Tour de France.
2006
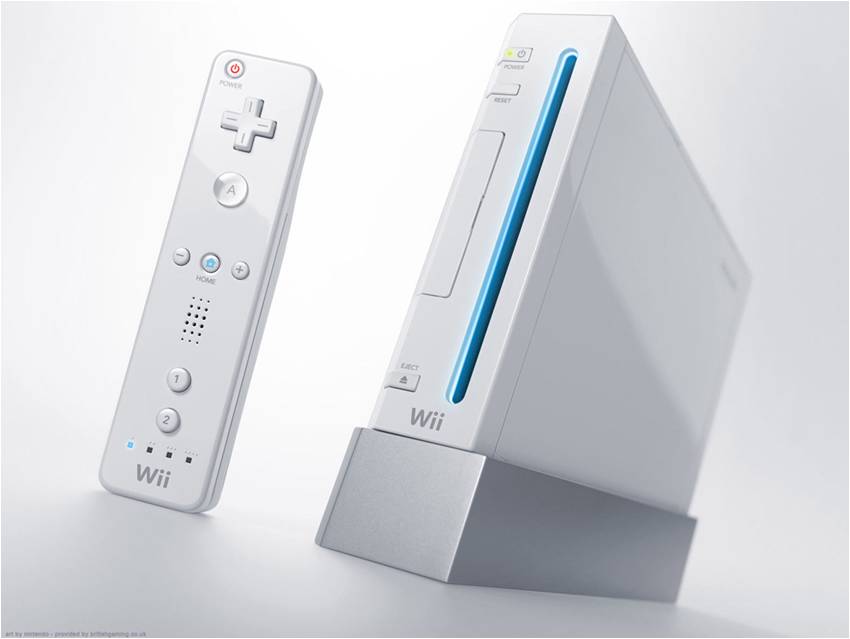
- Inverted yield curve turns out to be an accurate leading indicator for 2008 recession despite markets advance.
- Internet activity accelerates: Google buys YouTube after News Corp buys MySpace. Twitter is introduced.
- Playstation 3 (PS3) and Nintendo Wii unveiled.
- Merger & acquisition activity reaches $3.79 trillion worldwide, surpassing previous 2000 peak (Thomson).
- Options backdating takes center stage. United Health and technology companies were among those dragged into controversy.
- Housing market peaks.
2007
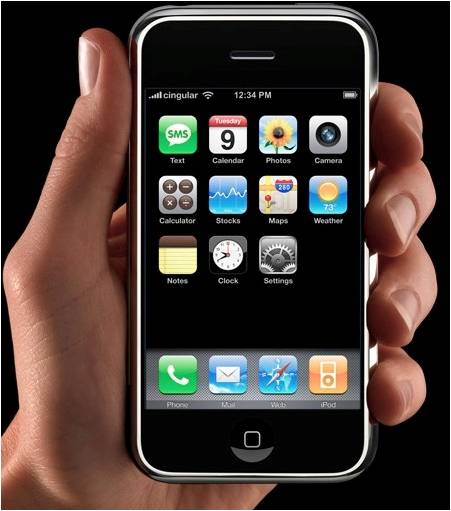
- Markets continue multi-year rally with three major indexes holding single-digit gains. Emerging markets build on previous year gains – Shanghai composite +97%.
- Monoline insurers MBIA and rival Ambac become early canaries in the coal mine given the greater than $1 trillion in exposure on insuring securities.
- Apple presents the iPhone – part phone, part music, part computer.
- KKR (Kohlberg Kravis Roberts & Co.) and TPG complete $44.4 billion buyout of Texas power company TXU Corp.
- Microsoft Vista operating system introduced after five years of development.
- Housing decline accelerates as Countrywide Financial announces 12,000 job cuts (20% of its workforce), New Century Financial (#2 subprime lender at one point) files Chapter 11 bankruptcy, and two Bear Stearns mortgage based hedge funds go under.
- Chuck Prince, Citigroup CEO, steps down.
2008

- Bank of America agrees to buy Countrywide mortgage company for about $4 billion.
- JPMorgan Chase agrees to buy Bear Stearns for $2 per share in a sale brokered by the Fed and the U.S. Treasury – eventually bid revised upwards to $10 per share (~$1.1 billion) to appease angry shareholders.
- Lehman Brothers goes bankrupt.
- Bank of America agrees to acquire Merrill Lynch for about $50 billion.
- Government takes over AIG after providing insurance company $85 billion loan.
- Goldman Sachs and Morgan Stanley become bank holding companies to improve access to capital.
- Washington Mutual Inc. is seized by FDIC and sold to JPMorgan Chase in the biggest U.S. bank failure in history.
- Wells Fargo & Co., agrees to purchase Wachovia for about $15.1 billion, trumping Citigroup’s bid.
- $700 billion TARP (Troubled Asset Relief Program) eventually approved by Congress to stabilize financial system.
- Eliot Spitzer resigns after prostitution scandal.
- Michael Phelps wins eight gold medals at the 2008 Beijing Summer Olympics.
2009
- Barack Obama inaugurated in as 44th President of the United States. Healthcare reform bills pass in both the House and Senate.
- GM and Chrysler declare bankruptcy.
- Recession ends as stimulus kicks in and inventories rebuild. Government announces new PPIP and TALF programs.
- Warren Buffett pays $26 billion to buy Burlington Northern Santa Fe. Other announcements include: Oracle /Sun Microsystems; Pfizer/Wyeth; Merck/Schering Plough; and Pulte Homes/Centex.
- Commodities and emerging markets rebound. Gold tops $1,000 per ounce.
- Signs of housing bottoming as low mortgage rates, tax credits, and declining inventories create a more constructive environment.
- Madoff goes to prison after he was convicted for a $65 billion Ponzi Scheme.
- Chesley B. “Sully” Sullenberger successfully carries out the treacherous crash-landing of US Airways Flight 1549 into the Hudson River.
- Dubai debt debacle forces Abu Dhabi to lend support to calm global markets.
- Tiger Woods admits transgressions after car crash pushes him into spotlight.
2010 ???
Time will tell what the new year will bring. Stay tuned for some iron clad 2010 predictions coming to an Investing Caffeine blog near you in the not too distant future!
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds and BAC, AAPL, and GOOG, but did not have any direct positions in the following stocks mentioned in this article at time of publication (including AOL/TWX, VIA/CBS, NWS, TYC, UAUA, MSO, CMCSA, DIS, SHLD, PG, COP, Nintendo, MBI, ABK, MSFT, C, JPM, AIG, MS, WFC, GM, Chrysler, BRKA, ORCL, JAVA, PFE, MRK, PHM, BNI, LCC, GLD, and NKE). No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Too Big to Fail (Review)
Some call Andrew Ross Sorkin’s new behind-the-scenes book about the financial crisis of 2008-2009 “Too Big to Read” due to its meaty page count at 624 pages (a tad more than my book). But actually, once you crack the first chapter of Too Big to Fail you become immediately sucked in. In creating the “fly on the wall” perspective covering the elite power brokers of Wall Street and Washington, Sorkin utilizes 500 hours of interviews with more than 200 individuals.
Through the detailed and vivid conversations, you get the keen sense of overwhelming desperation and self-preservation that overtakes the executives of the sinking financial system. Some of the chief participants failed, some were triumphant, and some were pathetically bailed out. History will ultimately be the arbiter of whether government and Wall Street averted, mitigated, postponed, or contributed to the financial collapse. Regardless, Sorkin brilliantly encapsulates this emotionally panicked period in our history that will never be erased from our memories.
Here are a few passages that capture the feeling and mood of the book:
Merger Musical Chairs
The terror-induced insanity of merger musical chairs is best depicted through the notepad of Timothy Geithner, then the president of the New York Federal Reserve Bank:
“On a pad that morning, Geithner started writing out various merger permutations: Morgan Stanley and Citigroup. Morgan Stanley and JP Morgan Chase. Morgan Stanley and Mitsubishi. Morgan Stanley and CIC. Morgan Stanley and Outside Investor. Goldman Sachs and Citigroup. Goldman Sachs and Wachovia. Goldman Sachs and Outside Investor. Fortress Goldman. Fortress Morgan Stanley. It was the ultimate Wall Street chessboard.”
AIG Bombshell
The book is also laced with financial nuggets to put the scope of the crisis in perspective. Here Sorkin examines the distressed call of assistance from AIG CEO, Bob Willumstad, to Timothy Geithner:
“A bombshell that Willumstad was confident would draw Geithner’s attention-was a report on AIG’s counterparty exposure around the world, which included ‘$2.7 trillion of notional derivative exposures, with 12,000 individual contracts.” About halfway down the page, in bold, was the detail that Willumstad hoped would strike Geithner as startling: “$1 trillion of exposures concentrated with 12 major financial institutions.’”
Bernanke’s Bumbled Spelling Bee
In setting the stage for the drama that unfolds, Sorkin also provides a background on the key players in the book. For example in describing Ben Bernanke you learn he was
“born in 1953 and grew up in Dillon South Carolina, a small town permeated by the stench of tobacco warehouses. As an eleven-year-old, he traveled to Washington to compete in the national spelling championship in 1965, falling in the second round, when he misspelled ‘Edelweiss.’”
TARP Tidbits
On how the precise $700 billion TARP (Troubled Asset Relief Program) figure was created, Sorkin describes the scattered thought process of the program designer Neel Kashkari:
“They knew they could count on Kashkari to perform some sort of mathematical voodoo to justify it: ‘There’s around $11 trillion of residential mortgages, there’s around $3 trillion of commercial mortgages, that leads to $14 trillion, roughly five percent of that is $700 billion.’ As he plucked numbers from thin air even Kashkari laughed at the absurdity of it all.”
Mercedes Moment
Mixed in with the facts and downbeat conversations are a series of humorous anecdotes and one-liners. Here is one exchange between Goldman Sachs CEO, Lloyd Blankfein, and his Chief of Staff Russell Horwitz:
“’I don’t think I can take another day of this,’ Horowitz said wearily. Blankfein laughed. ‘You’re getting out of a Mercedes to go to the New York Federal Reserve – you’re not getting out of a Higgins boat* on Omaha Beach! Keep things in perspective.’”
*Blankfein’s quote: A reference to the bloody D-Day battle.
Too Big to Fail is an incredible time capsule for the history books. Let’s hope we do not have to relive a period like this in our lifetimes. I wouldn’t mind reading another Andrew Ross Sorkin book…just not another one about a future financial crisis.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but did not have any direct positions in any stock mentioned in this article at time of publication (including GS, AIG, WFC, MS, and C). No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Poetic Holiday Dividend
Stocks can rise and they can fall
Emotions can suffer withdrawal
What remains firm are feelings for those we love
Whether by the Christmas tree or in our hearts above
‘Tis the time of year to give thanks and reflect
But forget not ailing lost souls that deserve our respect
2009 included its share of pain and sorrow
For 2010 I wish all a prosperous and brighter tomorrow
-Wade W. Slome
Plan. Invest. Prosper.
Mobius: The Kojak of Emerging Markets
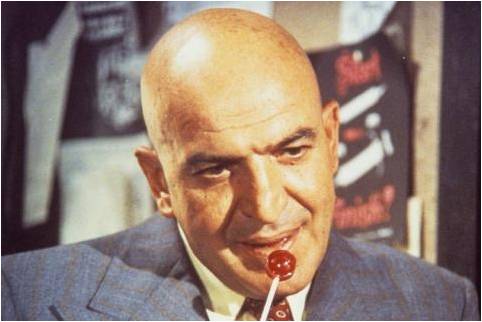
Kojak substituting lollipops for nicotine.
Lieutenant Theo Kojak, played by Telly Savalas in the 1970s television series Kojak, is a bald, hard-nosed New York City police detective who hunts down criminals. Mark Mobius, executive chairman of Templeton Asset Management, is a bald, hard-nosed investment manager devoted to hunting down winning stocks in emerging markets. Expanding on his numerous authored books, Mobius recently decided to write his own blog expanding on his global travels and reporting back his investment findings.
Recently Mobius fielded some questions from his readers, covering emerging markets from China and Brazil to “Frontier” markets like Sri Lanka and Serbia (see also Trade of the Century). Here are a few of the exchanges:
In which countries, regions or sectors are you finding the best values?
“We are finding opportunities in almost all emerging markets. Our ground-up research process locates opportunities in countries where the political or economic outlooks may not, at first appearance, look good. Nevertheless, we generally favor China and Brazil, but also have large positions in Russia, India and Turkey. In terms of sectors, we believe commodity stocks look good because we expect the global demand for commodities to continue its long-term growth. We also favor consumer stocks. With rising per-capita income and strong demand for consumer goods and services in many emerging markets, we believe the earnings growth outlook for these stocks is positive.”
It appears that the financial market has changed, in that one needs to be more skeptical and cautious when investing than in the past. Alan Greenspan said that last year’s crash was unforeseen, and given the uncertainty of the markets and global financing, the big crash could happen again. What say you?
“Actually some analysts did see the crash coming in view of Greenspan’s loose monetary policies. The nature of markets is that there will always be booms and crashes since people tend to get either too optimistic or too pessimistic. The good news is that on average, bull markets have lasted longer than bear markets, and bull markets have gone up in percentage terms more than bear markets have gone down. In terms of other risks, I believe there is still a danger of the unregulated derivatives market.
Do you think Sri Lanka will turn around?
“We believe that Sri Lanka is fundamentally a rich country and that the challenges revolve around how the true potential in tourism, agriculture and industry can be effectively met. We have been investing in Sri Lanka for many years. For us, the biggest challenge in the public market is liquidity. Trading turnover is rather low although we have found some investment bargains.”
Belgrade’s Stock Exchange suffered heavy losses in the 2008 meltdown, with the Belex index falling sharply. I am from Serbia, and so I was thrilled to find out that Franklin Templeton is investing in Serbia.
“Yes, we are interested in the Serbian market and we are now looking at opportunities there. Of course, when markets are down, it is the best time to start looking and Belgrade is definitely on our list. We have already invested in a company in Serbia and look forward to looking more closely at that market.”
Mark Mobius - Not Moby
While Telly Savalas discovered fame 30 years ago from his Kojak role, Mr. Mobius has spent more than 30 years in the emerging markets chasing successful investments. Franklin Templeton Investors should remain happy if Mobius’ picks continue to shine, like his bald, polished crown.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (EEM, FXI, BKF). No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Can the Lost Decade Strike Twice?

There is an old saying that lightning does not strike twice in the same place. I firmly believe this principle will apply to stock returns over the next decade. Josh Brown, investor and writer for The Reformed Broker highlighted a chart published by Bloomberg showing the 10-year return for various asset classes. Statisticians and market commentators have been quick to point out that stocks, as measured by various benchmarks, have not only underperformed bonds for the last 10 years, but stock performance has actually also been negative for the trailing decade.
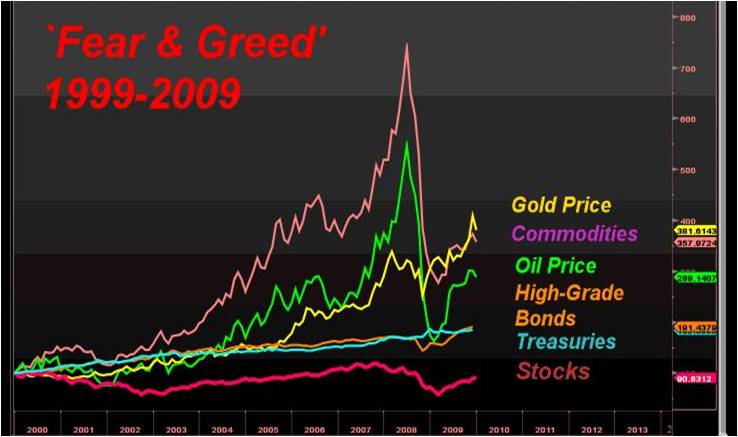
Source: Bloomberg via The Reformed Broker
Will this trend persist during the next decade? Will the lost decade in stocks be repeated again, similar to the deflation death spiral experienced by the Japanese? (Read more regarding Japanese market on IC). With the Fed Funds rate at effectively zero, is it possible bonds can pull off a miracle over the next 10 years? I suppose anything is possible, but I seriously doubt it.
Let’s not forget that the P/E ratio (Price-Earnings) pegged by some to be at about 14-15x’s 2010 expected earnings – nestled comfortably within historical bands. Granted, financials and some other sectors were overheated (e.g. certain Consumer industries), but based on next year’s estimates, some industries are already expected to exceed the peak earnings achieved during 2007 (e.g., Technology).
History on Our Side

Source: Crestmont Research. Dated graph over the last century showing stock returns rarely result in negative returns over a rolling 10 year period.
For the trailing decade using December 20, 2009 as an end point, I arrive at a marginally negative return for the S&P 500 index assuming an average dividend yield of 2.5% for the period. Certainly the negative return would be pronounced by any fees, commissions or taxes related to a 10-year buy-and-hold strategy of the broad market index. This chart gets chopped off in 2005, nonetheless history is on our side, lending support that stock returns have a good chance of improving on the results over the last 10 years.
Equity Risk Premium
The bubbles and scandals that have blanketed corporate America over the last 10 years have made the average investor extremely skeptical. What does this mean for the pricing of risk? Well, if you rewind to the year 2000 when technology exceeded 50% of some indexes, and many investors thought technology was a low risk endeavor, there was virtually no equity risk premium discounted into many stock prices. If you fast forward to today, the reverse is occurring. Investors despise market volatility and arguably demand a much higher risk premium for taking on the instability of stocks. This is the exact environment investors should desire – lots of skepticism and money piled into bonds (See IC article on investor queasiness). As Warren Buffett says, “Be fearful when others are greedy and greedy when others are fearful.” I believe the next 10 years will be a time to be greedy.
The analysis above is obviously very narrow in scope, since we are only discussing domestic stock markets. In my client portfolios I advocate a broadly diversified portfolio across asset classes (including bonds), geographies, and styles. However, in managing bonds across portfolios, I am forced to tactfully include strategies such as inflation protection and shorter duration techniques. With the year-end fast approaching, now is a good time to review your financial goals and asset allocation.
Lightning definitely negatively impacted stocks this decade, but betting for lightning to strike twice this decade could very well turn out to be a losing wager.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at time of publishing had no direct positions in BRKA. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.



 Investing Caffeine

