Sports & Investing: Why Strong Earnings Can Hurt Stock Prices
There are many similarities between investing in stocks and handicapping in sports betting. For example, investors (bettors) have opposing views on whether a particular stock (team) will go up or down (win or lose), and determine if the valuation (point spread) is reflective of the proper equilibrium (supply & demand). And just like the stock market, virtually anybody off the street can place a sports bet – assuming one is of legal age and in a legal betting jurisdiction.
Right now investors are poring over data as part of the critical, quarterly earnings ritual. Thus far, roughly 20% of the companies in S&P 500 index have reported their results and 78% of those companies have beaten Wall Street expectations (CNBC). Unfortunately for the bulls, this trend has not been strong enough to push market prices higher in 2010.
So how and why can market prices go down on good news? There are many reasons that short-term price trends can diverge from short-run fundamentals. One major reason for the price-fundamental gap is the following factor: expectations. Just last week, the market had climbed over +70% in a ten month period, before issues surrounding the Massachusetts Senatorial election, President Obama’s banking reform proposals, and Federal Reserve Bank Chairman Ben Bernanke’s re-appointment surfaced. With such a large run-up in the equity markets come loftier expectations for both the economy and individual companies. So when corporate earnings unveiled from companies like Google (GOOG), J.P. Morgan (JPM), and Intel (INTC) outperform relative to forecasts, one explanation for an interim price correction is due to a significant group of investors not being surprised by the robust profit reports. In sports betting lingo, the sports team may have won the game this week, but they did not win by enough points (“cover the spread”).
Some other reasons stock prices move lower on good news:
- Market Direction: Regardless of the underlying trends, if the market is moving lower, in many instances the market dip can overwhelm any positive, stock- specific factors.
- Profit Taking: Many times investors holding a long position will have price targets or levels, if achieved, that will trigger selling whether positive elements are in place or not.
- Interest Rates: Certain valuation techniques (e.g. Discounted Cash Flow and Dividend Discount Model) integrate interest rates into the value calculation. Therefore, a climb in interest rates has the potential of lowering stock prices – even if the dynamics surrounding a particular security are excellent.
- Quality of Earnings: Sometimes producing winning results is not enough (see also Tricks of the Trade article). On occasion, items such as one-time gains, aggressive revenue recognition, and lower than average tax rates assist a company in getting over a profit hurdle. Investors value quality in addition to quantity.
- Outlook: Even if current period results may be strong, on some occasions a company’s outlook regarding future prospects may be worse than expected. A dark or worsening outlook can pressure security prices.
- Politics & Taxes: These factors may prove especially important to the market this year, since this is a mid-term election year. Political and tax policy changes today may have negative impacts on future profits, thereby impacting stock prices.
- Other Exogenous Items: Natural disasters and security attacks are examples of negative shocks that could damage price values, irrespective of fundamentals.
Certainly these previously mentioned issues do not cover the full gamut of explanations for temporary price-fundamental gaps. Moreover, many of these factors could be used in reverse to explain market price increases in the face of weaker than anticipated results.
For those individuals traveling to Las Vegas to place a wager on the NFL Super Bowl, betting on the hot team may not be enough. If expectations are not met and the hot team wins by less than the point spread, don’t be surprised to see a decline in the value of the bet.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds and GOOG, but at the time of publishing had no direct positions in JPM and INTC. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Flogging the Financial Firefighter

There we were in the fall of 2008, our economic system burning up in flames, as we all watched century-old financial institutions falling like flies. At the center of the inferno was Federal Reserve Chairman Ben Bernanke. In coordination with other government agencies and officials, Bernanke managed to prevent the worse financial crisis since the Great Depression from completely scorching the economy into ruin. After successfully hosing down the flames (at least temporarily), Ben Bernanke is now being singled out as the scapegoat and getting flogged for being a major participant in the financial crisis.
Execution Threatened Water Damage
In hind-sight could Bernanke have made better decisions? Certainly. Despite the Federal Reserve dousing out the flames, politicians are pointing the finger at Bernanke for causing water damage. I’m going to go out on a limb and say water damage is preferable to the alternative – a whole community of properties burned down to a large pile of charred ash.
Democrats are now flailing in the wake of the Massachusetts Democratic Senate seat loss to Republican Scott Brown. Even though I question President Obama’s blame-game tax and overhaul tactics (see Surgery or Amputation article), to his credit Obama realizes the instability of mass proportion that would occur if the reappointment of Bernanke were to come to fruition. If the head of the globe’s largest financial system is going to be kicked to the curb after saving our economy at the edge of an abyss, then heaven please help us.
Politics Will Reign Supreme in 2010
“Change” was promised in the 2008 Presidential election and the impatient natives are not seeing results fast enough, given lofty unemployment rates and unsuccessful implementation of other initiatives (thus far). Needless to say, the media is going to be awash in an orgy of political mudslinging and campaign promises that will overwhelm the airwaves for the balance of the year.
From a market standpoint, Republicans and Democrats, alike, do share some common ground…jobs. As a countervailing trend to the forces dragging down the economy, the unified focus on job creation should provide some support to the financial markets.
Unfortunately, the independence of the Federal Reserve is being dragged into the political ring as Ben Bernanke’s reappointment process cannot escape the Capitol Hill circus. Berkshire Hathaway (BRKA/B) CEO Warren Buffett has likely handicapped the market’s reaction to a failed Bernanke reappointment when he recently stated, “Just tell me a day ahead of time so I can sell some stocks.” If the fires of 2008 concerned you, you may want to have your fire alarm and water hose ready for action if Chairman Bernanke is shown the exit.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and at the time of publishing had no direct positions in BRKA/B. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Banking Surgery or Amputation?

Photo Source: (c)iStockphoto.com Artist: Powerofforever
Deciding whether to sever the proprietary trading arms of the commercial banks, rather than instituting regulation, seems a lot like deciding whether amputation is a healthier path for those suffering terrible frostbite cases. Even if this legislation is unlikely to pass, I find the recommendations severe in relation to other measured alternatives. I’m no right-wing conspiracy theorist, but I don’t think the timing of the Obama administration’s announcement is coincidental. Why is this proposal surfacing two years into the financial crisis and a whole year after the President entered office?
Politicians have always been masterful at introducing coincidental distractions at opportune times, in order to generate patriotic voter sympathies. Some examples include, Margaret Thatcher in the Falkand Islands; George Bush #41 in the Iraqi war; and President Obama’s current ant-banker populist brigade. Perhaps miserable and declining approval ratings and a healthcare bill on the verge of collapse may have something to do with the timing? I want President Obama to succeed, and he may have good intentions, but let’s not rush to an overzealous knee-jerk reactions before other less-draconian solutions are thoroughly explored.
Glass-Steagall Redux
Theoretically, the argument of forcing banks to adopt lower risk sounds great on paper. Overall, I think this initiative is a worthy one Americans could buy into. As a matter of fact, investment guru Jeremy Grantham makes the same argument in my Investing Caffeine article (“Too Big to Sink”). However, I think a more relevant question is, “How do we implement more responsible risk taking by the banks, without a massive overhaul to the system?” Certainly there were some regulators asleep at the switch, and some financial institutions that pushed the envelope on risk assumption, but I’m not convinced a return to Glass-Steagall (or Glass-Steagall Lite) is going to bring miracles. If the regulators cannot adequately curb risk taking by the banks, then cross the more dangerous bridge later. The economy is presently in the midst of a fragile recovery and we do not want to change the airplane engine during mid-flight.
Political Pendulum Swings
This isn’t the first time Washington has reversed previous decisions. If the cries of voters reach a feverish pitch, and these wishes coincide with a politician’s re-election agenda, then the probabilities of sub-optimal, rushed legislation increases. Consider AT&T (T), which because of antitrust concerns was forced to split operations in 1982. Lo and behold, some twenty years later, we witnessed the re-consolidation of the “Baby Bells” back into AT&T. Now, Glass-Steagall is the topic of conversation and with an unambiguous scapegoat needed by politicians, Washington is targeting the banks with taxes and operations splitting.
Hasty legislation is nothing new with the populist flames fanning in the background. Sarbanes-Oxley is another example of less-than-ideal legislation introduced in the wake of relatively low number of corporate scandals, such as Enron, WorldCom, and Tyco (TYC).
Regulation Reform Solution
Here are 3 constructive steps:
1) Institute transparent trading of derivatives (i.e., Credit default Swaps) over exchanges with adequately capitalized clearing houses.
2) Require higher capital requirements for banks conducting proprietary trading and mandate adequate disclosure.
3) Consolidation of regulators, thereby creating a more simplified, accountable structure (see also Regulatory Web article). Savings from redundant costs could be used to hire additional regulatory oversight staff.
Blood is in the streets and with mid-term elections just around the corner, the Obama administration is looking to salvage anything they can bring back to the voters. Frost bite (and greedy bankers) is a painful and horrible predicament, however if healthy functioning limbs can be saved with targeted surgery rather than amputation, then I vote for this solution.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (including VFH), and at the time of publishing had no direct positions in T, TYC. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
John Paulson and the “Gutsiest” Trade Ever

Although the pain and suffering of the 2008-09 financial crisis has been well documented and new books are continually coming out in droves, less covered are the winners who made a bonanza by predicting the collapse of the real estate and credit markets. Prizewinning Wall Street Journal reporter Gregory Zuckerman decided to record the fortunes made by hedge fund manager John Paulson in his book The Greatest Trade Ever (The Behind-the-Scenes story of How John Paulson Defied Wall Street and Made Financial History).
Paulson’s Cartoonish Cut
Zuckerman puts Paulson’s massive gains into perspective:
“Paulson’s winnings were so enormous they seemed unreal, even cartoonish. His firm, Paulson & Co., made $15 billion in 2007, a figure that topped the gross domestic products of Bolivia, Honduras, and Paraguay…Paulson’s personal cut was nearly $4 billion…more than the earnings of J.K. Rowling, Oprah Winfrey, and Tiger Woods put together.”
As impressive as those gains were, Paulson added another $5 billion into his firm’s coffers and $2 billion into his personal wallet over 2008 and early 2009.
There are many ways to skin a cat, and there are countless strategies used by the thousands of hedge fund managers looking to hit the jackpot like Paulson. John Paulson primarily made his multi-billion fortune thanks to his CDS positions (Credit Default Swaps), the same product that led to massive multi-billion bailouts and government support for various financial institutions.
Bigger Gamble than Perception
One surprising aspect I discovered from reading the book was the uncertainty surrounding Paulson’s negative real estate trade. Here’s how Zuckerman described the conviction level of John Paulson and Paolo Pelligrini (colleague) as it related to their CDS positions on subprime CDO (Collateralized Debt Obligation) debt:
“In truth, Paulson and Pellegrini still were unsure if their growing trade would ever pan out. They thought the CDOs and other risky mortgage debt would become worthless, Paulson says. ‘But we still didn’t know.’”
Often the trades that cause you to sweat the most tend to be the most profitable, and in this case, apparently the same principle held.
Disingenuous Dramatic License
Before Paulson made his billions, Zuckerman uses a little dramatic license in the book to characterize Paulson as a small fry manager, “Paulson now managed $1.5 billion, a figure that sounded like a lot to friends outside the business. But the firm was dwarfed by its many rivals.” Zuckerman goes on to call Paulson’s hedge fund “small potatoes.” I don’t have the industry statistics at my fingertips, but I’ll go out on a limb and make an educated guess that a $1.5 billion hedge fund has significantly more assets than the vast majority of hedge fund peers. Under the 2 and 20 model, I’m guessing the management fee alone of $30 million could cover Paulson’s food and shelter expenses. Before he struck the payload, the book also references the $100 million of his personal wealth he invested with the firm. I think John Paulson was doing just fine before he executed the “greatest trade.”
What Drove the Greatest Trade
Hind sight is always 20/20, but looking back, there was ample evidence of the real estate bubble forming. Fortunately for Paulson, he got the timing generally right too. Here are some of the factors leading to the great trade:
- CDO Leverage in Subprime: By the end of 2006, the subprime loan market was relatively large at around $1.2 trillion (representing around 10% of the overall mortgage market). But thanks to the introduction of CDOs, there were more than $5 trillion of risky investments created from all the risky subprime loans.
- Liars & Ninjas: “Liar Loans” loans based on stated income (using the honor system) and “ninja loans” (no income, no job, no assets) gained popularity and prevalence, which just led to more defaults and foreclosures in the mid-2000s.
- No Down Payments: What’s more, by 2005, 24% of all mortgages were completed with no down payment, up from approximately 3% in 2001. The percentage of first-time home buyers with no down payment was even higher at 43%.
Overall, I give kudos to Gregory Zuckerman, who spent more than 50 hours with John Paulson, for bringing something so abstract and homogenous (a skeptical real estate trade) to life. Zuckerman does a superb job of adding spice to the Paulson story by introducing other narratives and characters, even if the story lines don’t blend together perfectly. After reading The Greatest Trade Ever I came away with a new found respect for Paulson’s multi-billion dollar gutsy trade. Now, Paulson has reloaded his gun and is targeting the U.S. dollar. If Paulson’s short dollar and long gold position works out, I’ll keep an eye out for his next book…The Greatest Trad-er Ever.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (including VNQ), but at time of publishing had no direct positions in companies mentioned. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Mauboussin Takes the Outside View
Michael Mauboussin, Legg Mason Chief Investment Strategist and author of Think Twice, is a behavioral finance guru and in his recent book he explores the importance of seriously considering the “outside view” when making important decisions.
What is Behavioral Finance?
Behavioral finance is a branch of economics that delves into the non-numeric forces impacting a diverse set of economic and investment decisions. Often these internal and external influences can lead to sub-optimal decision making. The study of this psychology-based discipline is designed to mitigate economic errors, and if possible, improve investment decision making.
Two instrumental contributors to the field of behavioral finance are economists Daniel Kahneman and Amos Tversky. In one area of their research they demonstrated how emotional fears of loss can have a crippling effect in the decision making process. In their studies, Kahneman and Tversky showed the pain of loss is more than twice as painful as the pleasure from gain. How did they illustrate this phenomenon? Through various hypothetical gambling scenarios, they highlighted how irrational decisions are made. For example, Kahneman and Tversky conducted an experiment in which participating individuals were given the choice of starting with an initial $600 nest egg that grows by $200, or beginning with $1,000 and losing $200. Both scenarios created the exact same end point ($800), but the participants overwhelmingly selected the first option (starting with lower $600 and achieving a gain) because starting with a higher value and subsequently losing money was not as comfortable.
The impression of behavioral finance is burned into our history in the form of cyclical boom, busts, and bubbles. Most individuals are aware of the technology bubble of the late 1990s, or the more recent real estate/credit craze, however investors tend to have short memories are unaware of previous behavioral bubbles. Take the 17th century tulip mania, which witnessed Dutch citizens selling land, homes, and other assets in order to procure tulip bulbs for more than $70,000 (on an inflation-adjusted basis), according to Stock-Market-Crash.net. We can attempt to delay bubbles, but they will forever be a part of our economic fabric.
The Outside View
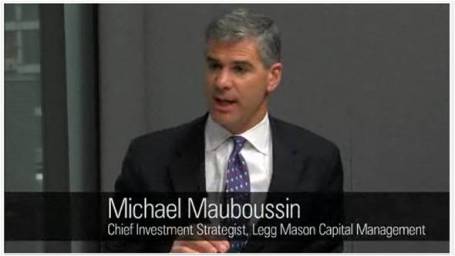 Click here for Michael Mauboussin interview with Morningstar
In his book Think Twice Mauboussin takes tenets from behavioral finance and applies it to individual’s decision making process. Specifically, he encourages people to consider the “outside view” when making important decisions.
Mauboussin makes the case that our decisions are unique, but share aspects of other problems. Often individuals get trapped in their heads and internalize their own problems as part of the decision making process. Since decisions are usually made from our personal research and experiences, Mauboussin argues the end judgment is usually biased too optimistically. Mauboussin encourages decision makers to access a larger outside reference class of diverse opinions and historical situations. Often, situations and problems encountered by an individual have happened many times before and there is a “database of humanity” that can be tapped for improved decision making purposes. By taking the “outside view,” he believes individual judgments will be tempered and a more realistic perspective can be achieved.
In his interview with Morningstar, Mauboussin provides a few historical examples in making his point. He uses a conversation with a Wall Street analyst regarding Amazon (AMZN) to illustrate. This particular analyst said he was forecasting Amazon’s revenue growth to average 25% annually for the next ten years. Mauboussin chose to penetrate the “database of humanity” and ask the analyst how many companies in history have been able to sustainably grow at these growth rates? The answer… zero or only one company in history has been able to achieve a level of growth for that long, meaning the analyst’s projection is likely too optimistic.
Mean reversion is another concept Mauboussin addresses in his book. I consider mean reversion to be one of the most powerful principles in finance. This is the idea that upward or downward moving trends tend to revert back to an average or normal level over time. In describing this occurrence he directs attention to the currently, overly pessimistic sentiment in the equity markets (see also Pessimism Porn article). At end of 1999 people were wildly optimistic about the previous decade due to the significantly above trend-line returns earned. Mean reversion kicked in and the subsequent ten years generated significantly below-average returns. Fast forward to today and now the pendulum has swung to the other end. Investors are presently overly pessimistic regarding equity market prospects after experiencing a decade of below trend-line returns (simply look at the massive divergence in flows into bonds over stocks). Mauboussin, and I concur, come to the conclusion that equity markets are likely positioned to perform much better over the next decade relative to the last, thanks in large part to mean reversion.
Behavioral finance acknowledges one sleek, unique formula cannot create a solution for every problem. Investing includes a range of social, cognitive and emotional factors that can contribute to suboptimal decisions. Taking an “outside view” and becoming more aware of these psychological pitfalls may mitigate errors and improve decisions.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds and AMZN, but at time of publishing had no direct positions in LM, or MORN. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
The Invisible Giant
Bruce Berkowitz has not exactly been a household name (he apparently is not even Wikipedia-worthy). With his boyish looks, nasally voice, and slicked-back hair, one might mistake Berkowitz for a graduate student. However, his results are more than academic, which explains why this invisible giant was recently named the equity fund manager of the decade by Morningstar. It’s difficult to argue with long-term results, especially in the roller coaster market like we’ve experienced over the last ten years. The Fairholme Fund (FAIRX) fund earned a 13% annualized return over the ten-year period ending in 2009, beating the S&P 500 index by an impressive 14%.
 Click here to view Bloomberg invterview with Bruce Berkowitz
How He Did It
Berkowitz states the stellar performance was achieved by
“Ignoring the crowd and going towards stressed areas that many people are running from…We make our judgments based on the cash that securities generate.”
Fairholme is effectively a “go anywhere” fund that adheres tightly to the value-based philosophy. Berkowitz’s portfolio is centered on equity securities, but his team has also shown willingness to go up and down the capital structure, if they find value elsewhere.
The Fund and its History
Berkowitz started the fund in 1999 as an extension of his separate account business, which was created in his previous life at Smith Barney and Lehman Brothers. The Fairholme fund tends to concentrate around 15 to 25 securities on average, with some holdings accounting for more than 10% of the portfolio. An example of Fairholmes concentration is evidenced by its favorably timed trade in the energy sector, which resulted in a 35% weighting in the fund. Fortunately Berkowitz redeployed that winning position – before energy prices cratered in 2008 – into unloved areas like healthcare and defense stocks.
Berkowitz models his investment style after Warren Buffett, focused on good businesses with prolific cash flows. Like many value investors, Berkowitz fishes for contrarian based ideas residing in pockets of the market that are out of favor. He also likes to have a significant weighting in “special situations,” which are limited to about 25% of the portfolio. In order to take advantage opportunities, Berkowitz is not shy or bashful about carrying around a good chunk of cash in his pocket. He likes to keep about 15% on average to scoop up out of favor opportunities.
The Future of Fairholme
I commend Berkowitz for his admirable record, but I caution investors to not go hog wild over outperforming funds. He has crushed the market over an extremely challenging investment period, but investors need to remember that “mean reversion,” the tendency for a trend to move towards averages, applies to investing styles too. Concentrated, go-anywhere, large cap value, market timing funds that outperform for ten years at a time may underperform or outperform less dramatically over the next ten years. Just ask Bill Miller (see also Bill Miller Revenge of the Dunce article), concentrated value manager at Legg Mason, about mean reversion. Miller beat the market for 15 consecutive years before recently ending up in the bottom 10-year decile (1-star Morningstar rated) after some bad concentrated bets and poor investment timing. Another challenge for Fairholme is size (currently around $10.5 billion in assets under management). Having managed a multi-billion fund myself (see also my book), I can attest to the complexities Berkowitz faces in managing a much larger fund now.
Regardless, Berkowitz’s performance should not be ignored given his sound philosophy and achievement over an unprecedented period. Already, just a few weeks into 2010, Fairholme is ranked #1 in its fund category by Morningstar.
This is one invisible man you should not let disappear off your radar.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at time of publishing had no direct positions in FAIRX, LM, BRKA/B or MORN. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Technical Analysis – Astrology or Lob Wedge?

Investing comes in many shapes and sizes. And like religion (see Investing Religion article), most investment strategies are built on the essential belief that following certain rules and conventions will eventually lead to profit enlightenment. When it comes to technical analysis (TA), a discipline used with the principal aim of predicting future prices from past patterns, some consider it a necessity for making money in the market. Others, regard the practice of TA as a pseudoscience, much like astrology.
I feel there is a proper place for TA on selective basis, which I will describe later, but for the most part I agree with some of the legendary investors who have chimed in on the subject:
Warren Buffett: “I realized technical analysis didn’t work when I turned the charts upside down and didn’t get a different answer.”
Peter Lynch: “Charts are great for predicting the past.”
Technical Analysis Linguistics
Fundamental analysis, the antithesis of technical analysis, strives to predict future price direction by analyzing facts and data surrounding a company, industry, and/or economy. It too comes with its own syntax and versions, for example: value, growth, top-down, bottom-up, quantitative, etc.
I do not claim to be a TA expert, however in my many years of investing I have come across a smorgasbord of terms and flavors surrounding the discipline. Describing and explaining the density of material surrounding TA would encompass too large of a scope for this article, but here are some prevalent terms one should come to grips with if you want to become a technical analysis guru:
Technical analysis Approaches
- Elliot Wave
- Relative strength / Momentum (see Momentum Investing article)
- MACD (Moving Average Convergence / Divergence)
- Fibonacci retracement
- Dow Theory
- Stochastics
- Bollinger bands
Price Patterns
- Head and shoulders
- Double bottom
- Cup and handle
- Channels
- Breakouts
- Pivot points
- Candlesticks
- Resistance/Support
- Dead cat bounce (my personal favorite)
Each of these patterns are supposes to provide insight into the future direction of price. At best, I would say the academic research surrounding the subject is “inconclusive,” and at worst I’d say it’s considered a complete “sham.”
The Lob Wedge

As I’ve stated earlier, I fall in the skeptical camp when it comes to TA, since fundamental analysis is the main engine I use for generating and tracking my investment ideas. For illustrative purposes, you may consider fundamental analysis as my group of drivers and irons. I do, however, utilize selective facets of TA much like I use a lob wedge in golf for a limited number of specific situations (e.g., shots over high trees, downhill lies, and fast greens). When it comes to trading, I do believe there is some value in tracking the relationship of extreme trading volume (high or low), especially when it is coupled with extreme price movement (high or low). The economic laws of supply and demand hold true for stock trades just as they do for guns and butter, and sharp moves in these components can provide insights into the psychological mindset of investors with respect to a security (or broader market). Beyond trading volume, there are a few other indicators that I utilize as part of my trading strategies, but these tactics play a relatively minor role, since most of my core positions are held on a multi-year time horizon.
Overall, there is a stream of wasteful noise, volatility, and misinformation that permeates the financial markets on a daily basis. A major problem with technical analysis is the many false triggered signals, which in many cases lead to excessive trading, transaction costs, and ultimately subpar investment returns. Although I remain a skeptic on the subject of technical analysis and I may not read my horoscope today, I will continue to keep a lob wedge in my golf bag with the hopes of finding new, creative ways of using it to my advantage.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own exchange traded funds and various securities, but at time of publishing had no direct position in BRKA/B or any company mentioned in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Google vs. China: Running Away from 660 Million Eyeballs?

Wait, let me get this straight. Google, the $185 billion behemoth that wants to take over the world is seriously considering turning its back on a rapidly growing cluster of 660 million eyeballs (330 million Chinese internet users according to BusinessWeek)? After hitting their head on an obscenely high market share in the U.S. (67% search share based on Nielsen data) and looking for new geographies to expand, I’m supposed to believe Google will walk away from the third largest economy on this planet (see China: Trade of the Century)? The explanation given for Google’s capitulation is discontent related to unknown hackers and censorship concerns. If that’s not enough, this alleged saint-like posturing comes after Google sold its censorship soul for years, before seeing the free speech light. Although the company’s mission is to “do no evil,” Google had no qualms aggressively poaching Microsoft (MSFT) miracle maker, Kai-Fu Lee, to kick-start their Chinese presence. If free speech is truly at the root of the Google’s unease, then why wait four whole years and a hack-attack before laying down an ultimatum on the Chinese government?
I Smell a Rat
In a blog post written by Google’s Chief Legal Officer, David Drummond, the company explains how their iron curtain digital defense was bent but not broken:
“We have evidence to suggest that a primary goal of the attackers was accessing the Gmail accounts of Chinese human rights activists. Based on our investigation to date we believe their attack did not achieve that objective. Only two Gmail accounts appear to have been accessed, and that activity was limited to account information (such as the date the account was created) and subject line, rather than the content of emails themselves.”
I’m no exterminator, but I smell a rat. All this feels a lot more like politics and business tactics then it does an altruistic display of free-speech martyrdom. The Chinese government and Google executives know what is at risk, as they both play a high stakes game of “chicken.”
Google goes onto say:
“As part of our investigation we have discovered that at least twenty other large companies from a wide range of businesses–including the Internet, finance, technology, media and chemical sectors–have been similarly targeted.”
I’m confused. These unknown hackers attacked 20 different companies and only unsuccessfully cracked two Gmail accounts. The evidence sounds pretty harmless on the surface, if this language is representative of reality. Maybe I’m wrong, and a foiled cyber-attack is reason enough to cease operations in a country inhabiting a potential 1.3 billion customers.
Sure China represents a relatively small portion of Google’s revenues (estimated at less than $1 billion and a single digit percentage of revenues), but Google would be insane to walk away from this massive long-term growth market, even if Baidu (BIDU) is currently eating their lunch. Although Google has a smaller #2 position in China, it still has a respectable 35.6% search market share (according to BusinessWeek).
Not Just About Search – Cell Phones Too
Even if they claimed they were throwing in the white towel on their Chinese search business, I don’t think they really want to flush their newly minted cell phone prospects down the toilet. Even if 275 million or so cell phone users in the U.S. is fertile ground for Google to target their new Android-based phones, I’m guessing they have penciled out the gigantic mobile potential of the rapidly expanding 700 million+ Chinese mobile phone user market.
While I can’t take the scenario of Google ceasing China operations off the table, I consider the chance of Google shutting its doors in China significantly less than 50%. While the bold Google statement of feasibility review regarding their Chinese business existence has gained a lot of attention, I think calmer heads will eventually prevail and Google will resume their targeting of 660 million Chinese eyeballs. Who knows, the high stake game of “chicken” may even benefit their bottom-line as they win the hearts and minds of more future free-speech users.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own GOOG shares and China based exchange traded funds at the time of this article’s publishing, but did not have a direct position in MSFT and BIDU shares. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Short-Termism and the Destruction of Wealth
Oscar Wilde, famous Irish playwright, is known for saying “People know the price of everything and the value of nothing.” In a new book titled the Value of Nothing, Raj Patel questions the efficacy of pure capitalism and builds on that idea that many of society’s major economic problems relate to the lack of focus on value. For example, the cost of a $2 greasy burger or $1 candy bar is actually much higher once you factor in the health costs associated with obesity and diabetes – not to mention indirect charges like trash management or environmental costs.
Patel focuses a decent amount on the social damage caused by the consumerism culture for cheap goods. I think this is certainly relevant when you consider our energy policies. Whether you are a “greenie” or not is almost irrelevant from a strategic or security standpoint. Since we import more than 2/3 of our oil from abroad – much of it from countries that wish to do us harm – it seems almost like a no-brainer to have government create incentives to wean us off our addiction to oil (see Thomas Friedman article). Since pure independence will take decades to achieve, I firmly believe we must simultaneously expand our pool of domestic available fossil fuel resources without getting into holy wars over the environment. If there is a shared focus for energy independence and lower-cost, long-term solutions, then surely there can be space for some common ground.
Short-Termism in the Investment World
In the world of investing, instant gratification, short-termism and the “Cramer-ization” of America have served as fuel behind the housing and credit induced binges that have dragged down our economy. I think Jack Gray of Grantham, Mayo, Van Otterloo nailed it when he said, “Excessive short-termism results in permanent destruction of wealth, or at least permanent transfer of wealth.” Decisions made based on the short-term concerns regarding today’s price may have longer lasting impacts, if the consequences of short-termism are not balanced with the probable outcomes discounted into future values. Short-termism merely creates useless churning and transaction costs that make Wall Street intermediaries a fortune, at the cost of investors.
Gray has a great chart from John Bogle data at Vanguard providing a historical perspective on portfolio turnover percentage basis (the inverse being the average investment holding period in years for fund managers):

As you can see from the data chart, the average holding period for equity mutual funds has gone from about 5 years (20% turnover) in the mid 1960s to significantly less than 1 year (> 100% turnover) in recent years. Advancements in technology have lowered the damaging costs of transacting, but the increased frequency, coupled with other costs (impact, spread, emotional, etc.), have been shown to be detrimental over time (Bogle).
Congress would do taxpayers a favor too if they focused on the long-term, rather than piling on debt and building deficits for future generations. If Raj Patel and Jack Gray can get our leaders and investors to strategically think about long-term value, then I know I can sleep more comfortably at night.
Listen to NPR Raj Patel Radio Interview
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (including Vanguard Funds), but at time of publishing had no direct position in any company mentioned in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Cash Pile Still Growing

Despite the sluggish economic reports, corporate cash piles have been expanding (see “Nest Egg” chart), thanks to aggressive cost-cutting, stabilization in GDP numbers, and meager capital programs. As part of stingy CFOs and executives controlling expenses, companies have been slow to hire despite an expected two quarters of economic growth. Job hiring is likely to remain scarce since capacity utilization and capital expenditures will probably remain priorities before job payrolls expand. It may be that jobs were the first area cut as the crisis unfolded and the last aspect to rebound in the economic expansion.
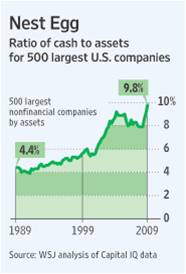
Source: The Wall Street Journal and Capital IQ
As the saying goes, “A bank only lends to those people whom do not need it.” Common knowledge has it that most jobs are created from small and medium sized businesses (SMBs). Unfortunately, the inaccessibility of loans for these SMBs has contributed to the lackluster job recovery. The hemorrhaging of jobs has slowed to a trickle, but sustainable recovery will eventually require new, substantive job creation. Rather than fund what appear to be risky loans to SMBs, banks are choosing to repair their weary balance sheets to reap the benefits of a very steep yield curve (borrowing at low short-term interest rates and lending at relatively high long-term interest rates). Bankers are not the only people stockpiling cash (see other article on cash). On the capital raise side, larger corporations have had more success in tapping the capital credit markets since bond issuance has been flowing nicely.

Source: Haver Analytics and Gluskin Sheff
As multi-national corporations continue to benefit from a relatively weak dollar and Wall Street persists to underestimate the trajectory of the U.S. corporate profit rebound, banks are hoarding more capital, which is leading to a larger cash pile. When will all this cash reflow back into the marketplace? The timing is unclear, but if the profitability and hoarding trends continue, the low-yielding cash piles spoiling on the balance sheets are likely to be released into the economy in the form of capital expenditures and rehiring. Job seekers will breathe a sigh of relief once these corporate wallets become too uncomfortably fat.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (such as VFH), but at time of publishing had no direct position in any company mentioned in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.