Posts filed under ‘Financial Markets’
Walking on Egg Shells

The recent stock market rally has investors walking on egg shells. “Nervous Nelly” investors panicked on the way down last year, and now they are fearful and skeptical about the sustainability of the fierce six-month rally. The S&P 500 is up about 60% from the latest bear market lows, but I think the recent New Jersey Business News (NJBN) article captures the investor sentiment perfectly, “I’m scared, I’m scared, I’m scared,” investor Dania Leon said. “Why are we up, especially with unemployment as high as it is? I don’t feel great because I worry that we could have a 500- or 600-point drop in a day and I won’t be quick enough to pull out of it in time.”
Will investors ever be comfortable? Well yes, of course, exactly at the right time to sell. Calm and complacency will most likely settle in once the economic headlines are on a clear path to recovery. At that point, the market, like a game of chess, will likely have already anticipated the recovery.
Until then, the whipsaw syndrome seems to have taken effect on investors. The NJBN article goes onto expand on investors’ emotional scars:
“They’ve been traumatized twice,” said Michal Strahilevitz, a business professor at Golden Gate University who studies the psychology of individual investors. “First they lost a lot and got out. And now they’ve watched it climb up. It’s a lot of regret, and for people who are investing for their family, it’s a lot of guilt.”
Trillions of low yielding cash continues to sit on the sidelines, waiting for the inevitable 10% “pullback.” Strategist Laszlo Birinyi sees little evidence for an imminent correction, “Give me the evidence…in 1982 we went 424 days before we had a correction. In 2000, we went seven years before we had a 10% correction. In 2002, we went three or four years.” (For more on Mr. Birinyi, see http://is.gd/3xS5u)
At the end of the day, as great growth investor Peter Lynch said, it’s the direction of corporate earnings that will ultimately drive the market higher or lower. “People may bet on hourly wiggles of the market but it’s the earnings that waggle the wiggle long term.” Right now based on the strength of the rally, the market is telling us that third quarter corporate earnings should come in better than analyst expectations. Perhaps we get a yawner response (sell on the news reaction), or if improvement outright stalls, perhaps we will get the mother of all expected corrections?
All these mind games make for an extremely tiresome investing mental tug-of-war. I choose not to get caught up in this game of market timing, but rather I choose to let the investment opportunity-set drive my investment decisions. I have taken some chips off the table during this rebound but I am still finding plenty of other fertile opportunities to redeploy capital. As others nervously walk on egg shells, I opt to clean up the mess and look for a clearer investment path.
Read the Full NJBN Article Here
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Goldman Sachs in Talks to Acquire Treasury Department
 Andy Borowitz from the Borowitz Report published an article a few months ago satirizing the ever increasing conspiracy theories being spread regarding Goldman Sachs’ (GS) role in the global financial crisis. Spearheading the scapegoating Goldman Sachs brigade is Matt Taibbi of Rolling Stone who wrote Inside The Great American Bubble Machine. Megan McArdle at The Atlantic has a detailed critique of Taibbi’s loose facts and outlandish generalizations.
On a lighter note, here’s what Mr. Borowitz has to say about the Goldman Sachs/Treasury Department merger, with tongue firmly in cheek:
According to Goldman spokesperson Jonathan Hestron, the merger between Goldman and the Treasury Department is “a good fit” because “they’re in the business of printing money and so are we.” The Goldman spokesman said that the merger would create efficiencies for both entities: “We already have so many employees and so much money flowing back and forth, this would just streamline things.” Mr. Hestron said the only challenge facing Goldman in completing the merger “is trying to figure out which parts of the Treasury Dept. we don’t already own.” Goldman recently celebrated record earnings by roasting a suckling pig over a bonfire of hundred-dollar bills.
If Matt Taibbi is having difficulty coming up with some fresh new material, perhaps he could target some of these hotly debated areas of contention:
- The 40 year anniversary of NASA faking the moon landing.
- The CIA assassination of John F. Kennedy and the 4th shot from the “grassy knoll.”
- Crashed UFO aircraft remains stored at Area 51, Air Force base in Nevada.
- Elvis still alive.
- Paul McCartney actually dead.
- 9/11 terrorist attacks government cover-up.
- The creation of HIV/AIDS by the CIA.
If Bill Clinton can’t suppress sexual relations with Monica Lewinsky and Dick Cheney can’t hide the fact he shot someone in the face with a shotgun, I guess the Goldman crew is just better at pulling the wool over the eyes of 6.5 billion people…less one smart cookie, Matt Taibbi.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management and client accounts do not have direct positions in GS at the time the article was published. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Wealth Creation Using the Demi-Ashton Ratio

Ajay Kapur at Mirae Asset Securities is bullish on the global markets in the short-run (he sees the S&P 500 index reaching 1250 by March 2010), but even more optimistic in the long-run due to a demographic shift occurring in particular markets. According to this Chief Global Strategist, the more Demi Moores and less Ashton Kutchers we have populating the earth, the better our financial markets will perform.
Mr. Kapur’s Demi-Ashton argument is based on the belief that the higher the ratio of middle aged workers in their 40s (Demis) versus those in their 20s (Ashtons) will result in higher stock prices. Basically, those in their 40s generally have accumulated more wealth to invest and are very concerned about their impending retirement, while those in their 20s have little savings to invest and are more concerned about going to clubs and chasing the opposite sex. Seems to make logical sense.
Even though he is bullish in the domestic markets in the short-run, he sees the U.S., Canada, and Western Europe persisting through a secular bear market that began in 2000 and will last through 2015. Mr. Kapur is quick to point out these markets generally maxed-out when the Demi-Ashton ratios peaked in the 2000 timeframe. When these ratios were rising, for example as in Japan in the 1980s and the U.S. in the 1990s, the respective markets went on an upwards tear. Kapur sees emerging markets like Russia, Eastern Europe, and Latin America benefitting from the rising Demi-Ashton ratios in the coming years.
Whether his hypothesis proves correct or not, I admire the strategist’s bold call on the market direction. Typically economists and strategists herd together due to fear of being an outlier. As for Demi Moore and Ashton Kutcher, they should sleep fine with respect to their retirement plans, as long as they do not go on M.C. Hammer, Michael Jackson, or Mike Tyson spending binges.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Measuring Chaos

An interesting study was done by Morgan Stanley Europe, in which they looked at the last 19 bear markets and subsequent rallies. I’m not sure how much weight you can put on these results since every bear market is unique in its own right, nonetheless it provides a good frame of reference for debates.
What the Morgan Stanley team found was that the median bear market resulted in a -57% decline over 30 months and the ensuing rally equaled about +71% over 17 months. The problem is that our bear market in the U.S. was much shorter than the median timeframe despite its steepness – the fall effectively began in October 2007 and bottomed in March 2009 (about 17 months in duration). Since the decline was faster in duration, does that mean the advance will be as well? Not sure. Our current rally has lasted about six months, which implies there is about another year for the rally to continue based on this data.
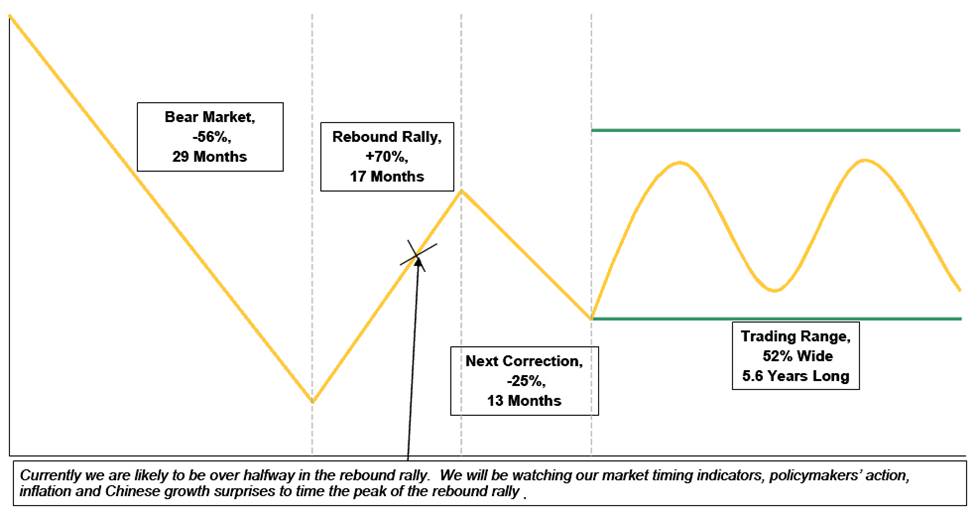
Prieur du Plessis wrote about the Morgan Stanley work for Seeking Alpha
As I alluded to earlier, it’s hard to compare an average to a period in which we had financial institutions dropping like flies (i.e., Bear Stearns, Lehman Brothers, WaMu, Fannie Mae, AIG, etc.) and people were hiding in caves – you knew it was really serious when it even caused voracious consumers to save money…imagine that. At the end of the day, stock and index prices eventually follow earnings. Because of the severity of this downfall, earnings came down faster than prices because fundamentals deteriorated faster than cost cutting could take place. When the economy begins to recover, the opposite will occur – businesses will not be able to hire and spend as fast as earnings are growing. It will be a nice problem to have, but nonetheless characteristic of a typical economic recovery.
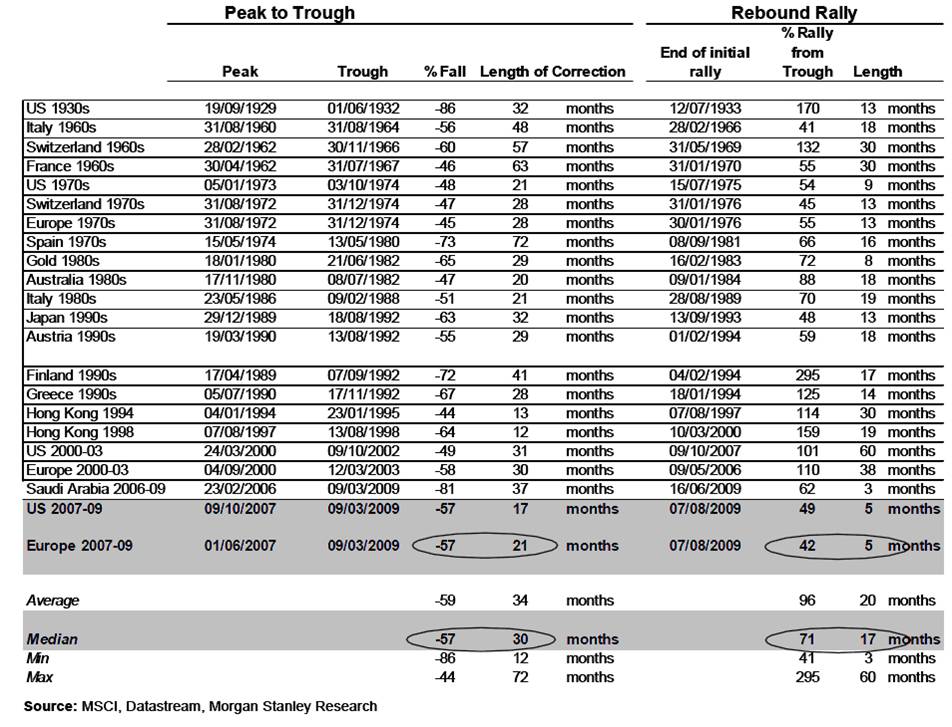
In the U.S., the consumer will have a lot to say about the shape of the recovery since they account for about 2/3 of our country’s economic activity. The other “X” factor will be to what extent government legislation will have an impact on the economy. There will be opportunities available domestically and internally, but in order to survive the chaos, one needs to have a diversified and balanced global approach.
Read the Full Seeking Alpha Article Here
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Business Theory: Voodoo or Value?
Michael E. Porter, a former aeronautical engineer graduate turned Harvard Economics PhD professor, came out with a revolutionary article thirty years ago (How Competitive Forces Shape Strategy) in which he describes the Five Forces of competition that shape the profitability dynamics of an industry. Since then, Porter’s management theories have continued to spread and his knowledge is continually sought after. Some people believe Porter’s Five Forces, and other management business theories, are pure voodoo.
In a recent HBR (Harvard Business Review) article, Andrew O’Connell completed a book review of The Management Myth: Why the “Experts” Keep Getting it Wrong written by Matthew Stewart, a former consultant. Mr. Stewart (a former consultant turned non-believer) exposes the sham of the business consulting industry by outlining the outrageous fees paid by clients and the “mumbo-jumbo” language spouted out by newly minted MBAs.
In a similarly titled article (the Management Myth) written in 2006, Mr. Stewart goes on to say:
“The impression I formed of the M.B.A. experience was that it involved taking two years out of your life and going deeply into debt, all for the sake of learning how to keep a straight face while using phrases like “out-of-the-box thinking,” “win-win situation,” and “core competencies.”… M.B.A.s have taken obfuscatory jargon—otherwise known as bullshit—to a level that would have made even the Scholastics blanch.”
Some other interesting comments include his views on failing companies:
“In fact, we kind of liked failing businesses: there was usually plenty of money to be made in propping them up before they finally went under. After Enron, true enough, Arthur Andersen sank. But what happened to such stalwarts as McKinsey, which generated millions in fees from Enron and supplied it with its CEO?”
Too often with many books, a silver bullet or holy-grail is searched for. The true answer – there is no easy solution. I believe tools or frameworks, like Porter’s Five Forces, can create significant benefits by forcing practitioners into thinking about competition and profits in new ways. Although the lessons may not be worth millions in consulting fees, the education may be worth the $21.95 cost of a book (including free shipping) from Amazon. Mr. Stewart would likely take umbrage with these views, especially since I have an MBA from Cornell.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Social Media Revolution Taking Over World
When I speak of revolution I’m not talking about religion, politics, or wars; rather I am talking about “social media.” Should I care that Ashton Kutcher and Ellen DeGeneres have more twitter followers than the populations of Ireland, Norway, and Panama? Some say social networking is just a fad, but if you blindly sit along the sidelines, the whole world may pass you by in a blink of an eye. Erik Qualman, author of the book and blog Socialnomics, has a must see video that details the revolutionary growth of social media and explains how it is changing the world.
Ever since the early 1900s when the commercialization of radio took hold, millions of people were able to connect all over the world through the spread of technology – in this case the spread of AM (Amplitude Modulation) and FM (Frequency Modulation). Other technologies, such as the telephone, television, and now the internet, have also allowed people to connect. Mr. Qualman details how social media is spreading faster than ever.
Through a chain of details, Qualman highlights the following facts: the invention of the radio took 38 years to reach 50 million users; the television 13 years; the internet 4 years; and the iPod 3 years. Pretty staggering figures until you realize it only took less than 1 year – actually 9 months – for Facebook to add 100 million users! We know the trend is real when my mom (in her seventies) asked me last week how she can register on facebook. Currently, the 55-65 year old female segment is the fastest growing member segment on facebook.
Facebook is just one of many social media networks, which includes twitter, orkut, bebo, flickr, digg, myspace, YouTube, and countless others. The networks are expanding at break-neck speed, and the types of networks are becoming more focused and strange (for example, Spot-a-Potty, or Weird Beard).
Regardless of your view – fad or revolution – the younger generation is consuming more of it. It doesn’t take a genius to follow consumers where they are spending more time. The smart advertisers and businesses are moving to where the action is. As Mr. Qualman notes, Generation Y (the so-called “Echo-Boomers) already outnumbers the Baby Boomers – hmmm, I think advertisers are slowly getting the picture. Investors should be paying attention too. I am investing my own money (and my clients’) in areas like these, where I see companies benefitting from technological change. If pushed to make a choice regarding social media, I pick revolution over fad.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: At the time of publishing, Sidoxia Capital Management and some of its clients owned certain exchange traded funds, AAPL, and GOOG, but had no direct positions in twitter, Facebook, orkut, bebo, flickr, digg, myspace, or any other security referenced. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Technology Does Not Sleep in a Recession
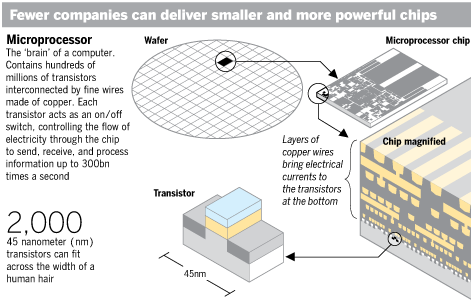
Our economy may be coming out of a long economic hibernation; however technology does not sleep through a recession. Gordon Moore, co-founder of Intel Corporation, has proven this trend true through his groundbreaking piece written in the April 1965 issue of Electronics Magazine. In the article Mr. Moore predicted transistor densities would double about every two years (“Moore’s Law”). Transistors can be thought of as the brains of electronics devices, and the industry (Intel and other semiconductor manufacturers) has been boosting the brain power of electronics for decades. How far has the industry come? The number of transistors contained on a chip has gone from 16 in 1960s to over 600 million today – now that’s what I call progress!
These achievements have been nothing short of revolutionary, and many people consider the introduction of the transistor as the greatest invention of the 20th century. According to many industry experts, Mr. Moore’s forecasts have been shockingly accurate and many believe “Moore’s Law” will hold true for years to come – despite challenging technological limitations.
Source: The Financial Times
We may curse at our computers (I absolutely despise Vista), but there is no arguing with the huge productivity and standard of living improvements we have experienced over the last forty years – since the introduction of the transistor. Many take their GPS, Tivo, WiFi laptop, iPhone, and HiDef TVs for granted, however I for one thank Gordon Moore and those diligent engineers for making my geeky tech dreams come true.
However the cost of further advancements is becoming pricier. As line widths (the ability to add more transistors) narrow, the costs of building fabrication plants (“fabs”) with the necessary equipment are running in the multi-billion range. The Financial Times (FT) article talking about semiconductor trends mentions a $4.2 billion state-of-the-art factory in upstate New York that is just beginning construction. The FT notes that only two players (Intel and Samsung) have firm plans to build 20 nanometer fabs. For comparison purposes, one nanometer is equal to one-billionth of a meter and a human hair is 100,000 nanometers wide. In other words, a nanometer is pretty darn tiny. To further illustrate the point, Intel has managed to fit up to 11 Intel Atom processors – each packed with 47 million transistors – on the face of an American penny.
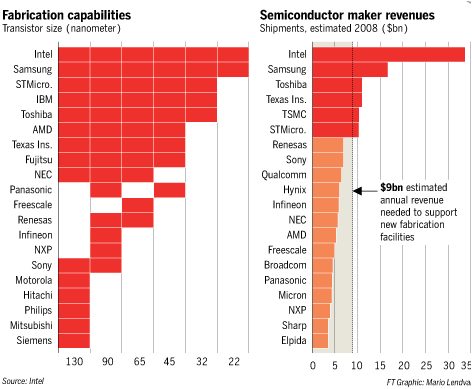
Source: The Financial Times
As the chip making industry become more costly, fewer semiconductor manufacturers will be playing in the sandbox:
“Intel argues that only companies with about $9bn in annual revenues can afford to be in the business of building new fabs, given the costs of building and operating the factories and earning a decent 50 per cent margin. That leaves just Intel, Samsung, Toshiba, Texas Instruments and STMicroelectronics.”
The economy may still be in the doldrums, but the $60 trillion global economy (as measured by Gross Domestic Product) never sleeps – technologies created by Gordon Moore and others continue to propel amazing advancements.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Buffett Sells Insurance: Weapons of ANTI-Destruction
Writing Options is the Opposite of Mass Destruction
Those same “Weapons of Mass Destruction” that Warren Buffett so ardently warned investors against are the same derivatives that catapulted Berkshire Hathaways (BRKA) Q2 earnings performance. Chris McKhann at OptionMonster summarized Buffet’s moves:
Buffett has sold a large number of puts on four major indexes starting in 2007: the S&P 500, the FTSE 100, the Euro Stoxx 50, and the Nikkei 225. He took in $4.9 billion, with a potential loss of more than $35 billion–but only if all four indexes were at zero come the expiration date (at which point we would be worrying about other things).
Derivatives are like a gun, if used responsibly for gaming or for self-defense, then they can be a useful tool. Unfortunately, like guns, these derivatives are used irresponsibly in many instances. This point is especially true in areas like Credit Default Swaps where there were inadequate regulations and capital requirements to prevent disastrous outcomes (e.g., AIG’s collapse). With proper transparency, capital requirements, and proper regulation, derivatives can be used to manage risk rather than create additional risk.
Although I wouldn’t categorize myself as a value investor like Warren, I would prefer to call myself a growth investor with a value conscience. With that said, if you incorporate valuation within your investment discipline, I believe writing (selling) options is a brilliant idea. I can make this assertion because I’ve used this strategy for myself and my hedge fund. Volatility has a direct impact on the amount of premiums collected; therefore the trading levels of the CBOE Volatility Index (VIX) will have a directly correlated impact on option writing profitability. For example, if I’m selling flood insurance, I’m going to collect much higher rates in the period right after Katrina occurred.
If you are willing to accept free money from speculators betting on short-term swings in prices (Warren sold long-term, multi-year options), while being forced to sell/buy stock at price levels you like, then why not?! However, buying and selling puts and calls is a different game in my book, and one I personally do NOT excel at. I’ll keep to utilizing “Weapons of Anti-Destruction” and collect premiums up-front, like Warren, from speculators and leave the rest of the options strategies to others.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management and client accounts do not have direct positions in AIG or BRKA/B at the time the article was published. Sidoxia Capital Management and its clients do have long exposure to TIP shares. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
How Sweet it Is: Sugar Prices Near 30-Year High
The Cap'n Hangin' with the Crunch Berry Beast
The cost of a sugar coma has gone up, making my Cap’n Crunch with Crunch Berries craving a pricier endeavor. It’s seems like almost yesterday when I was crouched over my sugar cereal on a Saturday morning watching cartoons – hey wait, maybe that was last weekend? Regardless of the timeframe, prices for sugar have not been this high since Coke and Pepsi used sugar, rather than corn syrup, in their 1970s formulations and Cuba was the world’s largest sugar producer.
What’s the reason for the +67% price rise in sugar this year*? There are several reasons:
1) Disappointing Crops: India is the largest consumer of sugar at 23.5 million tons and a very significant producer of the sweetener. Due to deficient rainfall in the northeast and southern regions in India (caused in part by El Niño conditions), the country is estimated to need more than double the imports of the good this year. Disappointing crops in Brazil have also contributed to the tightening global supply. India and Brazil account for about 40% of global sugar supplies.
2) Forward Buying / Hedging: The supply-demand dynamics of the sugar market have caused certain high sugar-consuming countries, like Egypt and Mexico, to buy large stockpiling purchases – further pushing up prices. Beyond consumer and speculators, global food and beverage companies from the likes of Kraft, General Mills and ConAgra Foods have been purchasing futures to hedge the risk of additional price hikes.
3) Oil Increase Buoys Ethanol: Oil’s +59% price increase this year to about $70 per barrel has provided additional price support through increased demand for sugar-based ethanol.
Weather, oil demand, and sentiment may change thereby easing the cost burden of higher priced sugar goods, but irrespective of sugar prices you can rest assured my Cap’n Crunch with Crunch Berries addiction will remain resilient.
*Source: The Financial Times (8-7-09).
Read Financial Times Article on Sugar Here
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
“Bye Bye Roubini, Hello Abby”

Perma-Bull with Perma-Grin
Bye-bye” Dr. Doom” and hello “Happy Abby.” Abby Joseph Cohen is back in the spotlight with the recent market resurgence and is calling for a sustained bull market rally. The death-like sentiment spread by NYU professor Nouriel Roubini has now swung – it’s time for CNBC to call in the bulls, much like a baseball coach calls in a fresh reliever after a starter has exhausted his strength.
Over the last year, we’ve gone from full-fledged panic, into a healthy level of fear – the decline in the CBOE Volatility Index (VIX) supports this claim. But with cash still piled to the ceiling and broad indices still are about -35% below 2007 peaks, I wouldn’t say sentiment is wildly ebullient quite yet. The low-hanging fruit has been picked and now we need to tread lightly and delay the victory lap for a little longer. Market timing has never been my gig, so gag me any time I attempt a market prediction. Having said that, sentiment comprises the softer art aspects of investing, and therefore it can swing the markets wildly in the short-run. Ultimately in the long-run, profits and cash flows are what drive stock prices higher, and that’s what I pay attention to. Profits and cash flows are currently depressed and unemployment remains high by historical standards, but there are signs of recovery. Cohen highlights easy profit comparisons in the second half of 2009 (versus 2008), coupled with inventory replenishment, as significant factors that can lead to larger than anticipated surges in early economic cycle recoveries. Whether the pending economic advance is sustainable is a question that Cohen would not address.
Investors are emotional creatures, and CNBC realizes this fact. Before investing in that 30-1 leveraged, long-only hedge fund, prudence should reign supreme as we start to see some of the previously bullish strategists begin crawling out of their caves – including perma-bull Abby Joseph Cohen.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.