Time to Take Out the Trash: From Garbage to Cream
As we saw with the +50% move in the 2003 NASDAQ recovery when there was a flight to garbage (lower quality stocks), eventually the cream rose to the top in the later stages of the 2002-2007 bull market. Usually investors get what they pay for, yet many of the companies that were left for dead in 2008 (including bankruptcy fears) have rebounded the fiercest. As the “anti-Great Depression” trade has paid off handsomely for those low quality stocks, high quality stocks have patiently waited on the sidelines eager to jump along for the escalating ride. Ben Levisohn, Business Week writer, thinks it’s time for high quality stock’s to outperform their junky brethren. Here’s what Mr. Levisohn had to say:
“The stock market has gained 58% since its bear-market low Mar. 9, but the rally hasn’t lifted all equities equally. As is typical in many market bouncebacks, the worst recovered first. Low-quality companies, those with weak or nonexistent profits, mediocre return on equity, and less-than-stellar balance sheets, outpaced their more solidly profitable peers by nearly a 2-to-1 margin, according to research from Baird Private Wealth Management.”
Intuitively, the “garbage” rally makes sense from the standpoint, the harder you fall, the faster you will bounce. However, the sustainability of such rapid, fierce moves should be questioned. Eventually, fundamentals move up investors’ priority list and the “cream” (quality stocks) rises to the top.
Mr. Levisohn further highlights the disparity between “garbage” and “cream” by noting:
“Baird found that companies not earning a profit gained 92% from the Mar. 9 lows through the end of August, compared with a 47% rise for companies that had the highest profit margins. Companies with the lowest return on equity outperformed those with the highest by more than 2 to 1, according to Baird.”
With the sickly stock rally and the removal of the “global meltdown” scenario apparently behind us, I concur with Mr. Levisohn that now is the time to focus on “quality” stocks. What does “quality” mean? From a quantitative perspective, concentrating on those companies with high returns on invested capital (ROIC), high returns on equity (ROE), companies with low levels of debt (leverage), generating healthy levels of cash flow (See Cash Flow Article), represents “quality” investing to me. From a fundamental standpoint, management teams with a clear track record of success, and companies with deep barriers to entry, and a healthy pipeline of growth opportunities are other quality characteristics I look for.
Companies retaining these higher quality traits generally are not held hostage to the capital markets and banking system (i.e., no bailouts necessary). As a result, these companies have the flexibility to invest additional resources into areas like research & development, marketing, manufacturing, and mergers & acquisitions. Superior companies have the ability to step on the throats of weaker competitors, thereby extending their competitive advantage and garnering additional market share.
We have experienced a massive rebound in the markets since the March lows, but now it’s time to take out the garbage. As I search for high quality stocks through my computer terminal, I’ll be enjoying my delicious coffee…with extra cream.
Read Entire Business Week Article Here
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
How to Make Money in Stocks Using Cash Flows
 There you are in front of your computer screen, and lo and behold you notice one of your top 10 positions is down -11% (let’s call it ticker: ABC). With sweaty palms and blood rushing from your head, you manage to click with trembling hands on the ticker symbol that will imminently deliver the dreadful news. A competitor (ticker: XYZ) just pre-announced negative quarterly earnings results, and an investment bank, Silverman Sax, has decided to downgrade ABC on fears of a negative spill-over effect. What do you do now? Sell immediately on the cockroach theory – seeing one piece of bad news may mean there are many more dreadful pieces of information lurking behind the scenes? Or, should you back up the truck to take advantage of a massive buying opportunity?
Thank goodness to our good friend, cash flow, which can help supply answers to these crucial questions. Without an ability to value the shares of stock, any decision to buy or sell will be purely based on gut-based emotions. Many Wall Street analysts follow this lemming based analysis when whipping around their ratings (see The Yuppie Bounce & the Lemming Leap). As I talk about in my book, How I Managed $20,000,000,000.00 by Age 32, I strongly believe successful investing requires a healthy balance between the art and the science. Using instinct to tap into critical experience acknowledges the importance of the artistic aspects of investing. Unfortunately, I know few (actually zero) investors that have successfully invested over the long-run by solely relying on their gut.
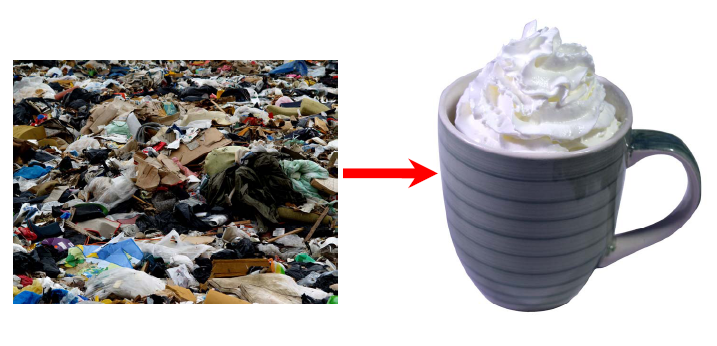
A winning investment strategy, I argue, includes a systematic, disciplined approach with objective quantitative measures to help guide decision making. For me, the science I depend on includes a substantial reliance on cash flow analysis (See Cash Flow Components Here). What I also like to call this tool is my cash register. Any business you look at will have cash coming into the register, and cash going out of it. Based on the capital needs, cash availability, and growth projects, money will furthermore be flowing in and out of the cash register. By studying these cash flow components, we gain a much clearer lens into the vitality of a business and can quickly identify the choke points.
ACCOUNTING GAMES
The other financial statements definitely shed additional light on the fitness of a company as well, but the income statement, in particular, is subject to a lot more potential manipulation. Since the management teams have more discretion in how GAAP (Generally Accepted Accounting Principles) is applied to the income statement, multiple levers can be pulled by the executives to make results look shinier than reality. For example, simply extending the useful life of an asset (e.g., a factory, building, computer, etc.) will have no impact on a company’s cash flow, yet it will instantaneously and magically raise a companies’ earnings out of thin air…voila!
“Stuffing the channel” is another manipulation strategy that can accelerate revenue recognition for a company. For example, let’s assume Company X ships goods to a distributor, Company Y, for the exclusive purpose of recognizing sales. Company X wins because they just increased their sales, Company Y wins because they have more inventory on hand (even if there is no immediate plan for the distributor to pay for that inventory), and the investor gets “hoodwinked” because they are presented artificially inflated sales and income results.
JOINT STRATEGY
These are but just a few examples of why it’s important to use the cash flow statement in conjunction with the income statement to get a truer picture of a company’s valuation and “quality of earnings.” If you don’t believe me, then check out the work done by reputable academics (Konan Chan, Narasimhan Jegadeesh, Louis Chan, and Josef Lakonishok) that show negative differentials between accounting earnings and cash flow are significantly predictive of future stock price performance (Read more).
So the next time a holding craters (or sky-rockets), take an accounting on the state of the company’s cash flows before making any rash decisions to buy or sell. By doing a thorough cash flow analysis, you’ll be well on your way to racking up gains into your cash register.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
The Hidden Train Wreck – Professional Athlete Portfolios
Need capital for a floating furniture venture? How about an oxygen absorbing skin procedure? Well, if you are having any difficulty, just call an NFL, NBA, or MLB rookie. Even wealthy professional athletes have been impacted by the financial crisis, not to mention the aggressive sales tactics of the investment industry and the players’ poor money management skills. Many players are too busy concentrating on winning games, while their portfolios are suffering losses. The statistics are staggering. Here are the findings, according to an article published in Sports Illustrated earlier this year:
- “By the time they have been retired for two years, 78% of former NFL players have gone bankrupt or are under financial stress because of joblessness or divorce.”
- “Within five years of retirement, an estimated 60% of former NBA players are broke.”
- The divorce rate for pro athletes ranges from 60% to 80%, based on estimates from athletes and agents.
- “According to the NFL Players Association, at least 78 players lost a total of more than $42 million between 1999 and 2002 because they trusted money to financial advisers with questionable backgrounds.”
These are not old, dementia-suffering widows living in Florida we are talking about, but rather professional athletes, many of which made multi-million fortunes during their playing careers. The article goes out of its way to demonstrate this is not a fringe issue affecting a minority of professional athletes. Numerous examples were provided, including the following:
- Ten current and former Major League Baseball players, including outfielder Jonny Damon of the New York Yankees, had some of their money tied up in the alleged $8 billion fraud perpetrated by Robert Allen Stanford.
- Raghib (Rocket) Ismail lost a fortune by investing in excessively risky ventures, including a movie about music label COZ Records; a cosmetics procedure company; a nationwide phone-card dispensing venture; and a framed calligraphy company opened in New Orleans two months before Hurricane Katrina hit.
- Drew Bledsoe, Rick Mirer and five other NFL retirees each invested a minimum of $100,000 in a failed start-up, which touted “biometric authentication” technology that potentially could replace credit cards with fingerprints. The players eventually sued UBS (the financial-services firm) for allegedly withholding information about the company founder’s criminal history and drug use.
- Torii Hunter, outfielder for the Los Angeles, invested almost $70,000 in living-room furniture that included inflatable rafts – perfect for those consumers living in flood zones. Suffice it to say, the results did not meet initial expectations.
- In addition to his legal problems, NFL quarterback Michael Vick filed for Chapter 11 bankruptcy last year partly because he could not repay about $6 million in bank loans that he directed toward a car-rental franchise in Indiana, wine shop in Georgia and real estate in Canada.
- Retired NBA forward Vin Baker’s seafood restaurant in Old Saybrook, Connecticut, was foreclosed on in February 2008 due to nearly $900,000 in unpaid loans.
- “NBA guard Kenny Anderson filed for bankruptcy in October 2005. He detailed how the estimated $60 million he earned in the league had dwindled to nothing. He bought eight cars and rang up monthly expenses of $41,000, including outlays for child support, his mother’s mortgage and his own five-bedroom house in Beverly Hills, Calif.—not to mention $10,000 in what he dubbed “hanging-out money.” He also regularly handed out $3,000 to $5,000 to friends and relatives.”
- “Former NBA forward Shawn Kemp (who has at least seven children by six women) and, more recently, Travis Henry (nine by nine) have seen their fortunes sapped by monthly child-support payments in the tens of thousands of dollars.”
Besides irresponsible spending, and greedy advisors, contributing factors to all the losses are the “boring” and “unintelligible” nature of securities investments. Professional athletes like to flaunt investments like night clubs and car dealerships – there is a “thrill of tangibility,” according to SI writer Pablo Torre.
Professional athletes are not the only ones suffering losses. Ordinary investors have lost also and are learning it’s not what you make – rather it’s what you preserve and grow. The majority of the athletes do not realize their peak earnings years cover a very brief period, and therefore need to be more prudent with their money management since the windfall moneys must be spread over many years.
Trust is an important but difficult trait to find for many of these athletes since many opportunistic friends, acquaintances, and family members in many cases put their self interests ahead of the professional athlete’s needs. There is no simple formula for intelligent money management, however there are ways for athletes to protect their financial blind spots:
1) Educate Themselves. Learn the basics of what you are investing in. You may not learn the ins and outs but you can get a basic understanding of the expected return and volatility of your investments. Athletes often forget about diversification as well, “Chronic over-allocation into real estate and bad private equity is the number one problem [for athletes] in terms of a financial meltdown,” Ed Butowsky of Chapwood Investments says.
2) Trust But Verify. Ronald Reagan famously made those statements decades ago and the principle applies to money too. Many athletes pay tens of thousands of dollars for investment advice, so asking questions is advisable. Specifically, ask how performance is trending versus comparable benchmarks and get a view over multiple time periods.
3) Avoid Friends and Family. If possible, separating business from friends and family is a wise idea. When emotions mix with money, harmful decisions can damage the athlete’s financial future.
4) Determine Fees & Commissions. When investing hundreds of thousands, if not millions of dollars, fees and commissions can be substantial; therefore it is imperative for the athletes to know what they are paying their advisors.
5) Experience Matters. Check out the background of your advisor and determine the licenses and credentials they hold. If you were flying a plane in a heavy storm, you would want an experienced pilot flying the plane, not a flight attendant.
6) Budget. Establish an investment plan with a sustainable lifestyle that accounts for inflation. As veteran agent Bill Duffy says, whose clients include Suns guard Steve Nash and Nuggets forward Carmelo Anthony, “A pro athlete’s money is supposed to outlive his career. Most players never get that.”
Athletes spend their whole lives trying to make the professional ranks in order to earn the big bucks. Due to their high profile status, financial advisors and trusted individuals prey on the sports figures’ wealth. Unfortunately a majority of the athletes lack the money management skills and discipline to preserve and grow their earned wealth. Perhaps repeatedly shining a light on the dirty under-belly of this tragic problem will prevent future financial train wrecks from occurring. Until then, I guess we’ll just have to sift though the bankrupt remains of inflatable sofa raft companies and liquidation proceeds from failed night clubs.
Read the Complete Sports Illustrated Article Here
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Walking on Egg Shells

The recent stock market rally has investors walking on egg shells. “Nervous Nelly” investors panicked on the way down last year, and now they are fearful and skeptical about the sustainability of the fierce six-month rally. The S&P 500 is up about 60% from the latest bear market lows, but I think the recent New Jersey Business News (NJBN) article captures the investor sentiment perfectly, “I’m scared, I’m scared, I’m scared,” investor Dania Leon said. “Why are we up, especially with unemployment as high as it is? I don’t feel great because I worry that we could have a 500- or 600-point drop in a day and I won’t be quick enough to pull out of it in time.”
Will investors ever be comfortable? Well yes, of course, exactly at the right time to sell. Calm and complacency will most likely settle in once the economic headlines are on a clear path to recovery. At that point, the market, like a game of chess, will likely have already anticipated the recovery.
Until then, the whipsaw syndrome seems to have taken effect on investors. The NJBN article goes onto expand on investors’ emotional scars:
“They’ve been traumatized twice,” said Michal Strahilevitz, a business professor at Golden Gate University who studies the psychology of individual investors. “First they lost a lot and got out. And now they’ve watched it climb up. It’s a lot of regret, and for people who are investing for their family, it’s a lot of guilt.”
Trillions of low yielding cash continues to sit on the sidelines, waiting for the inevitable 10% “pullback.” Strategist Laszlo Birinyi sees little evidence for an imminent correction, “Give me the evidence…in 1982 we went 424 days before we had a correction. In 2000, we went seven years before we had a 10% correction. In 2002, we went three or four years.” (For more on Mr. Birinyi, see http://is.gd/3xS5u)
At the end of the day, as great growth investor Peter Lynch said, it’s the direction of corporate earnings that will ultimately drive the market higher or lower. “People may bet on hourly wiggles of the market but it’s the earnings that waggle the wiggle long term.” Right now based on the strength of the rally, the market is telling us that third quarter corporate earnings should come in better than analyst expectations. Perhaps we get a yawner response (sell on the news reaction), or if improvement outright stalls, perhaps we will get the mother of all expected corrections?
All these mind games make for an extremely tiresome investing mental tug-of-war. I choose not to get caught up in this game of market timing, but rather I choose to let the investment opportunity-set drive my investment decisions. I have taken some chips off the table during this rebound but I am still finding plenty of other fertile opportunities to redeploy capital. As others nervously walk on egg shells, I opt to clean up the mess and look for a clearer investment path.
Read the Full NJBN Article Here
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Metamorphosis of a Bear into Bull
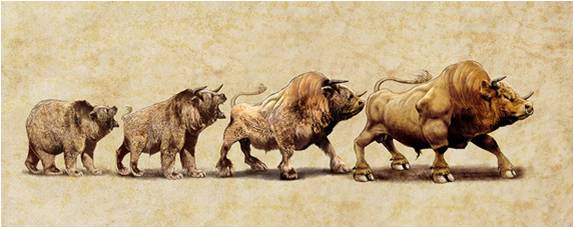
Picture Source: The Wall Street Journal (Mick Coulas)
James Grant, a self-admitted, “glass half-full kind of fellow,” recently contributed a Wall Street Journal article predicting the economic recovery will be a “bit of a barn burner.” Traditionally a pessimist, he recently experienced the metamorphosis from a bear to a bull. James Grant is a multi-book author who has written for the Interest Rate Observer for more than 25 years with thoughtful observations on economics and interest rates. With a value-tilted investment philosophy, Mr. Grant prides himself as a contrarian and anti-CNBC advocate.
Current Environment
Markets have transitioned from sheer panic (what Grant calls the “bomb shelter”) to a manageable utter fear – meaning a lot of investors still have cash stuffed under the mattress in low yielding money market and CD (Certificates of Deposit) accounts. This bed cash will ultimately act as dry powder to ignite the market higher, should earnings and macroeconomic variables continue to improve. Despite the approximate 60% index bounce from the March 2009 lows, the S&P 500 still remains more than 30% below the late 2007 highs.
Glass Half Empty Crowd
Skeptics of the market advance generally fall into one of the following buckets:
1) Armageddon is coming, just wait. Our country is choking on too much debt.
2) The stock market advance is merely a bear market rally within a secular bear market.
3) Rally fueled by temporary stimulus, which once it dries up will lead to another recession and bear market.
4) Earnings results that are coming in better than expected are merely coming from unsustainable cost-cutting.
Grant’s Rose-Colored Glasses
James Grant has a different view of the unfolding recovery in light of historical cycle patterns:
“Growth snapped back following the depressions of 1893-94, 1907-08, 1920-21 and 1929-33. If ugly downturns made for torpid recoveries, as today’s economists suggest, the economic history of this country would have to be rewritten.”
Consistent with Mr. Grant’s views, Michael T. Darda, chief economist of MKM Partners stated “The most important determinant of the strength of an economy recovery is the depth of the downturn that preceded it. There are no exceptions to this rule, including the 1929-1939 period.” Grant goes on to compare the current recession with the 1981-82 variety:
“[During] the first three months of 1982, real GDP shrank at an annual rate of 6.4%, matching the steepest drop of the current recession, which was registered in the first quarter of 2009. Yet the Reagan recovery, starting in the first quarter of 1983, rushed along at quarterly growth rates (expressed as annual rates of change) over the next six quarters of 5.1%, 9.3%, 8.1%, 8.5%, 8.0% and 7.1%. Not until the third quarter of 1984 did real quarterly GDP growth drop below 5%.”
Further support for a stronger than anticipated recovery is provided via data supplied by the Economic Cycle Research Institute:
“The institute’s long leading index of the U.S. economy, along with supporting sub-indices, are making 26-year highs and point to the strongest bounce-back since 1983. A second nonconformist, the previously cited Mr. Darda, notes that the last time a recession ravaged the labor market as badly as this one has, the years were 1957-58 —after which, payrolls climbed by a hefty 4.5% in the first year of an ensuing 24-month expansion.”
Mr. Grant does not promise as large a recovery implied by Mr. Darda, but historical standards point in that direction, especially when you factor in vast pools of cash and cautious prognosticators and economists such as Ben Bernanke, Warren Buffett, and Paul Volcker. These financial “giants” have not deterred Mr. Grant’s metamorphosis from a bear to a bull.
Click Here to Read Full Grant WSJ Article
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and at the time of publishing had no direct positions in BRKA/B. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Tips for Survival and Prosperity in Challenging Economic Times
Survival requires multiple strategies
We have all been impacted in some shape or form by the worst financial crisis experienced in a generation. The question now becomes what did we learn from this mess and how can we better prepare for a more prosperous financial future?
Here are some important tips to follow:
Save and Invest: Before paying others, pay yourself first. You can achieve this goal by saving and investing your money. Given the weak state of our government “safety net” programs, such as Medicare and Social Security, it has become more important than ever to save. Life spans are extending as well, meaning a larger “nest egg” is needed for retirement. If you don’t have the time, discipline, or emotional make-up to manage your own money, then seek out a fee-only advisor* who does not have a conflict of interest in regards to building your wealth.
Tighten Belt: In order to save and invest you need to be in a position where you are creating excess income. Cutting costs is one way to generate additional income. Eating out less, buying used, taking more affordable vacations, conserving energy, purchasing private label goods are a few easy ways to save money that will accumulate over time. If those efforts are still not adequate, one should then contemplate adjusting their living situation (i.e., down-size) or pursue additional income opportunities – either through a pay raise or higher paying job alternatives.
Pay Down Debt: If your credit card company is charging you a 15-20% rate on unpaid credit card balances and gouging you for late-fees and cash advances, then look for other sources of affordable financing. A home equity line of credit or second mortgage may make sense for some, if the fees and lower interest rates make economic sense. Contact a financial planner or tax professional to determine the appropriateness of these debt alternatives. Ultimately, the goal is to reduce debt and create more financial flexibility.
Take Free Money: If your employer offers matching payments to your retirement plan contributions, they are effectively offering you free money. Take it! The government offers you some tax deferral savings through IRA (Individual Retirement Account) contributions, so take advantage of that benefit as well.
Form a 6-Month Emergency Fund: The economy may be in a bottoming-out phase; however we are not out of the woods yet. Unemployment is approaching 10% and many companies and industries continue to struggle. Build a protective financial cushion should you or your family hit a bump in the road.
Invest in Yourself: Investing for retirement is crucial, however investing in yourself is just as, if not more, important than traditional investing. What I’m referring to is job training, education, and health awareness. We live in a globalized economy and in order to compete against those starving for our jobs, we need to improve our skills and education. Lastly, we cannot neglect our health. Finances need to be put in perspective. Our health should be a top priority and a disciplined balance between diet and exercise will not only reduce stress, but it will also improve mental health.
Times have been challenging, but when the going gets rough, the tough go saving. Take control of your financial future rather than letting economic circumstances control you. Financial success however should not come at the expense of your health, so also focus on a balanced program of diet and exercise. There are no free lunches in this world, but following these steps will help lead you on a path to prosperity – even in these challenging economic times.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
*DISCLOSURE: Wade W. Slome, CFA, CFP is President and Founder of Sidoxia Capital Management, LLC (www.Sidoxia.com), a fee-only Registered Investment Advisory firm headquartered in Newport Beach, California.
Action Dan (Poker King) and Professional Investing

"Action Dan" wins millions in poker by skillfully mixing art with science
As I write in my book (How I Managed $20,000,000,000.00 by Age 32), successful investing requires skillful use of both art and science. What I find so fascinating is that the same principles apply to poker playing. Like investing, poker is also a game of skill that rewards a player who adequately understands the mathematical probabilities (science) while still able to appropriately read the behavior of his or her opponents (art). Take for example professional poker player and 1995 WSOP champ Dan Harrington. In 2003 he finished 3rd at the World Series of Poker Main Event (the Super Bowl of poker) out of a pool of 839 players. In 2004, the following year, despite the pool more than tripling to 2,576 participants, Mr. Harrington managed to finish 4th and take home a cool $1.5 million in prize money. Did luck account for this success? I think not. Odds, if left to chance, would be 1 in 25,000 for repeating this feat, according to the Economist.
In the short-run, random volatility and luck can make the average investor look like Warren Buffett, but because of the efficiency of the market, that same average investor will look like a schmuck over the long-run. Legg Mason Funds Management put out an incredible chart that I believe so elegantly captures the incoherent and meaningless, short-term noise that the media attempts to interpret daily. What appears like outperformance in the short-run may merely be the lucky performance of a reckless speculator.

Source: Legg Mason Funds Management
Dan Harrington, and so many other talented professionals know this fact all too well when an inexperienced “donkey” over-bets a clearly inferior hand, only to nail an inside-straight card on the “river” (last card of the round) out of pure luck – thereby knocking out a superior professional player. Over the long-run these out-of-control players end up losing all their money and professionals relish the opportunity of playing against them.
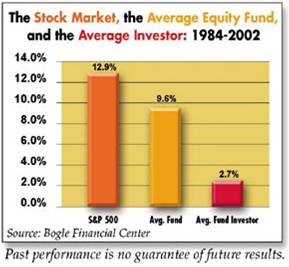
Talk to professionals and ask them what the biggest mistake new players make? The predominate answer: novices simply play too many hands. In the world of investing, the same can be said for excessive trading. Commissions, transactions costs, taxes and most importantly, ill-timed, emotionally driven trades lead the average investor to significantly underperform. I’ve referenced it before, and I’ll reference it again, John Bogle’s 1984-2002 study shows the significant drag the aforementioned costs have on professionals’ performance, and especially the average fund investor that underperformed the passive (a.k.a., “Do Nothing” strategy) S&P 500 return by more than a whopping 10% annually!
I consider myself an above average player, and I’ve won a few small tournaments, but match me up against a professional like “Action Dan” Harrington and I’ll get destroyed in the long-run. Investing, like professional poker, can lead to excess returns with the proper integration of patience and a disciplined systematic approach. I strongly believe that all great long-term investors successfully implement a strategy that marries the art and science aspects of investing. Don’t hold your breath if you expect to see me on ESPN, it may be a while before you see me at the Final Table with Dan Harrington at the World Series of Poker.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and at the time of publishing had no direct positions in LM, DIS, or BRKA/B. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
History Never Repeats Itself, But It Often Rhymes
As Mark Twain said, “History never repeats itself, but it often rhymes.” There are many bear markets with which to compare the current financial crisis we are working through. By studying the past we can understand the repeated mistakes of others (caused by fear and greed), and avoid making similar emotional errors.
Do you want an example? Here you go:
“Today there are thoughtful, experienced, respected economists, bankers, investors and businessmen who can give you well-reasoned, logical, documented arguments why this bear market is different; why this time the economic problems are different; why this time things are going to get worse — and hence, why this is not a good time to invest in common stocks, even though they may appear low.”– Jim Fullerton, former chairman of the Capital Group of the American Funds (written November 7, 1974)
Although the quote above seems appropriate for 2009, it actually is reflective of the bearish mood felt in most bear markets. We have been through wars, assassinations, banking crises, currency crises, terrorist attacks, mad-cow disease, swine flu, and yes, even recessions. And through it all, most have managed to survive in decent shape. Let’s take a deeper look.
1973-1974 Case Study:
For those of you familiar with this period, recall the prevailing circumstances:
- Exiting Vietnam War
- Undergoing a recession
- 9% unemployment
- Arab Oil Embargo
- Watergate: Presidential resignation
- Collapse of the Nifty Fifty stocks
- Rising inflation
Not too rosy a scenario, yet here’s what happened:
S&P 500 Price (12/1974): 69
S&P 500 Price (8/2009): 1,021
That is a whopping +1,380% increase, excluding dividends.
What Investors Should Do:
- Avoid Knee-Jerk Reactions to Media Reports: Whether it’s radio, television, newspapers, or now blogs, the headlines should not emotionally control your investment decisions. Historically, media venues are lousy at identifying changes in price direction. Reporters are excellent at telling you what is happening or what just happened – not what is going to happen.
- Save and Invest: Regardless of the market direction, entitlements like Medicare and social security are under stress, and life expectancies are increasing (despite the sad state of our healthcare system), therefore investing is even more important today than ever.
- Create a Systematic, Disciplined Investment Plan: I recommend a plan that takes advantage of passive, low-cost, tax-efficient investment strategies (e.g. exchange-traded and index funds) across a diversified portfolio. Rather than capitulating in response to market volatility, have a systematic process that can rebalance periodically to take advantage of these circumstances.
For DIY-ers (Do-It-Yourselfers), I suggest opening a low-cost discount brokerage account and research firms like Vanguard Group, iShares, or Select Sector SPDRs. If you choose to outsource to a professional advisor, I recommend interviewing several fee-only* advisers – focusing on experience, investment philosophy, and potential compensation conflicts of interest.
If you believe, like some economists, CEOs, and investors, we have suffered through the worst of the current “Great Recession” and you are sitting on the sidelines, then it might make sense to heed the following advice: “Some people say they want to wait for a clearer view of the future. But when the future is again clear, the present bargains will have vanished.” Dean Witter made those comments 77 years ago – a few weeks before the end of worst bear market in history. The market has bounced quite a bit since March of this year, but if history is on our side, there might be more room to go.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
*For disclosure purposes: Wade W. Slome, CFA, CFP is President & Founder of Sidoxia Capital Management, LLC, a fee-only investment adviser based in Newport Beach, California.
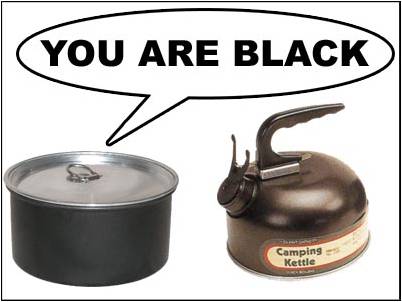
Spitzer the Pot Calling the Fed Kettle Black
Eliot Spitzer, whose job as the former Attorney General of New York was to convict criminals, was forced to quit himself as Governor for his illegal solicitation of prostitutes that he funded with secretive ATM withdrawals of government funds. Now, Mr. Spitzer is getting on his soapbox and telling others the Federal Reserve has been committing a Ponzi Scheme.
There are a lot of conspiracy theories floating around regarding the Fed’s motives and questions relating to the benefits of those receiving government bailout funds. Dylan Ratigan’s interview of Mr. Spitzer on MSNBC feeds into these conspiracy views. I can buy into conflicts of interests and the need for more transparency arguments, but let’s be realistic, this is not the DaVinci Code, this is the slow, bureaucratic Federal Government. Even if you buy into this skeptical belief, the Fed isn’t exactly a “black box.” The Fed proactively provides the minutes from its private meetings and systematically releases a full accounting of the Fed’s balance sheet (assets).
Mr. Spitzer and other critics point to the egregious benefits handed down to the banks and financial institutions through the bailouts and monetary system actions. Well, wasn’t that the idea? I thought our banking system (and the global banking system) was on the verge of collapse and we were trying to save the world from impending disaster? So, I think most people get the fact that our financial institutions needed a lifeline to prevent worse outcomes from occurring.
Should the Fed have carte blanche on all financial system decisions? Certainly not, but extreme situations like this generational financial crisis we are slogging through now, requires extreme measures.
Accountability I believe is even more important than the micro-managing transparency details Ron Paul (Republican/Libertarian Congressman from Texas) and others are asking for. If indeed it is the Fed’s job to remain an independent body, then maybe it’s not Congress’ job to question every word and minor decision. However, when it comes to these massive bailouts (AIG, Fannie Mae, Freddie Mac, etc.), additional details and accountability should be provided and seems fair. What we don’t need are more regulatory bodies and committees creating more inefficiencies in an already tangled system of regulatory fiefdoms.
Before Mr. Spitzer starts pointing his finger at the black Fed-kettle, perhaps he should get his illegal decision making pot in order first?
Read Full Daniel Tencer Spitzer-Ponzi Scheme Article
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Gold Market Lunacy Kicking Into Gear
So wait a second, let me get this right. A company pays billions of dollars to buy insurance, and then decides to sell $3.5 billion in dilutive ownership rights (current stockholders losing more than 10% of their ownership) so that they can pay somebody else another $5.6 billion to take that same insurance they previously loved away. In my book, I call that lunacy. This madness is exactly what Barrick Gold (ABX) just decided to do. The world’s largest gold miner issued approximately 95 million common shares at $37 per share to remove gold price hedges (used to lock in gold prices at a certain level), so if gold prices spike Barrick will now be able to participate fully without the drag of the hedges.
Effectively, management has decided to turn the mining company into a Vegas casino, where shareholders can now freely speculate in the price of gold without the volatility reducing hedges in place. Does this outlandish behavior signal a top in gold prices (now hovering around $1,000 per ounce)? I’m not stupid enough to call the end of frothing, speculative behavior – just witness Alan Greenspan’s “irrational exuberance” speech in 1996 when the NASDAQ traded at 1,300 (then went on to peak above 5,000). But what I am bold enough to do is call a spade a spade and to point out how ridiculous this reverse hedging activity is.
Other signs of speculation beyond the 4x price increase over the last 8 years or so, is the fact that gold prices have risen in the face of incredibly weak gold jewelry demand, -22% year-over-year globally in Q2 according to the Gold Demand Trends. This leaves the remaining demand coming largely from speculators and global central banks. If you need more evidence for the gold speculation, just turn on your local AM radio station and listen for the endless number of get-rich-quick on gold advertisements – some stations need to fill the gaping hole once held by those advertisers hawking mortgages.
From a gold investors’ perspective, I would say I fall more into Warren Buffett camp of thinking. Unlike other commodities (some of which I believe will be driven upwards by my emerging market demand and other forces) , gold is something dug up from the dirt in South Africa, melted, transported to another hole, buried in the ground (central bank), and then storage costs are incurred to guard the shiny metal. Sure, jewelry and small commercial applications are drivers for real demand, but the majority of demand is derived from intangible desires. Other commodities, for example oil, copper, uranium, and natural gas offer a lot more utility.
So what’s next when it comes to the price of gold? Peter Schiff an uber-gold bull broker at Euro Pacific Capital believes Armageddon is coming for the U.S. economy and hyper-inflation will drive gold upwards to the $4,000 per ounce price range (See How Peter Schiff’s Other Forecasts Have Performed). Another possibility to consider is a complete collapse in gold prices (and surge in the dollar) like we saw in the early 1980s after Paul Volcker raised interest rates and gold prices did not appreciate for a 25 year period. Hmmm, I wonder what direction interest rates are going next with the Federal Funds rate currently at effectively 0%? Could we see a repeat of the early ‘80s? Seems like a possibility to me. Certainly if you fall into the civil unrest, soup kitchen, and bread line camp, like Schiff and other U.S. bears, then piling into the diluted Barrick Gold shares may not be a bad strategy.
Inflation
Given the massive stimulus, debt loads, money supply growth and legislative agendas currently in place, inflation is a major medium and long-term concern. My remedy is government guaranteed Treasury Inflated Protection Securities (TIPS) that not only compensates investors with interest payments (unlike gold), but will also see principal values increase in tandem with principal if inflation indeed rears its ugly head. For those conspiracy theorists that believe the Consumer Price Index (CPI) is rigged, there are alternative international flavors of TIPs that reset according to other inflation benchmarks. As a kicker, some of these particular securities offer a hedge against a sliding U.S. dollar, which may or may not continue.
So as I lie in my recliner with my popcorn and TIPs, I’ll watch Barrick and other speculators continue the gold buying frenzy, wondering when and how ugly the gold finale will be?
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management and client accounts do not have direct long or short positions in ABX or gold related securities or BRKA/B at the time the article was published. Sidoxia Capital Management and its clients do have long exposure to TIP shares. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.



 Investing Caffeine