Solving Europe and Your Deadbeat Cousin

The fall holidays are quickly approaching, and almost every family has at least one black-sheep member among the bunch. You know, the unemployed second cousin who shows up for Thanksgiving dinner intoxicated – who then proceeds to pull you aside after a full meal to ask you for some money because of an unlucky trip to Las Vegas. For simplicity purposes, let’s name our deadbeat cousin Joe.
Right now the European union (EU) is dealing with a similar situation, but rather than being forced to deal with money-begging cousin named Joe, the EU is being forced to confront the irresponsible debt-binging practices of its own relatives – the PIIGS (Portugal, Ireland, Italy, Greece, and Spain). The European troika (International Monetary Fund/IMF; European Union/EU; and European Central Bank/ECB), spearheaded by German and French persuasion, is contemplating everything from prescribing direct bank recapitalization, bailouts via the leveraging of the EFSF (European Financial Stability Facility), ECB bond purchases, debt guarantees, unlimited central bank loans, and more.
New stress tests are being reevaluated as we speak. Previous tests failed in gaining the necessary credibility because inadequate haircuts were applied to the values of PIIGS debt held by European banks. European Leaders are beginning to gain some religion as to the urgency and intensity of the financial crisis. Just today, Germany’s chancellor (Angela Merkel) and France’s President (Nicolas Sarkozy) announced that they will introduce a comprehensive package of measures to stabilize the eurozone by the end of this month, right before the summit of the G20 leading global economies in Cannes, France.
Pick Your Poison
Whatever the path used to mop up debt excesses, the options for solving the financial mess can be lumped together in the following categories:
1. Austerity: Plain, unadulterated spending cuts is one prescription being administerd in hopes of curing bloated European sovereign debt issues. Negatives: Slowing economic growth, slowing tax receipts, potentially widening deficits (reference Greece), and political reelection self interests call into question the feasibility of the austerity option. Positives: Austerity is a morally correct fiscal response, which has the potential of placing a country’s financial situation back on a sustainable path.
2. Bailouts: The troika is also talking about infusing the troubled banks with new capital. Negatives: This action could result in more debt placed on country balance sheets, a potentially lower credit rating, higher costs of borrowing, higher tax burden for blameless taxpayers, and often an impossible political path of success. Positives: Financial markets may respond constructively in the short-run, but providing an alcoholic more alcohol doesn’t solve long-term fiscal responsibility, and also introduces the problem of moral hazard.
3. Haircuts: Voluntary or involuntary haircuts to principal debt obligations may occur in conjunction with previously described bailout efforts, depending on the severity of debt levels. Negatives: There are many different sets of constituents and investors, which can make voluntary haircut/debt restructuring terms difficult to agree upon. If the haircuts are too severe, banking reserves across the EU will become decimated, which will only lead to more austerity, bailouts, and potential credit downgrades. Such actions could hamper or eliminated future access to capital, and the cost of access to future capital could be cost prohibitive for the borrowing countries that defaulted/restructured. Positives: Haircuts eliminate or lessen the need for other more painful austerity or restructuring measures, and force borrowers to become more fiscally responsible, not to mention, investors are forced to conduct more thorough due diligence.
4. Printing Press: Buying back debt with freshly printed euros hot off the press is another strategy. Negatives: Inflation is an invisible tax on everyone, including those constituents who are behaving in a fiscally responsible manner. Positives: Not only is this strategy more politically palatable because the inflation tax is spread across the whole union, but this path to debt reduction also does not require as painful and unpopular cuts in spending as experienced in other options.
The Costs
What is the cost for this massive European debt-binging rehabilitation? Estimates vary widely, but a JP Morgan analyst sized it up this way as explained in the The Financial Times:
“In a worst-case, severe recession scenario, €230bn in new capital is needed to meet Basel III requirements, assuming a 60 per cent debt writedown on Greece, 40 per cent on Ireland and Portugal and 20 per cent on Italy and Spain, and that banks withhold dividends.”
More bearish estimates with larger bond loss haircuts, stricter regulatory guidelines, and harsher austerity measures have generated recapitalization numbers north of €1 trillion euros. Regardless of the estimates, European governments, regulators, and central banks are likely to select a combination of the poisons listed above. There is no silver bullet solution, and any of the chosen paths come with their own unique set of consequences.
As time passes and the European crisis matures, I am confident that you will be hearing more about ECB involvement and the firing-up of the printing presses. Perhaps the ECB will fund and work jointly with the EFSF to soak up debt and/or capitalize weak banks. Alternatively, and more simply, the ECB is likely to follow the path of the U.S. and implement significant amounts of quantitative easing (i.e., provide liquidity to the financial system via sovereign debt purchases and guarantees).
Dealing with irresponsible and intoxicated deadbeat second cousins (or European countries) fishing for money is never a pleasurable experience. There are many ways to address the problem, but ignoring the issue will only make the situation worse. Fortunately, our European friends on the other side of the pond appear to be taking notice. As in the U.S., if government officials delay or ignore the immediate problems, the financial market cops (a.k.a., “bond vigilantes”) will force them into action. In the recent past, European officials have used a strategy of sober talking “tough love,” but signs that the ECB printing presses are now beginning to warm up are evident. Once the euros come flying off the presses to detoxify the debt binging banks, perhaps the ECB can print a few extra euros for my cousin Joe.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at the time of publishing SCM had no direct position in JPM, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Playing Whack-A-Mole with the Pros
Source: Flickr
Deciphering the ups and the downs of the financial markets is a lot like playing a game of Whack-A-Mole. First the market is up 300 points, then down 300 points. Next Greece and Europe are going down the drain, and then Germany and the ECB (European Central Bank) are here to save the day. The daily data points are a rapid moving target, and if history continues to serve as a guide (see History Often Rhymes with the Future), the bobbing consensus views of pundits will continue to get hammered by investors’ mallets.
Let’s take a look at recent history to see who has been the “whack-er” and whom has been the “whack-ee.” Whether it was the gloom and doom consensus view in the early 1980s (reference BusinessWeek’s 1979 front page “The Death of Equities”) or the euphoric championing of tech stocks in the 1990s (see Money magazine’s March 2000 cover, “The Hottest Market Ever”), the consensus view was wrong then, and is likely wrong again today.
Here are some of the fresher consensus views that have popped up and then gotten beaten down:
End of QE2 – The Consensus: If you rewind the clock back to June 2011 when the Federal Reserve’s $600 billion QE2 (Quantitative Easing Part II) monetary stimulus program was coming to an end, a majority of pundits expected bond prices to tank in the absence of the Fed’s Ben Bernanke’s checkbook support. Before the end of QE2, Reuters financial service surveyed 64 professionals, and a substantial majority predicted bond prices would tank and interest rates would catapult upwards. Actual Result: The pundits were wrong and rates did not go up, they in fact went down. As a result, bond prices screamed higher – bond values increased significantly as 10-year Treasury yields fell from 3.16% to a low of 1.72% last week.
Debt Ceiling Debate – The Consensus: Just one month later, Democrats and Republicans were playing a game of political “chicken” in the process of raising the debt ceiling to over $16 trillion. Bill Gross, bond guru and CEO of fixed income giant PIMCO, was one of the many pros who earlier this year sold Treasuries in droves because fears of bond vigilantes shredding prices of U.S. Treasury bonds .
Here was the prevalent thought process at the time: Profligate spending by irresponsible bureaucrats in Washington if not curtailed dramatically would cascade into a disaster, which would lead to higher default risk, cancerous inflation, and exploding interest rates ala Greece. Actual Result: Once again, the pundits were proved wrong in the deciphering of their cloudy crystal balls. Interest rates did not rise, they actually fell. As a result, bond prices screamed higher and 10-year Treasury yields dived from 2.74% to the recent low of 1.72%.
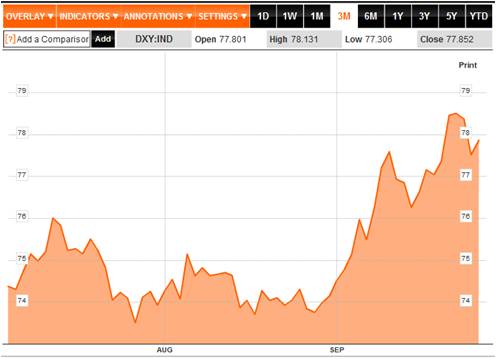
S&P Credit Downgrade – The Consensus: The S&P credit rating agency warned Washington that a failure to come to meaningful consensus on deficit and debt reduction would result in bitter consequences. Despite a $2 trillion error made by S&P, the agency kept its word and downgraded the U.S.’s long-term debt rating to AA+ from AAA. Research from JP Morgan (JPM) cautioned investors of the imminent punishment to be placed on $4 trillion in Treasury collateral, which could lead to a seizing in credit markets. Actual Result: Rather than becoming the ugly stepchild, U.S. Treasuries became a global safe-haven for investors around the world to pile into. Not only did bond prices steadily climb (and yields decline), but the value of our currency as measured by the Dollar Index (DXY) has risen significantly since then.
Dollar Index (DXY) Source: Bloomberg
What is next? Nobody knows for certain. In the meantime, grab some cotton candy, popcorn, and a rubber mallet. There is never a shortage of confident mole-like experts popping up on TV, newspapers, blogs, and radio. So when the deafening noise about the inevitable collapse of Europe and the global economy comes roaring in, make sure you are the one holding the mallet and not the mole getting whacked on the head.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at the time of publishing SCM had no direct position in JPM, MHP, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Mr. Market Bullying Investors
Source: Photobucket
There’s been a bully pushing investor’s around and his name is “Mr. Market.” Volatility is Mr. Market’s partner in crime, and over the last 10 trading days Mr. M has used volatility to school equity investors to the tune of 1,600+ point swings, which has contributed to equity investors’ failing grade over the last few months. Who is Mr. Market? Charles Ellis, author of Winning the Loser’s Game (1998) described him best:
“Mr. Market is a mischievous but captivating fellow who persistently teases investors with gimmicks and tricks such as surprising earnings reports, startling dividend announcements, sudden surges of inflation, inspiring presidential announcements, grim reports of commodities prices, announcements of amazing new technologies, ugly bankruptcies, and even threats of war.”
How has Mr. Market been stealing investors’ lunch money? The process really hasn’t been that difficult for him, once you consider how many times investors have been heaved into the garbage can over the last decade, forced to deal with these messy events:
• 2001 technology bubble beating
• 2006 real estate collapse
• 2008 – 2009 financial crisis and recession
• 2010 “flash crash” and soft patch
• 2011 debt ceiling debate and credit rating downgrade
With this backdrop, investors are dropping like flies due to extreme bully fatigue. Over the last four months alone, approximately $75 billion in equities been liquidated, according to data from the Investment Company Institute – this is even more money withdrawn than the outflows occurring during the peak panic months after the Lehman Brothers collapse.
The Atomic Wedgie

Exhibit I (Source: Photobucket)
Mr. Market understands the severity of these prior economic scars, which have been even more painful than atomic wedgies (reference Exhibit I above), so he opportunistically is taking advantage of fragile nerves. Introducing the following scary scenarios makes collecting lunch money from panicked investors much easier for Mr. Market. What is he using to frighten investors?
- A potential Greek sovereign debt default that will trigger a collapse of the Euro.
- Slowing growth in China due to slowing developed market economic activity.
- Possible double-dip recession in the U.S. coupled with an austerity driven downturn in Europe.
- Lack of political policy response to short and long-term economic problems in Washington and abroad.
- Impending deflation caused by decelerating global growth or likely inflation brought about by central banks’ easy monetary policies (i.e., printing money).
- End of the world.
Bully Victim Protection
Of course, not all of these events are likely to occur. As a matter of fact, there are some positive forming trends, besides just improving valuations, that provide protection to bully victims:
- Not only is the earnings yield (E/P – 12-month trailing EPS/share price) trouncing the yield on the 10-year Treasury note (~8% vs. ~2%, respectively), but the dividend yield on the S&P 500 index is also higher than the 10-year Treasury note yield (source: MarketWatch). Historically, this has been an excellent time to invest in equities with the S&P 500 index up an average of 20% in the ensuing 12 months.
- Jobs data may be poor, but it is improving relative to a few years ago as depicted here:

Source: Calafia Beach Pundit


Source: Calafia Beach Pundit
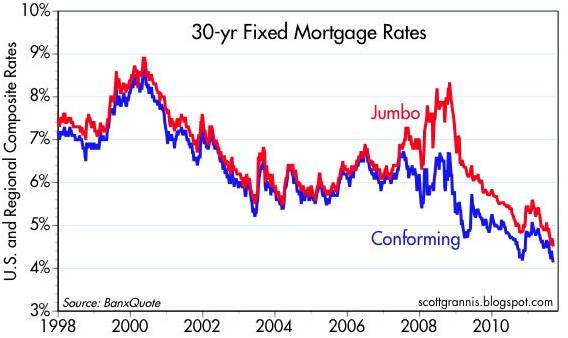
- Record low interest rates and mortgage rates provide a stimulative backdrop for businesses and consumers. Appetite for risk taking remains low, but as history teaches us, the pendulum of fear will eventually swing back towards greed.
Source: Calafia Beach Pundit
As I say in my James Carville peace from earlier this year, It’s the Earnings Stupid, long term prices of stocks follow the path of earnings. Recent equity price market declines have factored in slowing in corporate profits. How severely the European debt crisis, and austerity have (and will) spread to the U.S. and emerging markets will become apparent in the coming weeks as companies give us a fresh look at the profit outlook. So far, we have gotten a mixed bag of data. Alpha Natural Resources (ANR) acknowledged slowing coal demand in Asia and FedEx Corp. (FDX) shave its fiscal year outlook by less than 2% due to international deceleration. Other bellwethers like Oracle Corp. (ORCL) and Nike Inc. (NKE) reported strong growth and outlooks. In the short-run Mr. Market is doing everything in his power to bully investors from their money, and lack of international policy response to mitigate the European financial crisis and contagion will only sap confidence and drag 2011-2012 earnings lower.
Punching Mr. Market
The warmth of negative real returns in cash, bonds, and CDs may feel pleasant and prudent, but for many investors the lasting effects of inflation erosion will inflict more pain than the alternatives. For retirees with adequate savings, these issues are less important and focus on equities should be deemphasized. For the majority of others, long-term investors need to reject the overwhelming sense of fear.
As I frequently remind others, I have no clue about the short-term direction of the market, and Greece could be the domino that causes the end of the world. But what I do know is that history teaches us the probabilities of higher long-term equity returns are only improving. Mr. Market is currently using some pretty effective scare tactics to bully investors. For those investors with a multi-year time horizon, who are willing to punch Mr. Market in the nose, the benefits are significant. The reward of better long-term returns is preferable to an atomic wedgie or a head-flush in the toilet received from Mr. Market.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and FDX, but at the time of publishing SCM had no direct position in ANR, ORCL, NKE, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Magical Growth through Manufacturing Decline

In a data driven world, we can never get enough numbers. The market magicians and the media machines have no problem overhyping or overselling the importance of each pending data-point. With a quick economic sleight of hand, the industry pundits have converted the average investor into a frothing Pavlovian dog, begging for another market shaking statistic. One of the supposed earth-rattling data points is the monthly ISM Manufacturing Index figure, but the release of the ISM number alone isn’t enough for the audience. The real fun comes in determining whether the monthly number registers above or below a schizophrenic 50 level – a number above 50 indicates the manufacturing economy is generally expanding (August came in at 50.6).
The trick can often be surprising, but more surprising to me is the importance placed on this relatively small, disappearing segment of our economy. With the manufacturing sector now accounting for just 11-13% of GDP (see also Manufacturing – Losing Out?), shouldn’t we be focusing more on the “Services” sector of the economy, which accounts for roughly 75% of our country’s output, up from 62% in 1971 (source: Earthtrends). I believe economist Mark Perry at Carpe Diem captured this phenomenon best in his post from earlier this year (Decline of Manufacturing – The World is Much Better Off ):
 The fact of the matter is that manufacturing has been declining as a percentage of GDP over the decades just as the broader economy has seen massive growth. While manufacturing got chopped in half, as a percentage of GDP, from 1970 to 2011 we have seen GDP balloon from about $1 trillion to $15 trillion. If manufacturing declined by another 50% of GDP, I’d do cartwheels to see another 15x increase in economic expansion. I acknowledge the existence of certain synergies between product development and product manufacturing, but these benefits must be weighed against higher domestic costs that could make sales potentially unviable.
Déjà Vu All Over Again
This isn’t the first time in our country’s history that we’ve experienced explosive economic growth as legacy segments of the economy decline in relative importance. Consider the share of jobs agriculture controlled in the early 1800s – a whopping 90% of jobs were tied to farms (see chart below). Today, that percentage is less than 2% in the wake of the U.S. becoming the 20th Century global superpower. History has taught us that technology can be a bitch on employment, as robots, machinery, processes, and chemistry replace the demand for human labor. As Perry points out, there is no doubt that “tractors, electricity, combines, the cotton gin, automatic milking machinery, computers, GPS, hybrid seeds, irrigation systems, herbicides, pesticides” replaced millions of farming jobs, but guess what…American ingenuity ruled the day. As it turns out, those economic resources freed up by technology and productivity were redeployed into new, expanding, job-fertile areas of the economy like, “manufacturing, health care, education, business, retail, computers, transportation, etc.”

Source: Carpe Diem
More Apples or More GMs?
The farming lobby still cries for its inefficient, growth-muffling subsidies today, but many unproductive, unionized domestic manufacturing industries are also screaming for government assistance because cheap foreign labor and new technologies are stealing manufacturing jobs by the boatloads. So at the core, the real question is do we want government and investments supporting more companies like Apple Inc. (AAPL) or more companies like General Motors Company (GM)?
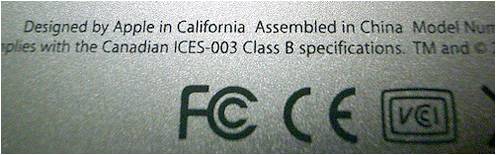
As you may know, by flipping over an iPhone, any observer can clearly notice the product is “designed by Apple in California – assembled in China.” It is clear that Apple and its customers value brains over manufacturing brawn. At $371 billion and the most valuable publicly traded stock in the universe, Apple is dominating the electronics world, all the while hiring employees by the thousands. These facts beg the question of whether Apple should revamp their manufacturing supply-chain back to the U.S. to save more domestic jobs? Of course the result of a manufacturing strategy shift to a higher cost region would make Apple less competitive, force them to charge consumers higher prices for Apple products, and open the door for competitors to freely steal market share? Would this strategy create more incremental jobs, or fewer jobs? I think I’ll side with the Steve Jobs philosophy of business, which says “more profitable businesses must fill more job openings.”
If this Apple case study isn’t illustrative enough for you, maybe you should take a look at companies like GM. The U.S. automobile industry has historically been notoriously mismanaged, thanks to a horrific manufacturing cost structure, anchored by unsustainable pension and healthcare costs. Should investors be surprised that an uncompetitive, bloated cost structure leaves companies like GM less money to invest in new products and innovation? This irrational cost management contributed to decades of market share losses to foreigners. If I’m the job creation czar in the U.S., I think I’ll choose the Apple path to job creation over GM’s route.
Global Competitiveness = Jobs
With a 9.1% unemployment rate and the recent introduction of the American Jobs Act, there has been plenty of emphasis and focus on job creation. At the end of the day, what will create durable, long-term job creation is innovative, competitively priced products and services that can be sold domestically and abroad. How do we achieve this goal? We need an education system that can teach and train a workforce sufficiently to meet the discerning tastes of a global marketplace. Government, on the other hand, needs to support (not direct) the private sector by investing in strategic areas to help global competitiveness (i.e., education, energy independence, basic research, infrastructure, entrepreneurial capital for business formation, etc.), while facilitating a business environment that incentivizes growth.
Regardless of the policy mixtures, the common denominator needs to be focused on improving global competitiveness. Excessive focus on a declining manufacturing sector and the monthly ISM data will only distract decision makers from the core issues. If the economic magician’s sleight of hand diverts investor attention for too long, we may see more jobs disappear.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and AAPL, but at the time of publishing SCM had no direct position in GM, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page
The Political Art of Investment Commentators
There are approximately 2 billion people surfing the internet globally and over 150 million bloggers (source: blogpulse.com) spewing their thoughts out into cyberspace. Throw in economists, strategists, columnists, and the talking heads on television, and you can sleep comfortably knowing there will never be a shortage of opinions for investors to sift through. The real question regarding the infinite number of ideas floating around from the “market commentators” is how useful or harmful is all this information? These diverse points of view, like guns, can be useful or dangerous – depending on an investor’s experience and knowledge level. Deciphering the nuances and variances of investment opinions can be very challenging for an untrained investing eye or ear. While there are plenty of diamonds in the rough to be discovered in the investment advice buffet, there are also a plethora of landmines and booby traps that could explode investment portfolios – especially if these volatile opinions are not handled with care.
No Credentials Required
Unlike dentists, lawyers, accountants, or doctors, becoming a market commentator requires little more than a pulse. All a writer, squawker, or blogger really needs is an internet connection, a keyboard, and something interesting or provocative to talk about. Are any credentials required to blast toxic gibberish to the millions among the masses? Unfortunately there are no qualifications required…scary thought indeed.
In order to successfully navigate the choppy investment opinion waters, investors need to be self-aware enough to answer the following key questions:
• What is your investment time horizon?
• What is your risk tolerance? (see also Sleeping like a Baby)
With these answers in hand, you can now begin to evaluate the credibility and track record of the market commentators and match your personal time horizon and risk profile appropriately. Ideally, investors would seek out prudent long-term counsel, but in this instant gratification society we live in, immediate fear and greed sells advertisements and attracts viewers. Even if media producers and editors of all stripes believed focusing on multi-year time horizons is most beneficial for investors, some serious challenges arise. The brutal reality is that concentrating on the lackluster long-term does not generate a lot of advertisement revenue or traffic. The topics of dollar-cost averaging, asset allocation, diversification, and rebalancing are about as exciting as watching an infomercial marathon (OK, actually this is quite funny) or paint dry. More interesting than the sleepy, uninspiring topics of long-term value creation are stories about terrorist threats, DSK sex scandals, Bernie Madoff Ponzi schemes, currency crises, hacking misconduct, bailouts, tsunamis, earthquakes, hurricanes, 50-day moving averages…OK, you get the idea.
Focus on Long-Term and Do Not Succumb to Short-Termism
Regrettably, there is a massive disconnect between the nano-second time horizons of market commentators and the time horizons of most investors. Moreover, this short-termism dispersed instantaneously via Facebook, Google (GOOG), Twitter, and traditional media channels, has sadly infected the psyches and investment habits of ordinary investors. If you don’t believe me, then check out some of the John Bogle’s work, which shows how dramatically investors underperform the benchmark thanks to emotionally charged reactions (see Fees, Exploitation, and Confusion Hammer Investors).
Although myopic short-termism is not the solution, extending time horizons too long does no good for investors either. As economist John Maynard Keynes astutely noted, “In the long run we are all dead.” But surely bloggers and pundits alike could provide perspectives in multiple year timeframes, rather than in multiple hours. Investors would be served best by turning off the TV, PC, or cell phone, and using the resulting free time to read a good book about the virtues of patient investing from successful long-term investors. Stuffing cash under the mattress, parking it in a 0.5% CD, or panicking into sub-2% Treasuries probably is not going to get the job done for your whole portfolio when inflation, longer life expectancies, and the unsustainable trajectory of entitlements destroy the value of your hard-earned nest egg.
Investment Commentators Look into Politician Mirror
Heading into a heated election year with volatility reaching historic heights in the financial markets, both politicians and investment commentators have garnered a great deal of the media spotlight. With the recent heightened interest in the two fields, some common characteristics between politicians and investment commentators have surfaced. Here are some of the similarities:
- Politicians have a short-term incentives to get re-elected and not get fired, even if there is an inherent conflict with the long-term interest of their constituents; Investment commentators have a short-term incentives to follow the herd and not get fired, even if there is an inherent conflict with the long-term interest of their constituents;
- Many politicians have extreme views that conflict with peers because blandness does not get votes; Many investment commentators have extreme views that conflict with peers because blandness does not get votes;
- Many politicians lack practical experience that could benefit their followers, but the politicians have the gift of charisma to mask their inexperience; Many investment commentators lack practical experience that could benefit their followers, but the commentators have the gift of charisma to mask their inexperience;
Investing has never been so difficult, and also has never been so important, which behooves investors to carefully consider portfolio actions taken based on a very volatile and inconsistent opinions from a group of bloggers, economists, strategists, columnists, and various other media commentators. Investors are bombarded with an avalanche of ever-changing daily data, much of which is irrelevant and should be ignored by long-term investors. As you weigh the precious value of your political votes in the upcoming election season, I urge you to back the candidates that represent your long-term interests. With regard to the financial markets, I also urge you to back the investment commentators that support your long-term interests – the success of your financial future depends on it.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and GOOG, but at the time of publishing SCM had no direct position in Facebook, Twitter, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page
August Shakes, Rattles, and Swirls
 Shake, Rattle, & Swirl: Category 3 hurricane Irene pounded the eastern seaboard with winds reaching 110 miles per hour, knocking out power in an estimated 8 million homes and businesses. Some analysts estimate the damage to be somewhere between $7 billion and $10 billion. If that wasn’t enough, earlier in the same week, a 5.8-magnitude earthquake rippled from its Virginia epicenter up to Maine rattling both buildings and people’s nerves.
 Volatility Spikes in August: Volatility, as measured by the Volatility Index (VIX – a.k.a. “Fear Gauge”), reared its ugly head again in August, reaching a level exceeding 44 (Source: Hays Advisory). This reading has only been experienced nine times in the last 25 years. Historically, on average, these have been excellent buying points for long-term investors.
 Steve Jobs Lets Go of Reins: After being Chief Executive Officer of Apple Inc. (AAPL – formerly Apple Computers) for more than 20 years, Steve Jobs passed the CEO reins over to Tim Cook, who has been with the company for 13 years (including interim CEO). Jobs will remain on board as Chairman of Apple and still provide assistance in a more limited capacity.
 Buffett Puts Dry Powder to Work: Billionaire Warren Buffett is putting his money where his mouth is. Although he is one of a few wealthy individuals griping about too LOW income taxes (NYT OpEd), at least he is using some of his extra bucks to support the country’s financial system. More specifically, Buffet’s Berkshire Hathaway Inc. (BRKA) is investing $5 billion in troubled banking giant Bank of America Corp.’s (BAC) preferred stock (paying a 6% dividend), with warrants to buy additional stock in the future at a mutually prearranged price.
 Google Buys Motorola Mobility: Google Inc. (GOOG) agreed to pay $12.5 billion to buy cellphone maker Motorola Mobility Holdings (MMI) in a move designed to protect the internet giant, and its partners, against patent litigation as it pertains to the Google Android mobile phone operating system. that could shake up the balance of power among among tech rivals. Time will tell whether Motorola’s assets will providing valuable resources for Google’s partners (i.e., HTC, LG Electronics and Samsung Electronics) or whether the acquisition will create competitive conflicts.
 ECB Buys some Bonds:The European Central Bank (ECB), Europe’s equivalent of the U.S. Federal Reserve Bank, began buying up billions of dollars in Spanish and Italian bonds last month. The goal of the bond buying program is to stem any potential contagion effect arising from debt crises occurring in countries like Greece, Portugal, and Ireland.
Quote of the Month
On Volatility:
“Worry gives a small thing a big shadow.”
– Swedish Proverb
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: For those taking this article seriously, please look up “parody” in the dictionary. Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, GOOG, and AAPL, but at the time of publishing SCM had no direct position in BRKA, MMI, HTC,
LG Electronics and Samsung Electronics, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page
A Serious Situation in Jackson Hole
Source: Daily Fill
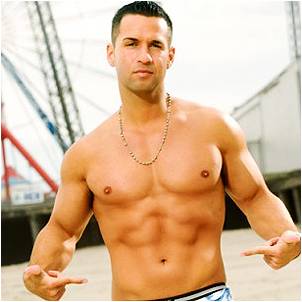
Federal Reserve Chairman Ben Bernanke graced his presence once again upon the glorious skyline of the Grand Tetons in Jackson Hole, Wyoming for the annual Economic Policy Symposium organized by the Federal Reserve Bank of Kansas City. The event has been made famous for Bernanke’s famous 2010 QE2 (quantitative easing) speech and he once again did his best to confuse people this year with his cryptic and masterful “Fed Speak” techniques. While reporters from around the globe covered the event, we at Investing Caffeine were fortunate enough to access MTV’s Jersey Shore cast member’s, Mike “The Situation” Sorrentino, exclusive interpretation of Bernanke’s speech. Here’s how “The Situation” translated Bernanke’s talk:
Mr Bernanke: “The financial crisis and the subsequent slow recovery have caused some to question whether the United States, notwithstanding its long-term record of vigorous economic growth, might not now be facing a prolonged period of stagnation.”
The Situation’s Take: “Looks like this economy is f’d up big time. This is gonna be some sick dry-spell.”
Mr. Bernanke: “The pace of recovery in the United States has, for the most part, proved disappointing thus far… it is clear that the recovery from the crisis has been much less robust than we had hoped.”
The Situation’s Take: “These economist chumps would have more luck chucking darts at Snooki’s booty than they would hitting their predictions. Let’s call Joey, my booky, and I’ll show you how the Situation works his magic.”
Mr. Bernanke: “Manufacturing production in the United States has risen nearly 15 percent since its trough, driven substantially by growth in exports. Indeed, the U.S. trade deficit has been notably lower recently than it was before the crisis, reflecting in part the improved competitiveness of U.S. goods and services.”
The Situation’s Take: “Trashed girls at the clubs like me a lot more after some drinks, just like the trashed value of the dollar makes foreigners like our exports.”
Mr. Bernanke: “Temporary factors, including the effects of the run-up in commodity prices on consumer and business budgets and the effect of the Japanese disaster on global supply chains and production, were part of the reason for the weak performance of the economy in the first half of 2011; accordingly, growth in the second half looks likely to improve as their influence recedes.”
The Situation’s Take: “When I’m chasing tail, hangovers temporarily slow me down sometimes too. What Big Ben and the U.S. financial situation needs is some 5-Hour Energy drink, a tanning session, and a quick pump of the biceps at the gym.”
Mr. Bernanke: “We indicated that economic conditions–including low rates of resource utilization and a subdued outlook for inflation over the medium run–are likely to warrant exceptionally low levels for the federal funds rate at least through mid-2013.”
The Situation’s Take: “I feel you Benjamin. Keeping rates low is like having a permanent 2-for-1 happy hour at the club for the next two years. Now, that’s what I’m talkin’ bout!”
Mr. Bernanke: “The Federal Reserve has a range of tools that could be used to provide additional monetary stimulus. The Committee will continue to assess the economic outlook in light of incoming information and is prepared to employ its tools as appropriate to promote a stronger economic recovery.”
The Situation’s Take: “I hear ya Ben. Sometimes you gotta pull out the secret weapon, just like I have to flash my secret weapon…boom – these monster abs! Keep those secret tools coming Benny. I don’t care if it’s QE3, QE4, QE-infinity – just don’t listen to the haters.”
Mr. Bernanke: “I have confidence that our European colleagues fully appreciate what is at stake in the difficult issues they are now confronting and that, over time, they will take all necessary and appropriate steps to address those issues effectively and comprehensively.”
The Situation’s Take: “Everybody needs to put faith in their wingman sometimes.”
Mr. Bernanke: “Our K-12 educational system, despite considerable strengths, poorly serves a substantial portion of our population.”
The Situation’s Take: “Don’t mess with me Benny. C’mon, just take a look at me. I’m living proof of how our schools are the bomb! After all, the Situation learned his best moves with the ladies during high school.”
Mr. Bernanke: “Most of the economic policies that support robust economic growth in the long run are outside the province of the central bank…As I have emphasized on previous occasions, without significant policy changes, the finances of the federal government will inevitably spiral out of control.”
Situation’s Take: “Don’t let them politician punks make you do all the heavy lifting and flush the economy down the toilet. Looking this good ain’t easy and fixing the U.S. of A. ain’t either.”
Federal Reserve Chairman Ben Bernanke covered a lot of ground in his Jackson Hole speech. Given the mounds of complex data and dismal state of our economic situation, who better to translate and provide cutting edge analysis than Mike “The Situation” Sorrentino. Investing Caffeine appreciates the exclusive access given to us, but now I’m off to more important tasks at hand – before I do my fist pumping at the club tonight, I need to go work my abs and apply a nice spray tan.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: For those taking this article seriously, please look up “parody” in the dictionary. Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at the time of publishing SCM had no direct position in any security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page
WEBINAR: Panic or Attack?! Preserving Your Financial Future (8/26/11)
Webinar Details:
—August 26, 2011 (Friday) at 11:30 a.m. – 12:30 p.m. (Pacific Standard Time)
CLICK HERE TO CONNECT TO WEBINAR
Toll Free # (if not using PC): 1-877-669-3239
Access Code 808 610 841
The financial markets are experiencing historic extremes in volatility. Fears of a European financial contagion are spreading and frustrations with Washington politicians are reaching a feverish pitch. What should investors and retirees do now?
Is now the time to cut losses, or are opportunities of a lifetime developing?
Tune in for this timely review of the financial markets and listen-in to valuable advice on how to preserve your financial future.
CLICK HERE TO CONNECT TO WEBINAR
Toll Free # (if not using PC): 1-877-669-3239
Access Code 808 610 841
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at the time of publishing SCM had no direct position in any security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Shoot First and Ask Later?
The financial markets have been hit by a tsunami on the heels of idiotic debt negotiations, a head-scratching credit downgrade, and slowing economic data after a wallet-emptying spending binge by the government. These chain of events have forced many investors and speculators alike to shoot first, and ask questions later. Is this the right strategy? Well, if you think the world is going to end and we are in a global secular bear market stifled by a choking pile of sovereign debt, then the answer is a resounding “yes.” If however, you believe the blood curdling screams from an angered electorate will eventually influence existing or soon-to-be elected politicians in dealing with the obvious, then the answer is probably “no.”
Plug Your Ears
Anybody that says they confidently know what is really going to happen over the next six months is a moron. You can ask those same so-called talking head experts seen over the airwaves if they predicted the raging +35% upward surge last summer, right after the market tanked -17% on “double-dip” concerns and Fed Chairman Ben Bernanke gave his noted quantitative easing speech in Jackson Hole, Wyoming. I’m still flicking through the channels looking for the professionals who perfectly envisaged the panicked buying of the same downgraded Treasuries Standard and Poor’s pooped on. Oh sure, it makes perfect sense that trillions of dollars would flock to the warmth and coziness of sub-2% yielding debt in a country exploding with unsustainable obligations and deficits, fueled by a Congress that can barely blows its nose to a successful negotiation.
The moral of the story is that nobody knows the future with certainty – no matter how much CNBC producers would like you to believe the opposite is true. Some of the arguably smartest people in the world have single handedly triggered financial market implosions. Consider Robert Merton and Myron Scholes, both renowned Nobel Prize winners, who brought global financial markets to its knees in 1998 when Merton and Scholes’s firm (Long Term Capital Management) lost $500 million in one day and required a $3.6 billion bailout from a consortium of banks. Or ask yourself how well Fed Chairmen Alan Greenspan and Ben Bernanke did in predicting the credit crisis and housing bubble.
If the strategist or trader du jour squawking on the boob-tube was really honest, he or she would steal the sage words of wisdom from the television series secret agent Angus MacGyver who articulated, “Only a fool is sure of anything, a wise man keeps on guessing.”
Listen to the “E”-Word
If you can’t trust all the squawkers, then whom can you trust (besides me of course…cough, cough)? The answer is no different than the person you would look for in other life-important decisions. If you needed a serious heart by-pass surgery, would you get advice from a nurse or medical professor, or would you listen more closely to the top cardiologist at the Mayo Clinic who performed over 2,000 successful surgeries? If you were looking for a pilot to fly your plane, would you prefer a 25-year-old flight attendant, or a 55-year old steely veteran who has 10 million miles of flight experience? OK, I think you get the point…legitimate experience with a track record is key.
Unfortunately, most of the slick, articulate people we see on television may look experienced and have some gray hair, but the only thing they are experienced at is giving opinions. As my great, great grandmother once told me, “Opinions are a dime a dozen, but experience is much more valuable” (embellished for dramatic effect). You are better off listening to experienced professionals like Warren Buffett (listen to his recent Charlie Rose interview), who have lived through dozens of crises and profited from them – Buffett becoming the richest person on the planet doesn’t just come from dumb luck.
If you are having trouble sleeping, you either are taking too much risk, or do not understand the nature of the risk you are taking (see Sleeping like a Baby). Things can always get worse, and the risk of a self-fulfilling further decline is a possibility (read about Soros and Reflexivity). If you are determined to make changes to your portfolio, use a scalpel, and not an axe. The recent extreme volatility makes times like these ideal for reviewing your financial position, goals, and risk tolerance. But before you shoot your portfolio first, and ask questions later, prevent a prison sentence of panic, or your financial situation may end up behind bars.
[tweetmeme source=”WadeSlome” only_single=false https://investingcaffeine.com/2011/08/20/shoot-first-and-ask-later/%5D
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at the time of publishing SCM had no direct position in MHP, CMCSA, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Sleeping like a Baby with Your Investment Dollars

Amidst the recent, historically high volatility in the financial markets, there have been a large percentage of investors who have been sleeping like a baby – a baby that stays up all night crying! For some, the dream-like doubling of equity returns achieved from the first half of 2009 through the first half of 2011 quickly turned into a nightmare over the last few weeks. We live in an inter-connected, globalized world where news travels instantaneously and fear spreads like a damn-bursting flood. Despite the positive returns earned in recent years, the wounds of 2008-2009 (and 2000 to a lesser extent) remain fresh in investors’ minds. Now, the hundred year flood is expected every minute. Every European debt negotiation, S&P downgrade, or word floating from Federal Reserve Chairman Ben Bernanke’s lips, is expected to trigger the next Lehman Brothers-esque event that will topple the global economy like a chain of dominoes.
Volatility Victims
The few hours of trading that followed the release of the Federal Reserve’s August policy statement is living proof of investors’ edginess. After initially falling approximately -400 points in a 30 minute period late in the day, the Dow Jones Industrial Average then climbed over +600 points in the final hour of trading, before experiencing another -400 point drop in the first hour of trading the next day. Many of the day traders and speculators playing with the explosively leveraged exchange traded funds (e.g., TNA, TZA, FAS, FAZ), suffered the consequences related to the panic selling and buying that comes with a VIX (Volatility Index) that climbed about +175% in 17 days. A VIX reading of 44 or higher has only been reached nine times in the last 25 years (source: Don Hays), and is normally associated with significant bounce-backs from these extreme levels of pessimism. Worth noting is the fact that the 2008-2009 period significantly deteriorated more before improving to a more normalized level.
Keys to a Good Night’s Sleep
The nature of the latest debt ceiling negotiations and associated Standard & Poor’s downgrade of the United States hurt investor psyches and did little to boost confidence in an already tepid economic recovery. Investors may have had some difficulty catching some shut-eye during the recent market turmoil, but here are some tips on how to sleep comfortably.
• Panic is Not a Strategy: Panic selling (and buying) is not a sustainable strategy, yet we saw both strategies in full force last week. Emotional decisions are never the right ones, because if they were, investing would be quite easy and everyone would live on their own personal island. Rather than panic-sell, investments should be looked at like goods in a grocery store – successful long-term investors train themselves to understand it is better to buy goods when they are on sale. As famed growth investor Peter Lynch said, “I’m always more depressed by an overpriced market in which many stocks are hitting new highs every day than by a beaten-down market in a recession.”
• Long-Term is Right-Term: Everybody would like to retire at a young age, and once retired, live like royalty. Admirable goals, but both require bookoo bucks. Unless you plan on inheriting a bunch of money, or working until you reach the grave, it behooves investors to pull that money out from under the mattress and invest it wisely. Let’s face it, entitlements are going to be reduced in the future, just as inflation for food, energy, medical, leisure and other critical expenses continue eroding the value of your savings. One reason active traders justify their knee-jerk actions and derogatory description of long-term investors is based on the stagnant performance of U.S. equity markets over the last decade. Nonetheless, the vast number of these speculators fail to recognize a more than tripling in average values in markets like Brazil, India, China, and Russia over similar timeframes. Investing is a global game. If you do not have a disciplined, systematic long-term investment strategy in place, you better pray you don’t lose your job before age 70 and be prepared to eat Mac & Cheese while working as a Wal-Mart (WMT) greeter in your 80s.
• Diversification: Speaking of sleep, the boring topic of diversification often puts investors to sleep, but in periods like these, the power of diversification becomes more evident than ever. Cash, metals, and certain fixed income instruments were among the investments that cushioned the investment blow during the 2008-2009 time period. Maintaining a balanced diversified portfolio across asset classes, styles, size, and geographies is crucial for investment survival. Rebalancing your portfolio periodically will ensure this goal is achieved without taking disproportionate sized risks.
• Tailored Plan Matching Risk Tolerance: An 85 year-old wouldn’t go mountain biking on a tricycle, and a 10 year-old shouldn’t drive a bus to his fifth grade class. Sadly, in volatile times like these, many investors figure out they have an investment portfolio mismatched with their goals and risk tolerance. The average investor loves to take risk in up-markets and shed risk in down-markets (risk in this case defined as equity exposure). Regrettably, this strategy is designed exactly backwards for long-term investors. Historically, actual risk, the probability of permanent losses, is much lower during downturns; however, the perceived risk by average investors is viewed much worse. Indeed, recessions have been the absolute best times to purchase risky assets, given our 11-for-11 successful track record of escaping post World War II downturns. Could this slowdown or downturn last longer than expected and lead to more losses? Absolutely, but if you are planning for 10, 20, or 30 years, in many cases that issue is completely irrelevant – especially if you are still adding funds to your investment portfolio (i.e., dollar-cost averaging). On the flip side, if an investor is retired and entirely dependent upon an investment portfolio for income, then much less attention should be placed on risky assets like equities.
If you are having trouble sleeping, then one of two things is wrong: 1.) You are taking on too much risk and should cut your equity exposure; and/or 2.) You do not understand the risk you are taking. Volatile times like these are great for reevaluating your situation to make sure you are properly positioned to meet your financial goals. Talking heads on TV will tell you this time is different, but the truth is we have been through worse times (see History Never Repeats, but Rhymes), and lived to tell the tale. All this volatility and gloom may create anxiety and cause insomnia, but if you want to quietly sleep through the noise like a content baby, make yourself a long-term financial bed that you can comfortably sleep in during good times and bad. Focusing on the despondent headline of the day, and building a portfolio lacking diversification will only lead to panic selling/buying and results that would keep a baby up all night crying.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (including emerging market ETFs) and WMT, but at the time of publishing SCM had no direct position in TNA, TZA, FAS, FAZ, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.



 Investing Caffeine

