Posts filed under ‘Politics’
Nation’s CEOs Suffering Severely: Pay Down -0.08%

Hold on, let me pull out my violin to play some sympathetic consoling music for our nation’s Chief Executive Officers (CEOs). According to a Corporate Library survey of 2,700 publicly traded companies, CEO compensation declined -0.8% in 2008. I guess that 4th Ferrari and 3rd yacht will have to be put on hold. With some creative perseverance and a little elbow grease, I’m sure the class of underprivileged CEOs can still salvage a healthy package of stock options and restricted stock (to pad the paltry multi-million dollar salaries).
This is what Payscale.com had to say in a report from 2008:
“In 1970, CEO salary and bonus packages were typically about $700,000 – 25 times the average production worker salary; by 2000, CEO salaries had jumped to almost $2.2 million on average, 90 times the average salary of a worker, according to a 2004 study on CEO pay by Kevin J. Murphy and Jan Zabojnik. Toss in stock options and other benefits, and the salary of a CEO is nearly 500 times the average worker salary, the study says.”
Of course, Congress and the public are looking for scapegoats to blame for the global financial crisis. There is no better group to blame than highly compensated CEOs. As a result, we are seeing more “say on pay” proposals brought to shareholder votes, thereby removing power from the hands of self-appointed compensation committees and chummy board members. Currently, a Shareholder Bill of Rights Act is making its rounds through Congress that would establish an annual shareholder vote to approve executive compensation of executive management along with have a separate vote on “golden parachute” payments in the context of a company merger or acquisition.
The U.S. is not the only country to implement these types of shareholder rights. As David Ellis at CNN Money wrote, “In 2002, the United Kingdom embraced the practice, and it has subsequently been taken up in Australia and Sweden.” In the U.S. such proposals being considered are on a “non-binding” basis, which means that if “say on pay” is approved there will be no obligation for management to implement the changes – rather “shame” will be the strategic lever used by shareholders.
Everyone has been impacted in one shape or form by the financial crisis, so when you tuck-in your child or lay your head on the pillow tonight, rest assured our poor corporate CEOs are sharing in the pain…just remember, they only kept 99.2% of their pay last year.
Read More About Corporate Library Survey
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Spitzer the Pot Calling the Fed Kettle Black
Eliot Spitzer, whose job as the former Attorney General of New York was to convict criminals, was forced to quit himself as Governor for his illegal solicitation of prostitutes that he funded with secretive ATM withdrawals of government funds. Now, Mr. Spitzer is getting on his soapbox and telling others the Federal Reserve has been committing a Ponzi Scheme.
There are a lot of conspiracy theories floating around regarding the Fed’s motives and questions relating to the benefits of those receiving government bailout funds. Dylan Ratigan’s interview of Mr. Spitzer on MSNBC feeds into these conspiracy views. I can buy into conflicts of interests and the need for more transparency arguments, but let’s be realistic, this is not the DaVinci Code, this is the slow, bureaucratic Federal Government. Even if you buy into this skeptical belief, the Fed isn’t exactly a “black box.” The Fed proactively provides the minutes from its private meetings and systematically releases a full accounting of the Fed’s balance sheet (assets).
Mr. Spitzer and other critics point to the egregious benefits handed down to the banks and financial institutions through the bailouts and monetary system actions. Well, wasn’t that the idea? I thought our banking system (and the global banking system) was on the verge of collapse and we were trying to save the world from impending disaster? So, I think most people get the fact that our financial institutions needed a lifeline to prevent worse outcomes from occurring.
Should the Fed have carte blanche on all financial system decisions? Certainly not, but extreme situations like this generational financial crisis we are slogging through now, requires extreme measures.
Accountability I believe is even more important than the micro-managing transparency details Ron Paul (Republican/Libertarian Congressman from Texas) and others are asking for. If indeed it is the Fed’s job to remain an independent body, then maybe it’s not Congress’ job to question every word and minor decision. However, when it comes to these massive bailouts (AIG, Fannie Mae, Freddie Mac, etc.), additional details and accountability should be provided and seems fair. What we don’t need are more regulatory bodies and committees creating more inefficiencies in an already tangled system of regulatory fiefdoms.
Before Mr. Spitzer starts pointing his finger at the black Fed-kettle, perhaps he should get his illegal decision making pot in order first?
Read Full Daniel Tencer Spitzer-Ponzi Scheme Article
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Maher Cheerleads No Profit Healthcare
Bill Maher, shock-comedian and host of Real Time with Bill Maher on HBO, has made up a new rule in a recent article, “Not Everything in America Has to Make a Profit.”
Hey Bill, that sounds intriguing. I’ve got an idea – how about you decide to work for no profit? If free healthcare is a right for every American, then why should people pay for your stupid jokes? If I have a right to free healthcare, then why not a right to free laughs?
Don’t get me wrong, our system is broke and needs to be fixed. The real question, is insuring an additional 50 million uninsured, by the same bureaucratic healthcare system leading the Medicare train-wreck, our best approach in solving our healthcare crisis? Sure, doing nothing should not be a fallback, but I’m not sure a trillion dollar healthcare plan with Washington bureaucrats is the best idea either? I’m not against government involvement, but before we dive headfirst into the deep-end with additional deficit exploding plans, why not wade in the shallow end and slowly roll-out success-based models that prove their superiority first.
I’m no medical expert, but let’s take the best structures, whether it’s the Mayo Clinic, Cleveland Clinic, or other leading structures and have the government manage a steady roll-out. If the government can prove a lower-cost, more efficient way of serving higher quality care, then by all means…let’s see it. Some argue we don’t have time to test new models, well unfortunately our disastrous system took decades to create and a pork-filled bill through Congress is not going to be an immediate silver-bullet for our dire healthcare problems.
Getting back to Mr. Maher’s profit objections on healthcare, I wonder if he’s ever complained or contemplated the innovations created by the profit-laden healthcare system. Whether it’s an MRI, hip replacement, cholesterol drug, cancer test, glaucoma treatment, ADHD medication or the hundreds of other beneficial advancements, maybe Mr. Maher should ask and understand where all these innovations came from? The answer: good old profits that were invested in critical research and development. Without those profits, there would be fewer and less impactful healthcare innovation for millions of Americans.
As for the firemen who do not “charge” or make a profit, I would like to remind Mr. Maher who is paying their fair share for those services consumed by hundreds of millions of Americans – it’s those same “soulless vampires making money off human pain” that you castigate. Profitable corporations are funding those essential government services with tax dollars derived from, you guessed it, profits. If we can find a lower-cost, more efficient way of serving the public services by the government, then as Phil Knight from Nike (NKE) says, “Just Do It!” Unfortunately, I prefer to see some tangible proof first, before spending hundreds of billions of tax dollars.
Healthy Incentives
From an early age, even as babies, we are incentivized for certain behavior. Whether it’s offering M&Ms to potty-train a two year old, or submitting six-figure bonuses to a fifty-two year old for hitting department profit targets, incentives always plays a central role in shaping behavior. Figure out the desired behavior and create incentives for your subjects (and penalties for non-compliance).
As the government comes up with a public solution, I have no problem with Washington pressuring insurance companies and the medical industry to become more efficient and provide a higher threshold of care. I’m confident that structures can be put in place that mitigate conflicts of interest (i.e., pure profit motive), while increasing the standard of care and efficiency. Rewarding the healthcare industry with incentives, rather than just simply beating them over the head with lower reimbursements under a single-payer system, may produce longer-lasting, sustainable benefits.
In certain areas of society, such as policemen/women, firefighters, national defense, and doctors there has always been a view that government is better suited for handling certain services. However, sometimes government does not implement the proper incentive plans, which then leads to bureaucracy, inefficiency, and excessive costs. Eventually, these negative trends overwhelm the system into failure, much like sand grinding engine gears to a halt.
Bill, I appreciate your viewpoint, and I like you would love if everything was free. For starters, I’ll look for your press release announcing the cancellation of your multi-million contract with HBO, closely followed by the revelation of your pro-bono comedy work. Here’s to profitless prosperity.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at the time of publishing SCM had no direct position in NKE, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Surviving in a Post-Merger Financial World
The financial institution dominoes have fallen.
Over the last two years we have experienced the worst financial crisis since the Great Depression. As a result, financial institutions have come under assault from all angles, including its customers, suppliers, and regulators. And as we have watched the walls cave in on the banking and brokerage industries, we have seen a tremendous amount of consolidation. Like it or not, we need to adapt to the new environment.
The accelerated change began in early 2008 with the collapse of Bear Stearns and negotiated merger with JP Morgan Chase. Since then we saw the largest investment banking failure (Lehman Brothers), and the largest banking failure in history (Washington Mutual). Other mergers included the marriage of Merrill Lynch and Bank of America, the combination of Wachovia into Wells Fargo, and most recently the blending of Smith Barney into Morgan Stanley. These changes don’t even take into account the disruption caused by the government control of Fannie Mae, Freddie Mac, and AIG.
So what does all this change mean for consumers and investors?
1) Rise in Customer Complaints: Change is not always a good thing. Customer complaints rose 54% in 2008, and climbed 86% in the first three months of 2009 according to FINRA (Financial Industry Regulatory Authority), a nongovernmental regulator of securities companies. The main complaint is “breach of fiduciary duty,” which requires the advisor to act in the best interest of the client. Making the complaint stick can be difficult if the broker only must fulfill a “suitability” standard. To combat the suitability limitation, investors would be well served by investigating an independent Registered Investment Adviser (RIA) who has a fiduciary duty towards clients.
2) Less Competition = Higher Prices: The surviving financial institutions are now in a stronger position with the power to raise prices. Pricing can surface in various forms, including higher brokerage commissions, administrative fees, management fees, ATM fees, late fees, 12b-1 fees and more.
3) Customer Service Weakens: The profit pool has shrunk as lending has slowed and the real estate gravy train has come to a screeching halt. By cutting expenses in non-revenue generating areas, such as customer service, the financial institutions are having a difficult time servicing all their client questions and concerns. There is still fierce competition for lucrative accounts, but if you are lower on the totem pole, don’t expect extravagant service.
4) Increased Regulation: Consumer pain experienced in the financial crisis will likely lead to heightened regulation. For example, the Obama administration is proposing a consumer protection agency, but it may be years before tangible benefits will be felt by consumers. Financial institutions are doing their best to remove themselves from direct oversight by paying back government loans. In the area of financial planning, proposals have been brought to Congress to raise standards and requirements, given the limited licensing requirements. Time will tell, but changes are coming.
Investing in a Post-Merger Financial World: Take control of your financial future by getting answers from your advisor and financial institution. Get a complete list of fees. Find out if they are an independent RIA with a “fiduciary duty” to act in the client’s best interest. Research the background of the advisor through FINRA’s BrokerCheck site (www.finra.org) and the SEC’s Investment Adviser Public Disclosure Web site (www.sec.gov). Get referrals and shop around for the service you deserve. Survival in a post-merger world is difficult, but with the right plan you can be successful.
For disclosure purposes, Sidoxia Capital Management, LLC is an independent Registered Investment Advisor in California.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
California the Golden State Turning Brown
 California is facing a significant cash crunch as the state attempts the narrowing of its $24 billion budget deficit. The crisis will come to a head now that the fiscal year, June 2009, budget deadline has passed. Without a budget resolution and in order to fill the budget gap, the California government will need to start issuing billions of government IOUs to contractors and vendors, local agencies handling health programs, as well as some receiving state aid.
Moodys rates the Golden State as the lowest rated state of all 50 at A2. The average rating for all states is AA2 and only two other states besides California are rated below AA. At the beginning of 2009 the state bought some breathing room by delaying cash tax refunds, but that cushion has rapidly deteriorated as the economy and employment outlook have deteriorated. Making things worse for the state, relative to other states, is the state constitutional inflexibility requiring voter approval for deficit borrowing.
Time will tell if Governor Schwarzenegger can gather the votes necessary to prevent bond defaults. President Obama and other states are watching closely as the actions (or inactions) will have a ripple through effect for everyone. At 13% of the nation’s GDP, California’s economy impacts the overall country in a significant manner.
Let’s hope the state maintains its “golden” status and does not get burnt.
Healthcare Reform: The Brutal Reality of Aging Demographics
The global population is aging and that is a bad trend for healthcare costs.
There’s no question healthcare reform is required. The Economist’s cover story, This is Going to Hurt, addresses this problem head-on:
“Even though one dollar in every six generated by the world’s richest economy is spent on health—almost twice the average for rich countries—infant mortality, life expectancy and survival-rates for heart attacks are all worse than the OECD average. Meanwhile, because health insurance is so expensive, nearly 50m Americans, an obscene number in such a rich place, have none; those that are insured pay through the nose for their cover, and often find it bankruptingly inadequate if they get seriously ill or injured.”
The real question is not whether we have a problem, but rather how are we going to approach it? Estimates of the current healthcare congressional plans put estimates for reform between $1.2 trillion and $1.6 trillion over 10 years. I tend to side with George Will when discussions center on costs, “If you think health care is expensive now, just wait until it is free.”
One of the reasons healthcare costs are exploding is because of our aging demographics. The 76 million “Baby Boomers” are entering their golden years, and as a result are consuming more healthcare products and services. Because our system is so convoluted and opaque, true healthcare competition cannot flourish. Rather, patients expect a cheap “all-you-can-eat” smorgasbord of services without consideration of cost. Unfortunately, the aging trend of our global population (especially in the developed countries like the U.S.) has put our economy on track for a disastrous train-wreck.
The Economist’s article, A Slow Burning Fuse, crystallizes the aging trend into proper perspective by providing some interesting statistics. At the beginning of the last century, in 1900, the average life expectance at birth was approximately 30. Today, the average life expectancy has more than doubled to 67 years (and 78 years in richer developed countries).
Read Full Economist Article, A Slow Burning Fuse
A second major cause of aging societies is the decline in number of children families are having. During the early 1970s, women on average were having 4.3 children each. Now the average is about 2.6 children (and 1.6 children in developed countries). What these statistics mean is that the taxable younger workforce is shrinking (growing slower), therefore unable to adequately feed the swelling appetites of the aging, healthcare-hungry global populations.
My solution would focus on the following:
Technology: Yes, chopping down trees, wasting years of our lives filling out and storing library-esque piles of medical forms is so 20th Century.
Consolidation of Insurers: And do we need dozens of different insurers on different billing platforms? Reducing inefficient and undercapitalized competitors down to a common technological digital record and billing platform makes common sense to me. Although I love competition, if I look at things like cell phones, cable, or even local grocery stores, there is a law of diminishing return whereby inefficiencies eventually outweigh benefits of competition.
Fewer Late Life Benefits: Nearly 30 percent of Medicare spending pays for care in the final year of patients’ lives, according to George Will. Does it really make sense to pay such a high proportion of costs for the last 1-2% of our lives? Other countries, including European ones, deny certain costly services for elderly patients. Does spending over $50,000 on certain cancer treatments for a few extra months of life seem equitable? If elderly ill patients are in the financial position to pay, then that’s great. Otherwise, at some point, the ethical question has to be faced – what is an extra month of human life worth?
Not really a rosy subject, but an important one. I’m confident we can solve these problems, if addressed immediately, or else future generations will be saddled with a more disastrous problem to heal.
Wade W. Slome, CFA, CFP® www.Sidoxia.com
Cap and Tax Passes in the House
The U.S. House of Representatives passed The American Clean Energy and Security Act of 2009 (ACES), also named the “Waxman- Markey” bill, by a 219-212 vote. The masses are calling it the “Cap and Trade” bill, while detractors are blasting it as the “Cap and Tax” bill.
Joe Petrowsky, CEO of Gulf Oil, sees this bill costing businesses $50-100 per ton of carbon created, which will be passed through as a tax to energy consumers in the form of an annual $1,000+ tax (about $250-$350 per individual). Robert Murray, CEO of Murray Energy Corporation, calls it a $2 trillion tax on consumers over 8 years.
The House passed this bill just as the economy is shuttering on its knees and a rising skepticism is brewing over the validity of global warming – see Kimberley Strassel’s, journalist at The Wall Street Journal, article entitled, The Climate Change Climate Change dated June 26, 2009. Australia is in the process of killing its “Cap and Trade” proposals and many critics point to Spain’s failing carbon initiatives and 18% unemployment as evidence for the program’s shortcomings.
Despite one’s views on the validity of global warming, what cannot be disputed is our reliance (addiction) to oil as we import 70% of our oil demand. Is the time and scope of this bill the silver bullet for our crude dependence as we try to survive through this “Great Recession?” I think not.
Billions of humans across the globe are aspiring to achieve our standard of living here in the U.S., so even those against a “Cap and Trade” system, including myself, need to appreciate the massive energy investment we need to make. The U.S. is considered the “Saudi Arabia” of coal due to our vast reserves, and therefore we must find efficient and cleaner ways to use this abundant commodity. We need to throw the kitchen sink at nuclear, wind, solar, hydrogen, bio-fuels and other alternative energy technologies, even as we look to expand our fossil fuel resources.
But rather than forming randomly created silos of hoarded research across hundreds of universities, why not create domestic centers of excellence that collaborate with both academic and private sector participants. By integrating monetary incentives (i.e., exclusive commercial patent rights), incredible advancements and breakthroughs can be achieved. Historically, when the United States has focused on a task, we’ve been able to achieve greatness – for example sending a man to the moon. Heck, recently NASA mastered the art of converting urine into water!
Bold new steps need to be taken to solve our energy crisis, but I’m afraid this “Cap and Tax” bill is not the right answer.
The Governator: Terminate the Deficit or the Pooches?
Picture Source: Clusterstock
The only way you get to save dollars is by saving nickels and dimes, so if saving overpaid bureaucrat wages requires Governor Arnold Schwarzenegger sending pooches to doggy heaven a little early, then so be it. California’s Legislative Analyst’s Office seems to believe $23 million can be saved by accelerating the pet euthanizing process for sheltered pets by three days.
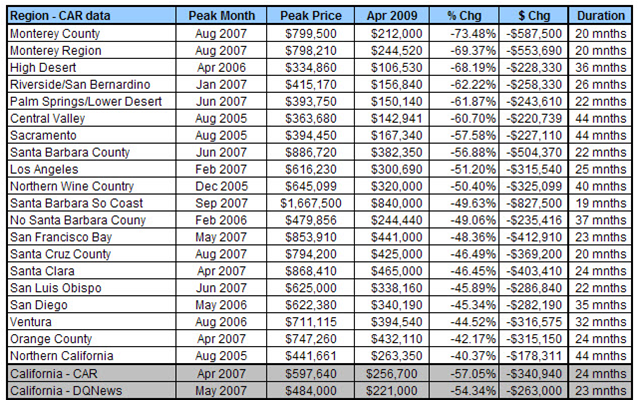
Riding the California housing train was an enjoyable ride in California as home prices more than tripled from the late 1990s until the beginning of 2007. However, after rolling in piles of house tax collection receipts from exploding prices, the bubble based binge of tax revenue has now come to a screeching halt as home prices have declined by more than 50% from peak levels a few years ago (see chart below). Facing an 11.5% unemployment rate, the state is being kicked while it’s down on the ground – income tax collections are declining and businesses dealing with the relatively high cost of operations forcing businesses to run for the hills and leave the state.
Things obviously appear gloomy in California, but the Governator is showing his resolve to get the job done – as evidenced by his contemplation of the pet destruction option. My dog is sleeping inside tonight.
Home Prices Down Dramatically from Peak
Wade W. Slome, CFA, CFP www.Sidoxia.com
U.S. to China, “What’s Wrong With a Little Porn and Anarchy?”
The U.S. recently scheduled talks with the Chinese government to discuss the appropriateness of automated personal computer (PC) content filtering (including, pornography, Falun Gong, and governmental protest content). Falun Gong is a meditatitve spiritual discipline frowned down upon by the Chinese government.
I can picture it now, U.S. officials calling up Chinese President Hu Jintao and saying, “Hey Hu, why not lighten up a bit on the freedom crackdowns – what’s the big deal with a little pornography and anarchy?” The Chinese government feels that in the absence of structured laws, which would limit access to inappropriate content, the natives will become restless and ultimately disruptive. PC manufacturers would prefer not to reengineer PCs and increase the embedded costs to consumers by adding additional components. However, given the size of the Chinese PC market, the dominant foreign manufacturers are likely to cave to Chinese government demands, given the massive long-term potential of this Asian market. We have already seen Google (GOOG), Yahoo (YHOO), and Microsoft (MSFT) make concessions to the Chinese government in the algorithmic search arena.
 The thematic parallels presently occurring in China apply to William Golding’s Lord of the Flies (1954) as well. Lord of the Flies is a story about a group of stranded kids (surviving a plane crash) that battle for survival on a deserted island. Due to the lack of law, adult supervision and questionable tendencies, all hell eventually breaks loose. The Chinese government, managing a population of 1.3 billion people, fears a similarly hellacious outcome if an uncontrolled, lawless population consumes unfettered, unhealthy content. Given mistakes we’ve made abroad (e.g., Abu Ghraib, and Guantanomo), the Chinese and other countries are questioning the strength of our moral compass in judging or guiding other countries’ policies.
Although the U.S. government’s intentions are in the right place to protect the personal freedoms of people globally, we are not currently in the strongest moral position right now to cram our beliefs down other’s throats. Even the freest of societies such as our own limits certain actions – such as underage voting, underage drinking, and public nudity (O.K., I’m stretching a bit).
Regardless of your political views, one can appreciate the fear of anarchy in the hearts of the Chinese government. Practically speaking however, given the openness and rapid expansion of the global internet, the Chinese can only slow the expansion of individuals’ freedoms – recent events in the Middle East just provide additional evidence to this premise.
DISCLOSURE: At the time of publishing, in addition to owning certain exchange traded funds, Sidoxia Capital Management and some of its clients also owned GOOG, but had no direct positions in YHOO, MSFT, or any other security referenced. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Government Looks to Strengthen Regulatory Web

As the chart from the Financial Times shows (BELOW), our messy regulatory cobweb system needs to be straightened out, so it can efficiently function. Not only to encourage risk taking and capitalism, but to also deter and punish those that take advantage of the U.S. system and its citizens. The President and Treasury Secretary Timothy Geithner will address the inefficient, entangled set of regulatory issues surrounding the intertwined agencies in our financial regulatory system. With a mix of federal, regional, and state- driven oversight, the current structure leaves potential gaps for rule-breakers to slide through.

Source: The Financial Times
As the FT article explains (http://is.gd/13YuS), a “council of regulators,” comprised of the agency heads, will be formed along with another consumer-related agency designed to protect areas such as home mortgages and credit cards. Will new unproductive layers be added to merely bog down risk-taking and innovation (i.e., Sarbanes-Oxley legislation), or will substantive reform occur, thereby allowing businesses to innovate and grow. The proof will be in the pudding when Geithner reveals the details of his plan.
What should regulatory reform include?
1) Consolidation: You can call me crazy, but simply looking at the layers of agencies cries for consolidation. Do we really need six different sets of regulators overseeing the banks?
2) Transparency/Capital Requirement Changes: When it comes to derivatives, heightened transparency and capital requirements feel like moves in the right direction. We have perfectly functioning options and futures markets that integrate margin and capital requirements for the various constituencies; I do not see why Credit Default Swaps should be any different. For more customized, exotic over-the-counter products, you could avoid much of the AIG debacle by increasing the capital requirements of the counterparties. I believe these aims without stifling innovation.
3) FDIC of Mega-Institutions: FDIC insurance has succeeded in managing the failures of retail depository institutions, so I see no reason why the same model for mega financial institutions. Certainly, managing the collapse of a global money center bank would be more convoluted; however a system to handle an orderly failure would limit the fallout effect we experienced with the folding of Lehman and crumbling of Bear Stearns.
Although many lawmakers will hunt for a silver bullet, we all know that in this complex global economy a path for reform will involve more evolution rather than revolution. Most controversial will be the consumer protection agency, as details still remain sparse. In my a healthy regulatory system boils down to more simplified structures with tighter oversight, mixed in with proper incentives and harsher punishments for criminals. We’ll know soon enough whether the government can weave a solution tight enough to capture the Bernie Madoffs and Allen Stanfords of the world without sacrificing our position as the global financial capitol of the world.