Posts filed under ‘Politics’
Money Goes Where Treated Best

“The world is going to hell in a handbasket” seems to be a prevailing sentiment among many investors. Looking back, a lack of fiscal leadership in Washington, coupled with historically high unemployment, has only fanned the flames of restlessness. A day can hardly go by without hearing about some fiscal problem occurring somewhere around the globe. Geographies have ranged from Iceland to Dubai, and California to Greece. Regardless, eventually voters force politicians to take notice, as we recently experienced in the Massachusetts vote for Senator.
Time to Panic?
So is now the time to panic? Entitlement obligations such as Social Security and Medicare, when matched with a rising interest payment burden from our ballooning debt, stands to consume the vast majority of our country’s revenues in the coming decades (if changes are not made). It’s clear to most that the current debt trajectory is not sustainable – see also Debt: The New Four-Letter Word. With that said, historical debt levels have actually been at higher levels before. For example, during World War II, debt levels reached 122% of GDP (Gross Domestic Product). Since promises generally garner votes, politicians have traditionally found it easier to legislate new spending into law rather than cutting back existing spending and benefits.
Money Goes Where it’s Treated Best
If our government leaders choose to ignore the growing upswell in fiscal discontent, then the global financial markets will pay more attention and disapprove less diplomatically. As the globe’s reserve currency, the U.S. Dollar stands to collapse if a different direction is not forged, and interest costs could skyrocket to unpalatable levels. Fortunately, the flat world we live on has created some of these naturally occurring governors to forcibly direct sovereign entities to make better decisions…or suffer the consequences. Right now Greece is paying for the financial sins of its past, which includes widening deficits and untenable debt levels.
As new, growing powers such as China, Brazil, India, and other emerging countries fight for precious capital to feed the aspirational goals of their rising middle classes, money will migrate to where it is treated best. Speculative money will flow in and out of various capital markets in the short-run, but ultimately capital flows where it is treated best. Meaning, those countries with policies fostering fiscal conservatism, financial transparency, prudent regulations, pro-growth initiatives, tax incentives, order of law, and other capital-friendly guidelines will enjoy their fair share of the spoils. The New York Times editorial journalist Tom Friedman coined the term “golden straitjacket” in describing this naturally occurring restraint system as a result of globalization.
Push Comes to Shove
Push will eventually come to shove, but the real question is whether we will self-impose fiscal restraint on ourselves, or will the global capital markets shove us in that direction, like the markets are doing to Greece (and other financially strapped nations) today? I am hopeful it will be the former. Why am I optimistic? Although more government spending has typically lead to more votes for politicians, cracks in the support wall have surfaced through the Massachusetts Senatorial vote, and rising populist sentiment, as manifested through the “Tea Party” movement (previously considered a fringe group).
Political gridlock has traditionally been par for the course, but crisis usually leads to action, so I eventually expect change. I am banking on the poisonous and sour mood permeating through the country’s voter base, in conjunction with the collapse of foreign currencies, to act as a catalyst for financial reform. If not, resident capital and domestic jobs will exodus to other countries, where they will be treated best.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (including emerging market-based ETFs), but at time of publishing had no direct positions in securities mentioned in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Short-Termism & Extremism: The Death Knell of our Future

In recent times, American society has been built on a foundation of instant gratification and immediate attacks, whether we are talking about politics or economics. Often, important issues are simply presented as black or white in a way that distorts the truth and rarely reflects reality, which in most cases is actually a shade of grey. President Obama is discovering the challenges of governing a global superpower in the wake of high unemployment, a fragile economy, and extremist rhetoric from both sides of the political aisle. Rather than instituting a promise of change, President Obama has left the natives restless, wondering whether a “change for worse” is actually what should be expected in the future.
Massachusetts voters made a bold and brash statement when they elected Republican Senator Scott Brown to replace the vacated Massachusetts Senate seat of late, iconic Democratic Senator Edward Kennedy – a position he held as a Democrat for almost 47 years. Obama’s response to this Democratic body blow and his fledging healthcare reform was to go on a populist rampage against the banks with a tax and break-up proposal. Undoubtedly, financial reform is needed, but the timing and tone of these misguided proposals unfortunately does not attack the heart of the financial crisis causes – excessive leverage, lack of oversight, and irresponsible real estate loans (see also, Investing Caffeine article on the subject).
With that said, I would not write President Obama’s obituary quite yet. President Reagan was left for dead in 1982 before his policies gained traction and he earned a landslide reelection victory two years later. In order for President Obama to reverse his plummeting approval ratings and garner back some of his election campaign mojo, he needs to lead more from the center. Don’t take my word for it, review Pew Research’s data that shows Independents passing up both Republicans and Democrats. The overall sour mood is largely driven by the economic malaise experienced by all in some fashion, and unfortunately has contributed to short-termism and extremism.
Technology has flattened the world and accelerated the exchange of information globally at the speed of light. Any action, recommendation, or gaffe that deviates from the approved script immediately becomes a permanent fixture on someone’s lifetime resume. Our comments and decisions become instant fodder for the worldly court of opinion, thanks to 24/7 news cycles and millions of passionate opinions blasted immediately through cyberspace and around the globe.
Short-termism and extremism can be just as poisonous in the economic world as in the political world. This dynamic became evident in the global financial crisis. Short-termism is just another phrase for short-term profit focus, so when more and more leverage led to more and more profits and higher asset prices, the financial industry became blinded to the long-term consequences of their short-term decisions.
Solutions:
- Small Bites First: Rather than trying to ram through half-baked, massive proposals laced with endless numbers of wasteful pork barrel projects, why not focus on targeted and surgical legislation first? If education, deficit-reduction, and job creation are areas of common interest for Republicans and Democrats, then start with small legislation in these areas first. More ambitious agendas can be sought out later.
- Embrace Globalization: Based on the “law of large numbers” and the scale of the United States economy, our slice of the global economic pie is inevitably going to shrink over time. How does the $14 trillion U.S economy manage to grow if its share is declining? Simple. By eschewing protectionist policies, and embracing globalization. Developing country populations are joining modern society on a daily basis as they integrate productivity-enhancing innovations used by developed worlds for decades. In a flat world, the narrowing of the productivity gap is only going to accelerate. The question then becomes, does the U.S. want to participate in this accelerating growth of developing markets or sit idly on the sideline watching our competitors eat our lunch?
- Hail Long-Termism and Centrism: Regulations and incentives need to be instituted in such a fashion that irresponsible behavior occurring in the name of instant short-term profits is replaced with rules that induce sustainable profits and competitive advantages over our economic neighbors. Much of the financial industry is scratching and screaming in the face of any regulatory reform suggestions. The bankers’ usual response to reform is to throw out scare tactics about the inevitable damage caused by reform to the global competitiveness of our banking industry. No doubt, the case of “anti-competiveness” is a valid argument and any reforms passed could have immediate negative impacts on short-term profits. Like the bitter taste of many medicines, I can accept regulatory remedies now, if the long-term improvements outweigh the immediate detrimental aspects.
The focus on short-termism and extremism has created an acidic culture in both Washington and on “Main Street,” making government changes virtually impossible. If President Obama wants to implement the change he campaigned on, then he needs to take a more centrist view that concentrates on enduring benefits – not immediate political gains.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Article first submitted to Alrroya.com before being published on Investing Caffeine.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds but at the time of publishing had no direct positions in securities mentioned in the article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Flogging the Financial Firefighter

There we were in the fall of 2008, our economic system burning up in flames, as we all watched century-old financial institutions falling like flies. At the center of the inferno was Federal Reserve Chairman Ben Bernanke. In coordination with other government agencies and officials, Bernanke managed to prevent the worse financial crisis since the Great Depression from completely scorching the economy into ruin. After successfully hosing down the flames (at least temporarily), Ben Bernanke is now being singled out as the scapegoat and getting flogged for being a major participant in the financial crisis.
Execution Threatened Water Damage
In hind-sight could Bernanke have made better decisions? Certainly. Despite the Federal Reserve dousing out the flames, politicians are pointing the finger at Bernanke for causing water damage. I’m going to go out on a limb and say water damage is preferable to the alternative – a whole community of properties burned down to a large pile of charred ash.
Democrats are now flailing in the wake of the Massachusetts Democratic Senate seat loss to Republican Scott Brown. Even though I question President Obama’s blame-game tax and overhaul tactics (see Surgery or Amputation article), to his credit Obama realizes the instability of mass proportion that would occur if the reappointment of Bernanke were to come to fruition. If the head of the globe’s largest financial system is going to be kicked to the curb after saving our economy at the edge of an abyss, then heaven please help us.
Politics Will Reign Supreme in 2010
“Change” was promised in the 2008 Presidential election and the impatient natives are not seeing results fast enough, given lofty unemployment rates and unsuccessful implementation of other initiatives (thus far). Needless to say, the media is going to be awash in an orgy of political mudslinging and campaign promises that will overwhelm the airwaves for the balance of the year.
From a market standpoint, Republicans and Democrats, alike, do share some common ground…jobs. As a countervailing trend to the forces dragging down the economy, the unified focus on job creation should provide some support to the financial markets.
Unfortunately, the independence of the Federal Reserve is being dragged into the political ring as Ben Bernanke’s reappointment process cannot escape the Capitol Hill circus. Berkshire Hathaway (BRKA/B) CEO Warren Buffett has likely handicapped the market’s reaction to a failed Bernanke reappointment when he recently stated, “Just tell me a day ahead of time so I can sell some stocks.” If the fires of 2008 concerned you, you may want to have your fire alarm and water hose ready for action if Chairman Bernanke is shown the exit.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and at the time of publishing had no direct positions in BRKA/B. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Our Nation’s Keys to Success
Politics is not a subject I love to debate, but unfortunately politics has a significant impact on economics, which I do care about dearly. I’m no expert on the politics of New York City’s Mayor Michael Bloomberg, but in reflecting on the past decade he highlights a few key areas of focus needed to advance our great nation:
“There are two things that we did not work on and, in fact, have gone the wrong direction during the last decade, which will dictate the economy for the next decade, and that’s immigration and education.”
I couldn’t agree more. With regard to the country’s stimulus program, we hear so much about shovel-ready projects and infrastructure spending. Rather than centering on the immediate gratification of low-paying job creation and building bridges to nowhere, more resources should be invested in education and recruitment of leading edge human capital. Without a competitive and educated workforce, high-paying 21st Century jobs of the future will be lost and outsourced to global challengers.

Bloomberg emphasizes this point by stating:
“Unless we give our young people the kind of education to compete in the global world, we cannot survive.”
Sure, education is a longer-term investment with no immediate pay-off, but in order to become (remain) competitive with other hungry nations, we need to improve our high school education system, which Microsoft Founder and Chairman Bill Gates calls “obsolete”.
National Suicide
I agree with Mayor Bloomberg that the isolationist immigration pendulum has swung too far in the paranoid direction. The recent airline bombing attempt by Yemeni Umar Farouk Abdulmutallab only fans the flames of fear more intensely. However, in order to attract the best and brightest, we need to relax immigration policies – at least loosen policies as they pertain to educated, law-abiding citizens who can assist our dynamic growing economy. I have no problems with “cherry-picking” immigrants. The foundation of capitalism is based on attracting and retaining the best cherries. Bloomberg notes the following:
“And immigration, we’re committing what I call national suicide. Somehow or other, after 9/11 we went from reaching out and trying to get the best and the brightest to come here, to trying to keep them out. In fact, we do the stupidest thing, we give them educations and then don’t give them green cards.”
If fear of job loss is scaring us from letting foreigners in our country, then we need ask ourselves who will pay for our massive debts, deficits and entitlements (i.e., Social Security and Medicare)? Aging demographics is a huge headwind we face (see demographics article) and a quick glance across the Pacific Ocean to our Japanese allies is proof enough of how destructive the graying of society can become.
Also, many ask the question, “Why should we give American jobs to foreigners?” The reality of the situation is we need a competitve work-force to create a competitive country, which can create more sustainable jobs. How many jobs (and tax-dollars) do you think Google co-founder Sergey Brin (Russian-born) has created for American workers? Or Intel’s former CEO Andy Grove (Hungarian-born); Yahoo’s co-founder Jerry Yang (Taiwanese-born); and Sun Microsystem’s co-founders Vinod Khosla (Indian-born) and Andreas von Bechtolsheim (German-born)? More than a few.
Energy Independence
In his Meet the Press Interview, Bloomberg weaves in another issue dragging down the economy – our dependence on foreign oil. Importing more than 2/3 of our oil from foreign nations, many of which harbor or sponsor U.S.-hating terrorists, is not a prudent long-term strategy when it involves such a critical and strategic resource.
“We’ve got to get, somehow or other, energy independence. And so regardless of whether you’re a greenie or not, the bottom line is we cannot keep funding our enemies,” Bloomberg adds.
As the saying goes, the three most important political issues for re-election are: 1) the economy; 2) the economy; and 3) the economy. Unfortunately, short-term sugar-high stimulus spending may help the economy in the short-run but can wear off quickly if not implemented properly. On the other hand, three key strategic areas of investment will lead to sustainable economic expansion, including education, immigration, and energy independence. With new bitter mid-term Congressional elections waiting for us in 2010, let’s hope the candidates take a lead from Mayor Michael Bloomberg by building on his ideas for a firmer economic foundation in the decade to come.
View Meet The Press Roundtable Interview with Mayor Bloomberg (Minute 2:40)
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds and GOOG, but at time of publishing had no direct positions in MSFT, JAVA, YHOO, or INTC. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Friedman Looks to Flatten Problems in Flat World
Perhaps Friedman could use Gallagher's "Sledge-O-Matic?"
Thomas Friedman, author of recent book Hot, Flat, and Crowded and New York Times columnist, combines a multi-discipline framework in analyzing some of the most complex issues facing our country, from both an economic and political perspective. Friedman’s distinctive lens he uses to assimilate the world, coupled with his exceptional ability of breaking down and articulating these thorny challenges into bite-sized stories and analogies, makes him a one-of-a-kind journalist. Whether it’s explaining the history of war through McDonald’s hamburgers, or using the Virgin Guadalupe to explain the rise of China, Friedman brings highbrow issues down to the eye-level of most Americans.
In his seminal book, The World is Flat, Friedman explains how technology has flattened the global economy to a point where U.S. workers are fighting to keep their domestic tax preparation and software engineering jobs, as new emerging middle classes from developing countries, like China and India, steal work.
The Flat World
In boiling down the recent financial crisis, Friedman used Iceland to explain the “flattening” of the globe:
“Fifteen British police departments lost all their money in Icelandic online savings accounts. Like who knew? I knew the world was flat – I didn’t know it was that flat…that Iceland would become a hedge fund with glaciers.”
The left-leaning journalist hasn’t been afraid to bounce over to the “right” when it comes to foreign affairs and certain fiscally conservative issues. For example, he initially full-heartedly supported George W. Bush’s invasion of Iraq. And on global trade, he has a stronger appreciation of the economic benefits of free trade as compared to traditionally Democratic protectionist views.
Calling All Better Citizens
In a recent Charlie Rose interview, Friedman’s patience with our country’s citizenry has worn thin – he believes government leaders cannot be relied on to solve our problems.
When it comes to the massive deficits and foreign affair issues, Friedman comes to the conclusion we need to cut expenses or raise taxes. By creating a $1 per gallon gasoline tax, Friedman sees a “win-win-win-win” solution. Not only could the country wean itself off foreign oil addiction from authoritarian governments and create scores of new jobs with E.T. (Energy Technologies), the tax could also raise money to reduce our fiscal deficit, and pay for expanded healthcare coverage.
It’s fairly clear to me that government can’t show the leadership in cutting expenses. Since cutting benefits for voters won’t get you re-elected, taxes most certainly will have to go up. Wishful thinking that a recovering economy will do the dirty, debt-cutting work is probably naïve. If forced to pick a poison, the gas tax is Friedman’s choice. I’m not so sure the energy lobby would feel the same?
Political gridlock has always been an obstacle for getting things done in Washington. Technology, scientific polling, 24/7 news cycles, and deep-pocketed lobbyists are only making it tougher for our country to deal with our difficult challenges. Regardless of whether Friedman’s gasoline tax is the silver bullet, I welcome the clear, passionate voice from somebody that understands the challenges of living in a flat world.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) owns certain exchange traded funds (BKF, FXI) and has a short position in MCD at the time this article was originally posted. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Too Big to Sink
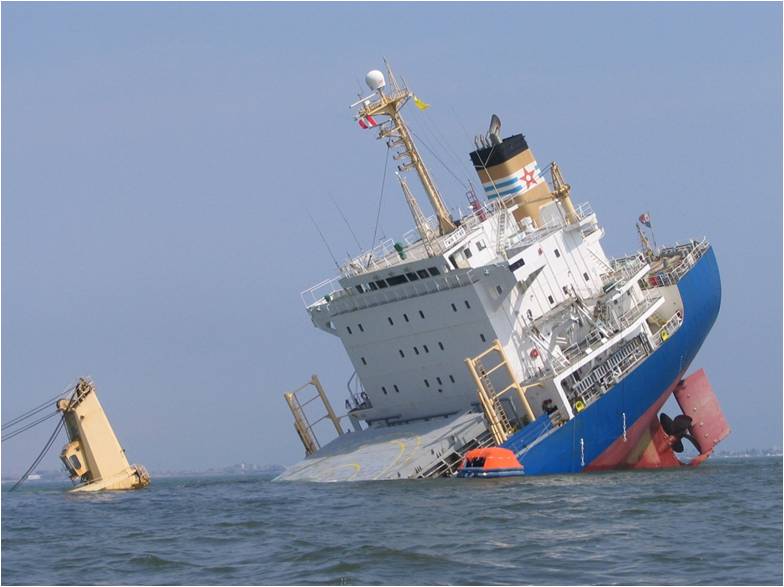
If I got paid a nickel for every time I heard the phrase “too big to fail” to describe the state of affairs of our major financial institutions, I’d be retired on my private island by now. Jeremy Grantham, famed value investor and Chairman of Grantham Mayo Van Otterloo, recently compared the redesigning of our financial system to the Titanic and aptly described the hubris surrounding the ship’s voyage as “too big to sink!”
Mr. Grantham argues that many of the financial institution reform proposals have an irrelevant, misguided focus on improving the safety of the Titanic’s lifeboats rather than the structural design or competence of the captain. Maybe it’s better to plan for disaster prevention rather than disaster preparation? Grantham adds:
“By working to mitigate the pain of the next catastrophe, we allow ourselves to downplay the real causes of the disaster and thereby invite another one.”
When analyzing system failures, incentives are important to understand too. For example, the ship was “under-designed” and the captain had an ill-advised reward baked into a compensation bonus, if he beat the speed record (see article on compensation).
The Solution
Rather than protecting the bankers’ interests, Grantham contends we need “smaller, simpler banks that are not too big to fail.” At the heart of these massive financial conglomerates, pruning is necessary to separate the risky, proprietary trading departments, thereby ridding an “egregious conflict of interest with their clients.” As a former fund manager for a $20 billion fund, I was acutely aware of how my fund trading information and my conversations were being tracked by investment bankers and traders for themselves and their clients’ benefit. When the banks are managing your money alongside their own money, greed has a way of creeping in.
Beyond the prop trading desk legislation, Grantham believes those financial institutions “too big to fail” should be cut down into smaller pieces that can actually fail. Many of these entities are already what I like to call, “too complex to succeed,” evidenced by the stupefied responses provided by Congressmen and the CEOs of the banking institutions during the aftermath of the crisis. Reintroduction of some form of Glass-Steagall legislation (separation of investment banks from commercial banks) is another recommendation made by Grantham.
These suggestions sound pretty reasonable to me, but the bankers scream “If we become smaller and simpler and more regulated, the world will end and all serious banking will go to London, Switzerland, Bali Hai, or wherever,” Grantham adds in a mocking voice. If the foreigners want to operate irresponsibly, then Grantham says let them suffer the negative consequences every 15 years, or so.
The political will of legislators will be tested if substantive financial reforms actually come to pass. Jeremy Grantham understands the extreme importance of reform as explained concisely here, “A simpler, more manageable financial system is much more than a luxury. Without it we shall surely fail again.” Fail that is…like a sinking Titanic.
Read Jeremy Grantham’s Full Quarterly Newsletter
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Compensation: Pitchforks or Penalties

Currently there is witch hunt under way to get rid of excessive compensation levels, especially in the financial and banking industries. Members of Congress and their constituents are looking to reign in the exorbitant paychecks distributed to the fat-cat executives at the likes of Goldman Sachs, Bank of America and the rest of the banking field. According to The Financial Times, Goldman has set aside $16.7 billion so far this year for compensation and benefits and pay is on track to meet or exceed the $661,000 employee average in 2007. The public is effectively calling these executive bankers “cheaters” because they are receiving benefits they don’t deserve. The backlash resembles the finger-pointing we see directed at the wealthy steroid abusers in football or cork-bat swingers in baseball. Americans seem OK with big payouts as long as they are achieved in a fair manner. No one quibbles with the billions made by Bill Gates or Warren Buffett, but when you speak of other wealth cheaters like Jeff Skilling (Enron), Bernie Ebbers (WorldCom), or Dennis Kozlowski (Tyco), then the public cringes. The reaction to corporate crooks is similar to the response provoked by steroid use allegations tied to Major League Baseball players (i.e., Barry Bonds and Roger Clemens).
Less clear are the cases in which cheaters take advantage of a system run by regulators (referees) who are looking the other way or have inadequate rules/procedures in place to monitor the players. Take for example the outrage over $165 million in bonuses paid to the controversial AIG employees of the Financial Products division. Should AIG employees suffer due to lax rules and oversight by regulators? There has been no implication of illegal behavior conducted by AIG, so why should employees be punished via bonus recaptures? The rules in place allowed AIG to issue these lucrative Credit Default Swap (CDS) products (read more about CDS) with inadequate capital requirements and controls, so AIG was not shy in exploiting this lack of oversight. Rule stretchers and breakers are found in all professions. For example, Lester Hayes, famed All-Pro cornerback from the Oakland Raiders, used excessive “Stickum” (hand glue) to give himself an advantage in covering his opponents. If professionals legally operate within the rules provided, then punishments and witch hunts should be ceased.
Regulators, or league officials in sports, need to establish rules and police the players. Retroactively changing the rules after the game is over is not the proper thing to do. What the industry referees need is not pitchforks, but rather some yellow flags and a pair of clear glasses to oversee fair play.
Cash Givers Should Make the Rules
What should regulators and the government do when it comes to compensation? Simply let the “cash givers” make the rules. In the case of companies trading in the global financial markets, the shareholders should drive the rules and regulations of compensation. “Say on pay” seems reasonable to me and has already gained more traction in the U.K. On the other hand, if shareholders don’t want to vote on pay and feel more comfortable in voting for independent board members on a compensation committee, then that’s fine by me as well. If worse comes to worse, shareholders can always sell shares in those companies that they feel institute excessive compensation plans. At the end of the day, investors are primarily looking for companies whose goal it is to maximize earnings and cash flows – if compensation plans in place operate against this goal, then shareholders should have a say.
When it comes to government controlled entities like AIG or Citigroup, the cash givers (i.e., the government) should claim their pound of flesh. For instance, Kenneth Feinberg, the Treasury official in charge of setting compensation at bailed-out companies, decided to cut compensation across the board at American International Group, Citigroup, Bank of America, General Motors, GMAC , Chrysler, and Chrysler Financial for top executives by more than 90% and overall pay by approximately 50%.
Put Away the Pitch Forks
In my view, too much emphasis is being put on executive pay. Capital eventually migrates to the areas where it is treated best, so for companies that are taking on excessive risk and using excessive compensation will find it difficult to raise capital and grow profits, thereby leading to lower share prices – all else equal. Government’s job is to partner with private regulators to foster an environment of transparency and adequate risk controls, so investors and shareholders can allocate their capital to the true innovators and high-profit potential companies. Too big to fail companies, like AIG with hundreds of subsidiaries operating in over 100 countries, should not be able to hide under the veil of complexity. Even in hairy, convoluted multi-nationals like AIG, half a trillion CDS exposure risks need to be adequately monitored and disclosed for investors. That why regulators need to take a page from other perfectly functioning derivatives markets like options and futures and get adequate capital requirements and transparency instituted on exchanges. I’m confident that market officials will penalize the wrongdoers so we can safely put away the pitch forks and pull out more transparent glasses to oversee the industry with.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management and its clients do not have a direct position in Goldman Sachs (GS), AIG, Berkshire Hathaway, BRKA/B, Citigroup (C), Enron, General Motors, GMAC , Chrysler, WorldCom, or Tyco International (TYC) shares at the time this article was originally posted. Sidoxia Capital Management and its clients do have a direct position in Bank of America (BAC). No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Timothy Geithner, the Eddie Haskell Dollar Czar
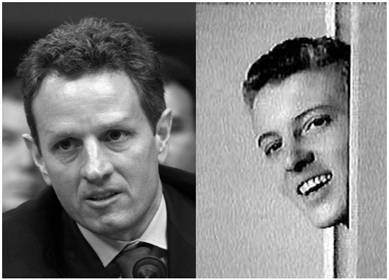
Treasury Secretary Timothy Geithner recently stated after a meeting of G-7 financial officials that “it is very important to the United States that we continue to have a strong dollar.”
With comments like this, why does Timothy Geithner remind me so much of Eddie Haskell (played by Ken Osmond) from the 1950s suburban sitcom Leave It to Beaver? Eddie Haskell plays the scheming trouble maker who is extremely polite on the exterior around adults, but reverts to a crafty conniver once the grown-ups leave the room.
I can just picture the conversations between Treasury Secretary Geithner and President Obama before a high powered meeting with Chinese administration officials:
Geithner: “Barack, the skyrocketing debt will be no problem, we can we shovel plenty of this paper on these Chinese.”
Barack: “Uh, oh…Hu is here for our meeting.”
Geithner: “Oh hello Mr. President Jintao – what a lovely trade surplus you have. We look forward to keeping a very fiscally responsible agenda here in the United States, so you can keep buying our valuable debt.”
Where did Timothy Haskell get his crafty dollar oration skills?
According to David Malpass, president of the research firm Encima Global and deputy assistant Treasury Secretary, Geithner training came from “using a code phrase, a carryover from the Bush administration. It means that the U.S. approves of a constantly weakening dollar but doesn’t want a disruptive collapse.”
These tactics and rhetoric can only work for so long. Exploding deficits and skyrocketing debt levels will eventually lead to a dumping of our debt, rising interest rates, crowding-out of private investments, and a damaging decline in the dollar. Sure, the weakening dollar helps us in the short-run with exports but eventually major U.S. debtholders will no longer buy our sweet talking.
With all the “U.S. dollar is going to collapse” talk, one would think a shift to an SDR (Special Drawing Rights) global currency structure is an inevitable outcome. Just six months ago the governor of China’s central bank argued the U.S. dollar’s role as the world’s reserve currency should be restructured. The SDR model has already been implemented by the IMF (International Monetary Fund), so if the Chinese wanted to create an SDR proxy, they could easily purchase euros, sterling, and yen in proper proportions. Would the Chinese want to make any sudden changes? Certainly not, because any quick adjustments would destroy the value of the Chinese’s existing dollar denominated portfolio. The logistics surrounding a legitimate SDR program would require the IMF or some other international agency to act as a global central bank, which would not only need to determine the appropriate mix of currencies in the SDR, but also decide future global liquidity actions. In order to legitimately run a new SDR program, countries like China would need to give up sovereignty – not a likely scenario.
Until a new SDR regime is agreed upon, dollar-reliant countries will continue to have barks bigger than their bites and Timothy Geithner Haskell will continue to sweet talk U.S. dollar owners.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Hear Eddie (or Treasury Secretary) Speak Here:
Nation’s CEOs Suffering Severely: Pay Down -0.08%

Hold on, let me pull out my violin to play some sympathetic consoling music for our nation’s Chief Executive Officers (CEOs). According to a Corporate Library survey of 2,700 publicly traded companies, CEO compensation declined -0.8% in 2008. I guess that 4th Ferrari and 3rd yacht will have to be put on hold. With some creative perseverance and a little elbow grease, I’m sure the class of underprivileged CEOs can still salvage a healthy package of stock options and restricted stock (to pad the paltry multi-million dollar salaries).
This is what Payscale.com had to say in a report from 2008:
“In 1970, CEO salary and bonus packages were typically about $700,000 – 25 times the average production worker salary; by 2000, CEO salaries had jumped to almost $2.2 million on average, 90 times the average salary of a worker, according to a 2004 study on CEO pay by Kevin J. Murphy and Jan Zabojnik. Toss in stock options and other benefits, and the salary of a CEO is nearly 500 times the average worker salary, the study says.”
Of course, Congress and the public are looking for scapegoats to blame for the global financial crisis. There is no better group to blame than highly compensated CEOs. As a result, we are seeing more “say on pay” proposals brought to shareholder votes, thereby removing power from the hands of self-appointed compensation committees and chummy board members. Currently, a Shareholder Bill of Rights Act is making its rounds through Congress that would establish an annual shareholder vote to approve executive compensation of executive management along with have a separate vote on “golden parachute” payments in the context of a company merger or acquisition.
The U.S. is not the only country to implement these types of shareholder rights. As David Ellis at CNN Money wrote, “In 2002, the United Kingdom embraced the practice, and it has subsequently been taken up in Australia and Sweden.” In the U.S. such proposals being considered are on a “non-binding” basis, which means that if “say on pay” is approved there will be no obligation for management to implement the changes – rather “shame” will be the strategic lever used by shareholders.
Everyone has been impacted in one shape or form by the financial crisis, so when you tuck-in your child or lay your head on the pillow tonight, rest assured our poor corporate CEOs are sharing in the pain…just remember, they only kept 99.2% of their pay last year.
Read More About Corporate Library Survey
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
Spitzer the Pot Calling the Fed Kettle Black
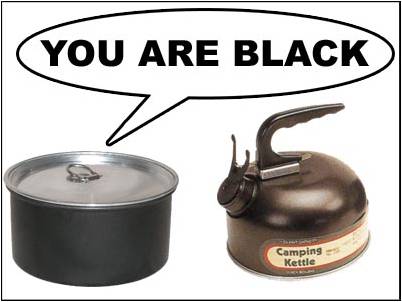
Eliot Spitzer, whose job as the former Attorney General of New York was to convict criminals, was forced to quit himself as Governor for his illegal solicitation of prostitutes that he funded with secretive ATM withdrawals of government funds. Now, Mr. Spitzer is getting on his soapbox and telling others the Federal Reserve has been committing a Ponzi Scheme.
There are a lot of conspiracy theories floating around regarding the Fed’s motives and questions relating to the benefits of those receiving government bailout funds. Dylan Ratigan’s interview of Mr. Spitzer on MSNBC feeds into these conspiracy views. I can buy into conflicts of interests and the need for more transparency arguments, but let’s be realistic, this is not the DaVinci Code, this is the slow, bureaucratic Federal Government. Even if you buy into this skeptical belief, the Fed isn’t exactly a “black box.” The Fed proactively provides the minutes from its private meetings and systematically releases a full accounting of the Fed’s balance sheet (assets).
Mr. Spitzer and other critics point to the egregious benefits handed down to the banks and financial institutions through the bailouts and monetary system actions. Well, wasn’t that the idea? I thought our banking system (and the global banking system) was on the verge of collapse and we were trying to save the world from impending disaster? So, I think most people get the fact that our financial institutions needed a lifeline to prevent worse outcomes from occurring.
Should the Fed have carte blanche on all financial system decisions? Certainly not, but extreme situations like this generational financial crisis we are slogging through now, requires extreme measures.
Accountability I believe is even more important than the micro-managing transparency details Ron Paul (Republican/Libertarian Congressman from Texas) and others are asking for. If indeed it is the Fed’s job to remain an independent body, then maybe it’s not Congress’ job to question every word and minor decision. However, when it comes to these massive bailouts (AIG, Fannie Mae, Freddie Mac, etc.), additional details and accountability should be provided and seems fair. What we don’t need are more regulatory bodies and committees creating more inefficiencies in an already tangled system of regulatory fiefdoms.
Before Mr. Spitzer starts pointing his finger at the black Fed-kettle, perhaps he should get his illegal decision making pot in order first?
Read Full Daniel Tencer Spitzer-Ponzi Scheme Article
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.




 Investing Caffeine

