Posts filed under ‘Government’
Debt Control: Turn Off Costly Sprinklers When Raining
By living in Southern California, I am acutely aware of the water shortage issues we face in this region of the country. We all have our pet peeves, and one that eats at me repeatedly occurs when I drive by a neighbor’s house and notice they are blasting the sprinklers in the pouring rain. I get the same sensation when I read about out-of control government spending confronting our current and future generations in light of the massive debt loads we presently carry.
I, like most people, love free stuff, whether it comes in the form of tooth-pick skewered, teriyaki meatball samples at Costco Wholesale Corp. (COST), or free government education from our school systems. But in times of torrential downpours, at a minimum, we need to be a little more cost conscious of our surroundings and turn off the spending sprinklers.
Certainly, when it comes to government spending, there’s no getting around the entitlement elephant in the room, which accounts for the majority of our non-discretionary government spending (see D-E-B-T: New Four Letter Word article). Unfortunately, layering on new entitlements on top of already unsustainable promises is not aiding our cause. For example, showering our Americans with free drugs as part of Medicare Part D program, and paying for tens of millions into a fantasy-based universal healthcare package (purported to save money…good luck) only serves to fatten up the elephant squeezed into our room.
Reform is absolutely necessary and affordable healthcare should be made available to all, but it is important to cut spending first. Then, subsequently, we will be in a better position to serve the needy with the associated savings. Instead, what we chose appears to have been a jamming of a massive, complex, divisive bill through Congress.
Slome’s Spending Rules
In an effort to guide ourselves back onto a path of sensibility, I urge our government legislators to follow these basic rules as a first step:
Rule #1 – Don’t Pay Dead People: I know we have an innate maternal/paternal instinct to help out others, but perhaps our government could stop doling out taxpayer dollars to buried individuals underground or those people incarcerated in jail? Over the last three years the government sent $180 million in benefit checks to 20,000 corpses, and also delivered $230 million to 14,000 convicted felons (read more).
Rule #2 – Pay for Our Own First: Before we start spending money on others outside our borders, I propose we tend to our flock first. For starters, our immigration policies are a disaster. As I wrote earlier (read Our Nation’s Keys to Success), I am a big proponent of legal immigration for productive, higher-educated individuals – not elitist, just practical. If you don’t believe me, just count the jobs created by the braniac immigrant founders at the likes of Google Inc. (GOOG), Intel Corp. (INTC), and Yahoo! Inc. (YHOO). These are the people who will create jobs and out-battle scrappy, resourceful international competitors that want to steal our jobs and our economic leadership position in the world. What I don’t support is illegal immigration – paying for the healthcare and education of foreign criminals with our country’s maxed-out credit cards. This is the equivalent of someone breaking into my house, and me making their bed and feeding them breakfast…ridiculous. I do not support the immigration law passed in Arizona, but this unfortunate chain of events thankfully puts a spotlight on the issue.
Rule #2a. – Stop Being the Globe’s Free Police: If we are going to comb the caves of Tora Bora as part of funding two wars and chasing terrorists all over the world, then we not only should be spending our defense budget more efficiently (non-Cold War mentality), but also charging freeloaders for our services (directly or indirectly). We are spending a whopping 20 cents of each federal tax dollar on defense, so let’s spend it wisely and charge those outside our borders benefiting from our monetary and physical sacrifices. And, oh by the way, sending $400 million to the territory controlled by Hamas (read more) doesn’t sound like the brightest decision given our fiscal and human challenges at home. I sure hope there are some tangible, accountable benefits accruing to the right people when we have 25 million people here in the U.S. unemployed, underemployed, or discouraged from finding a job.
Rule #3: Put the Obese Elephant on a Diet – As I alluded to above, our government doesn’t need to serve our overweight, entitlement-fed elephant more chocolate, pizza, and ice cream in the form of more entitlements we are not capable of funding. Let’s cut our spending first before we buy off the voters with new spending.
There are obviously a wide ranging set of economic, political, and even religious perspectives on the best ways of managing our hefty debt and deficits. I do not pretend to have all the answers, but what I do know is it is not wise to blast the sprinklers when it is pouring rain outside.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
*DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and GOOG, but at the time of publishing SCM had no direct positions in COST, YHOO, INTC, or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Goldman: Gambling Prosperity at Client Expense?

What a scene that 11-hour Senate subcommittee interrogation of Goldman Sachs (GS) executives was on C-Span – I’m still wondering whether a forklift was utilized to hoist in the multi-thousand page binders stuffed with reams of exhibits. With caffeine beverage firmly in hand, I watched as much of the marathon as possible until fatigue set in. Not all was lost though, because I managed to simultaneously conduct new stock research as I was glued to the hearings. After I saw the Goldman executives repeatedly wrestle open the gargantuan-sized binders of smoking-gun emails, I checked the paper futures markets and am now contemplating a purchase of International Paper’s (IP) stock.
Lead trader of the controversial Abacus/John Paulson deal, “Fabulous Fab” Fabrice Tourre, did not disappoint his supporters either, firmly addressing his responses in his French Pepe Le Pew accent. His Goldman trading counterparts (Daniel Sparks, ex-mortgage department head, Joshua Birnbaum, ex-managing director of the department, and Michael Swenson, current managing director of the department), like all Goldman witnesses, did their best at bobbing and weaving the intrusive, pointed questions. On the cozier side of the questioning fence, the Senators did a superb job of raking the Goldman execs over the coals with endless exhibits of emails. Judging by the shiny, sweating mugs of the traders, the Senators were successful in making the testifiers uncomfortable – either that, or the Senators had the thermostat in the room raised to 82 degrees.
Betting Away to Profits
At the heart of the questioning was the key issue of whether Goldman Sachs executives and employees were acting in the best interest of their clients (fiduciary duty), or were they making bets against clients with the benefit of privileged information. Senator Claire McCaskill compared Goldman to a bookie manipulating bets in their own favor without sharing their edge with bettors (investors). In the case of the Abacus deal, Goldman admits to not freely disclosing the involvement of now-famous, mortgage market short seller John Paulson (see the Gutsiest Trade) to the so-called sophisticated institutional investors, ACA Capital Holdings Inc. Was this lack of disclosure illegal? Perhaps unethical, but pundits have already established the high hurdle the SEC (Securities and Exchange Commission) will need to clear in order to prove Goldman’s guilt.
Based on the testimony and facts introduced in the hearings, and as I write in my previous Goldman article (Goldman Cheat?), Goldman’s behavior throughout the housing collapse and participation in the ACA deal reflects more about intelligent opportunism within a loose regulatory framework than it does about criminal behavior. Having managed a $20 billion fund (see my book) I dealt with the conflicts of interest and self dealings of the investment banks first hand. As I entered trade orders reaching into the millions of shares, do I naively believe Goldman and other banks altruistically kept that information in their trading vaults? Or is it possible that information leaked out to other clients or was used for the banks benefit? Suffice it to say, the regulatory structure and conflict of interest frameworks, as they stand today, are not stacked in favor of investors.
The Solutions
Although we wish our regulators and government officials could have been more forward looking, rather than reactive, nonetheless, some reforms need to be instituted to resolve the substantial risks built into our financial system today. Here are a few ideas from the 10,000 foot level:
Volcker Rule: Former Federal Reserve Chairman’s so-called “Volcker Rule” is looking better by the minute. Not a new concept, but as regulators shine the light on the opaque industry of derivatives trading and proprietary trading desks, the need for new reforms becomes even more evident. Derivatives are not evil (see Financial Engineering), but like a gun or knife, if misused these instruments can become extremely dangerous…as we have found out. The Glass-Steagall Act, which separated investment bank functions from commercial bank functions, was repealed almost 70 years after its introduction in 1932. The Volcker Rule would be a “lite” version of Glass-Steagall Act because the thrust of the proposal is aimed at splitting the risk-taking proprietary trading desk activities from the client based activities.
Heightened Capital: If you rented out an exotic car or motorcycle from a store, you would likely be required to commit a deposit or collateral to protect against adverse conditions. The same principle applies to derivatives, which generally raises volatility due to inherent leverage. The riskier the product, the larger the capital requirement should be. The collapse of Bear Stearns, Lehman Brothers, and AIG are painful lessons learned from situations of excessive leverage.
Central Clearing/Transparency: Derivative products such as options, futures, and swaps have existed for decades. The transparency gained by trading these securities on exchanges increases market confidence, thereby increasing liquidity and lowering costs for end-users. Standardization around complex derivatives like CDOs (Collateralized Debt Obligations), CDSs (Credit Default Swaps), and CLOs (Collateralized Loan Obligations) is a must to ensure the fact regulators can actually understand the products they are regulating.
Credit Rating Agency: It’s not entirely clear to me that the rating agencies play a critical role in the market place. In effect, the agencies serve as an outsourced research resource primarily for fixed income investors. If the agencies disappeared today, investors would be forced to do their own homework on each deal – not necessarily a bad idea. If the existing oligopoly structure of agencies ultimately survives, I suggest penalties should be incurred by firms with inaccurate ratings. Conversely, ratings could be structured such that compensation could be tiered (or escrowed) over time with payment incentives tied to the underlying deal performance relative to ratings accuracy.
Too Big To Fail: The massive bailouts and TARP (Troubled Asset Relief Program) money handed out to the financial and auto companies have left a sour taste in taxpayers’ mouths. A systemic risk regulator with the authority to unwind unhealthy institutions makes common sense. An insurance pool financed by self-inflicted industry taxes would assist regulators in achieving the reduction of troubled financial institutions.
Fiduciary Duty: Sidoxia Capital Management is a Registered Investment Advisor (RIA) and must act in the best interests of the client. Unfortunately, much of the industry is structured with a much lower “suitability” threshold, which provides a veil for firms to engage in less than ethical behavior.
Overall, regulatory reform urgency is in the Washington D.C. air and there is no question in my mind that a certain degree of witch hunting and scapegoating is occurring. Nonetheless, Lloyd Blankfein and team Goldman Sachs made it out alive from the Congressional hearing, but not without suffering some negative reputational damage. Former Goldman CEO alum and Treasury Secretary Henry Paulson probably sent roses to Mr. Blankfein thanking him for taking Paulson’s job before the 2008 market collapse. When regulatory reform eventually kicks in, perhaps Lloyd Blankfein and Henry Paulson will take a trip to Las Vegas to celebrate (or commiserate).
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
*DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds and in a security derived from an AIG subsidiary, but at the time of publishing SCM had no direct positions in GS, IP, AIG, JPM/Bear Stearns, LEH/Barclays or any security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Mozilo and Healthcare Tan Tax to the Rescue?

Ideological trains came crashing together as the battle for comprehensive healthcare reform resulted in the whole enchilada approach of the Democrats winning over the baby-step approach advocated by the Republicans. Thank goodness there is a savior to remedy the hefty $940 billion costs of the national healthcare plan…Angelo Mozilo. Not only will this mortgage tycoon (former CEO of Countrywide – the largest U.S. mortgage lender at one time) have his fat-cat wallet to fund multiple new healthcare taxes on the wealthy, but the government will also be collecting a new 10% tanning tax on all Mr. Mozilo’s bronzing sessions. Perhaps the CBO (Congressional Budget Office) healthcare reform cost saving estimates ($138 billion in the first decade) may come in even better than anticipated?
20,000,000 Tanning Sessions to Health
The public shouldn’t shed a tear for the real estate pain Mr. Mozilo endured – he still managed to stash a nice pile of dough before the mortgage walls came tumbling down on him. Given Mr. Mozilo’s timely sale of about $300 million in Countrywide stock before the share price cratered, coupled with the $23.8 million retirement fund and roughly $21 million in deferred compensation (Minyanville.com), Mr. Mozilo should have enough money to cover about 20,000,000 tanning sessions by my calculation. That sounds like a rather large number, but I expect Mr. Mozilo will shrewdly negotiate a bulk discount for the sessions, even if the government disapproves of the asssociated lost tax revenues.
However, one major potential hurdle for Mozilo may be finding the adequate time for tanning. If the SEC (Securities and Exchange Commission) is successful in prosecuting him on the alleged securities fraud and insider trading charges, then he may need to petition for a tanning bed in the prison gym.
Unintended Beach-going Consequences
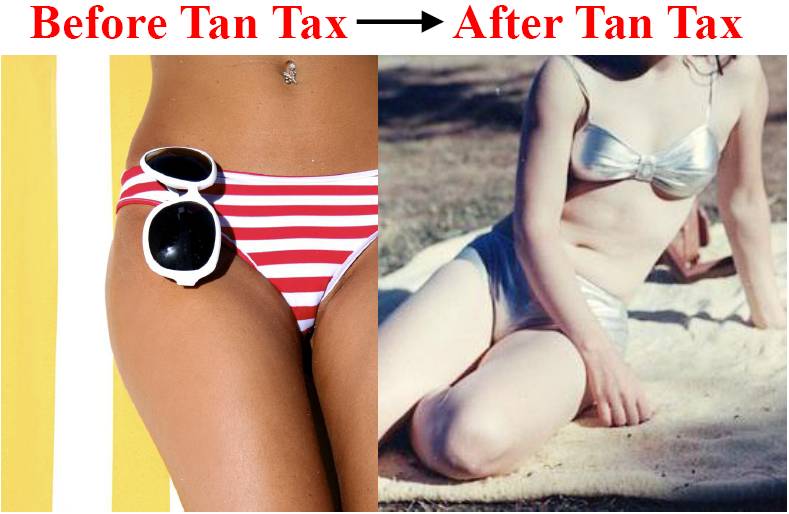
Although we all condemn the harmful side effects of skin cancer from sunbathing, let’s not completely dismiss some of the advantages, including the benefits of Vitamin D production. Other cited ailments benefitting from sunlight exposure include, eczema, arthritis, psoriasis, acne, season affective disorder, and depression. One of the worse afflictions suffered by beach-goers (male and female alike) is the tragic “pastiness” condition. One of the severe unintended consequences of President Obama’s tanning tax may indeed be the extreme ridicule unleashed on light skinned beach bums that are unable to afford the tanning tax (see photo below).
Toss the Drumstick
On a more serious note, I get the fact that the government wants to raise a substantial amount of money to cover an extensive healthcare bill like this one – either through taxes and/or cost cuts. However, I think there are other areas in the healthcare food chain that need to climb higher in the national debate. Although, I’m OK with the tanning tax, I strongly believe there is more fertile ground in attacking obesity (see article on the Economics and Consequences of Obesity) and other costlier areas of treatment. The amount of money spent on managing obesity, and associated ailments, trounces the expenditures directed towards cancer by more than $50 billion by some estimates. Dated data shows we are spending more than $100 billion dollars on obesity-related healthcare costs. One study estimates obesity costs in the United States will reach $344 billion by 2018.
Bolstering the severity of the condition, the CDC (Center of Disease Control) noted the following:
“More than one third of U.S. adults—more than 72 million people—and 16% of U.S. children are obese. Since 1980, obesity rates for adults have doubled and rates for children have tripled. Obesity rates among all groups in society—irrespective of age, sex, race, ethnicity, socioeconomic status, education level, or geographic region—have increased markedly.”
I realize the importance of a copper tone tan can have on the lives of millions of Americans, and I also recognize the tanning tax is just a small blip in the growing 2,200 healthcare bill signed into law. Nonetheless, the spotlight of the healthcare debate needs to focus on the highest cost silos (i.e., obesity). Otherwise, I’m not completely sure whether all of Angelo’s taxed tanning sessions will be enough to cover our country’s immense healthcare costs?
Related Article: Bill Maher Chearleads No Profit Healthcare
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
*DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at the time of publishing had no direct positions in BAC or any security mentioned in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Digging a Debt Hole

Little did I know when I signed up for a recent “distressed” debt summit (see previous article) that a federal official and state treasurer would be presenting as keynote speakers? After all, this conference was supposed to be catering to those professionals interested in high risk securities. Technically, California and the U.S. government are not classified as distressed yet, but nonetheless government heavy-hitters Matthew Rutherford (Deputy Assistant Secretary, Federal Finance at the U.S. Department of Treasury), and Bill Lockyer (Treasurer for the State of California) shared their perspectives on government debt and associated economic factors.
Why have government officials present at a distressed debt conference? After questioning a few organizers and attendees, I was relieved to discover the keynote speaker selections were made more as a function as a sign of challenging economic times, rather than to panic participants toward debt default expectations. As it turns out, the conference organizers packaged three separate conferences into one event – presumably for cost efficiencies (Distressed Investments Summit + Public Funds Summit + California Municipal Finance Conference).
The U.S. Treasury Balancing Act
Effectively operating as the country’s piggy bank, the Treasury has a very complex job of constantly filling the bank to meet our country’s expenditures. Deputy Assistant Secretary Matthew Rutherford launched the event by speaking to domestic debt levels and deficits along with some the global economic trends impacting the U.S.
- Task at Hand: Rutherford spoke to the Treasury’s three main goals as part of its debt management strategy, which includes: 1) Cash management (to pay the government bills); 2) Attempt to secure low cost financing; and 3) Promote efficient markets. With more than a few hundred auctions held each year, the Treasury manages an extremely difficult balancing act.
- Debt Limit Increased: The recent $1.9 trillion ballooning in the U.S. debt ceiling to $14.3 trillion gives the Treasury some flexibility in meeting the country’s near-term funding needs. The Treasury expects to raise another $1.5 trillion in debt in 2010 (from $1.3 trillion in ’09) to fund our government initiatives, but that number is expected to decline to $1.0 – $1.1 trillion in 2011.
- Funding Trillions at 0.16%: Thanks to abnormally low interest rates, an investor shift to short-term safety (liquidity), and a temporary rush to the dollar, the U.S. Treasury was able to finance their borrowing needs at a mere 16 basis points. Clearly, servicing the U.S.’ massive debt load at these extremely attractive rates is not sustainable forever, and the Treasury is doing its best to move out on the yield curve (extend auctions to lengthier maturities) to lock in lower rates and limit the government’s funding risk should short-term rates spike.
- Chinese Demand Not Waning: Contrary to recent TIC (Treasury International Capital) data that showed Japan jumping to the #1 spot of U.S. treasury holders, Rutherford firmly asserted that China remains at the top by a significant margin of $140 billion, if you adjust certain appropriate benchmarks. He believes foreign ownership at over 50% (June 2009) remains healthy and steady despite our country’s fiscal problems.
- TIPS Demand on the Rise: Appetite for Treasury Inflation Protection Securities is on the rise, therefore the Treasury has its eye on expanding its TIP offerings into longer maturities, just last week they handled their first 3-year TIPS auction.
There is no “CA” in Greece
State of California Treasurer Bill Lockyer did not sugarcoat California’s fiscal problems, but he was quick to defend some of the comparisons made between Greece and California. First of all, California’s budget deficit represents less than 1% of the state’s GDP (Gross Domestic Product) versus 13% for Greece. Greece’s accumulated debt stands at 109% of GDP – for California debt only represents 4% of the state’s GDP. What’s more, since 1800 Greece has arguably been in default more than not, where as California has never in its history defaulted on an obligation.
The current California picture isn’t pretty though. This year’s fiscal budget deficit is estimated at $6 billion, leaping to $12 billion next year, and soaring to $20 billion per year longer term.
Legislative political bickering is at the core of the problem due to the constitutional inflexibility of a 2/3 majority vote requirement to get state laws passed. The vast bulk of states require a simple majority vote (> than 50%) – California holds the unique super-majority honor with only Arkansas and Rhode Island. Beyond mitigating partisan bickering, Lockyer made it clear no real progress would be made in budget cuts until core expenditures like education, healthcare, and prisons are attacked.
On the subject of bloatedness, depending on how you define government spending per capita, California ranks #2 or #4 lowest out of all states. Economies of scale help in a state representing 13% of the U.S.’ GDP, but Lockyer acknowledged the state could just be less fat than the other inefficient states.
Lockyer also tried to defend the state’s 10.5% blended tax rate (versus the national median of 9.8%), saying the disparity is not as severe as characterized by the media. He even implied there could be a little room to creep that rate upwards.
Finishing on an upbeat note, Lockyer recognized the January state revenues came in above expectations, but did not concede victory until a multi-month trend is established.
After filtering through several days of meetings regarding debt, you quickly realize how the debt culture (see D-E-B-T article), thanks to cheap money, led to a glut across federal governments, state governments, corporations, and consumers. Hopefully we have learned our lesson, and we are ready to climb out of this self created hole…before we get buried alive with risky debt.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (including CMF and TIP), but at time of publishing had no direct position on any security referenced. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Money Goes Where Treated Best

“The world is going to hell in a handbasket” seems to be a prevailing sentiment among many investors. Looking back, a lack of fiscal leadership in Washington, coupled with historically high unemployment, has only fanned the flames of restlessness. A day can hardly go by without hearing about some fiscal problem occurring somewhere around the globe. Geographies have ranged from Iceland to Dubai, and California to Greece. Regardless, eventually voters force politicians to take notice, as we recently experienced in the Massachusetts vote for Senator.
Time to Panic?
So is now the time to panic? Entitlement obligations such as Social Security and Medicare, when matched with a rising interest payment burden from our ballooning debt, stands to consume the vast majority of our country’s revenues in the coming decades (if changes are not made). It’s clear to most that the current debt trajectory is not sustainable – see also Debt: The New Four-Letter Word. With that said, historical debt levels have actually been at higher levels before. For example, during World War II, debt levels reached 122% of GDP (Gross Domestic Product). Since promises generally garner votes, politicians have traditionally found it easier to legislate new spending into law rather than cutting back existing spending and benefits.
Money Goes Where it’s Treated Best
If our government leaders choose to ignore the growing upswell in fiscal discontent, then the global financial markets will pay more attention and disapprove less diplomatically. As the globe’s reserve currency, the U.S. Dollar stands to collapse if a different direction is not forged, and interest costs could skyrocket to unpalatable levels. Fortunately, the flat world we live on has created some of these naturally occurring governors to forcibly direct sovereign entities to make better decisions…or suffer the consequences. Right now Greece is paying for the financial sins of its past, which includes widening deficits and untenable debt levels.
As new, growing powers such as China, Brazil, India, and other emerging countries fight for precious capital to feed the aspirational goals of their rising middle classes, money will migrate to where it is treated best. Speculative money will flow in and out of various capital markets in the short-run, but ultimately capital flows where it is treated best. Meaning, those countries with policies fostering fiscal conservatism, financial transparency, prudent regulations, pro-growth initiatives, tax incentives, order of law, and other capital-friendly guidelines will enjoy their fair share of the spoils. The New York Times editorial journalist Tom Friedman coined the term “golden straitjacket” in describing this naturally occurring restraint system as a result of globalization.
Push Comes to Shove
Push will eventually come to shove, but the real question is whether we will self-impose fiscal restraint on ourselves, or will the global capital markets shove us in that direction, like the markets are doing to Greece (and other financially strapped nations) today? I am hopeful it will be the former. Why am I optimistic? Although more government spending has typically lead to more votes for politicians, cracks in the support wall have surfaced through the Massachusetts Senatorial vote, and rising populist sentiment, as manifested through the “Tea Party” movement (previously considered a fringe group).
Political gridlock has traditionally been par for the course, but crisis usually leads to action, so I eventually expect change. I am banking on the poisonous and sour mood permeating through the country’s voter base, in conjunction with the collapse of foreign currencies, to act as a catalyst for financial reform. If not, resident capital and domestic jobs will exodus to other countries, where they will be treated best.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds (including emerging market-based ETFs), but at time of publishing had no direct positions in securities mentioned in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Fed Ponders New Surgical Tool
The Fed is closely monitoring the recovering patient (the U.S. economy) after providing a massive dose of monetary stimulus. The patient is feeling numb from the prescription, but if the Fed is not careful in weaning the subject off the medicine (dangerously low Federal Funds rate), dangerous side- effects such as a brand new bubble, rampant inflation, or a collapsing dollar could ensue.
In preparing for the inevitable pain of the Federal Reserve’s “exit strategy,” the institution is contemplating the use of a new tool – interest rates paid to banks on excess reserves held at the Fed. A likely by-product of any deposit-based rate increase will be higher rates charged on consumer loans.
Currently, the Federal Reserve primarily controls the targeted Federal funds rate (the rate at which banks make short-term loans to each other) through open market operations, such as the buying and selling of government securities. Specifically, repurchase agreements made between the Federal Reserve and banks are a common strategy used to control the supply and demand of money, thereby meeting the Fed’s interest rate objective.

Source: Data from Federal Reserve Bank via Wikipedia
Although a relatively new tool created from a 2006 law, paying interest on excess reserves can help in stabilizing the Federal Funds rate when the system is awash in cash – the Fed currently holds over $1 trillion in excess reserves. Failure to meet the inevitably higher Fed Funds target is a major reason policymakers are contemplating the new tool. The Fed started paying interest rates on reserves, presently 0.25%, in the midst of the financial crisis in late 2008. Rate policy implementation based on excess reserves would build a stable floor for Federal Funds rate since banks are unlikely to lend to each other below the set Fed rate. The excess reserve rate-setting tool, although a novel one for the United States, is used by many foreign central banks.
Watching the Fed
While the Fed discusses the potential of new tools, other crisis-originated tools designed to improve liquidity are unwinding. For example, starting February 1st, emergency programs supporting the commercial paper, money market, and central bank swap markets will come to a close. The closure of such program should have minimal impact, since the usage of these tools has either stopped or fizzled out.
Fed watchers will also be paying attention to comments relating to the $1 trillion+ mortgage security purchase program set to expire in March. A sudden repeal of that plan could lead to higher mortgage rates and hamper the fragile housing recovery.
When the Fed policy makers meet this week, another tool open for discussion is the rate charged on emergency loans to banks – the discount rate (currently at 0.50%). Unlike the interest rate charged on excess reserves, any change to the discount rate will not have an impact charged on consumer loans.
While the Fed’s exit strategy is a top concern, market participants can breathe a sigh of relief now that Federal Reserve Chairman Ben Bernanke has been decisively reappointed – lack of support would have resulted in significant turmoil.
The patient (economy) is coming back to life and now the extraordinary medicines prescribed to the subject need to be responsibly removed. As the Federal Reserve considers its range of options, old instruments are being removed and new ones are being considered. The health of the economy is dependent on these crucial decisions, and as a result all of us will be carefully watching the chosen prescription along with the patient’s vital signs.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds but at the time of publishing had no direct positions in securities mentioned in the article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Flogging the Financial Firefighter

There we were in the fall of 2008, our economic system burning up in flames, as we all watched century-old financial institutions falling like flies. At the center of the inferno was Federal Reserve Chairman Ben Bernanke. In coordination with other government agencies and officials, Bernanke managed to prevent the worse financial crisis since the Great Depression from completely scorching the economy into ruin. After successfully hosing down the flames (at least temporarily), Ben Bernanke is now being singled out as the scapegoat and getting flogged for being a major participant in the financial crisis.
Execution Threatened Water Damage
In hind-sight could Bernanke have made better decisions? Certainly. Despite the Federal Reserve dousing out the flames, politicians are pointing the finger at Bernanke for causing water damage. I’m going to go out on a limb and say water damage is preferable to the alternative – a whole community of properties burned down to a large pile of charred ash.
Democrats are now flailing in the wake of the Massachusetts Democratic Senate seat loss to Republican Scott Brown. Even though I question President Obama’s blame-game tax and overhaul tactics (see Surgery or Amputation article), to his credit Obama realizes the instability of mass proportion that would occur if the reappointment of Bernanke were to come to fruition. If the head of the globe’s largest financial system is going to be kicked to the curb after saving our economy at the edge of an abyss, then heaven please help us.
Politics Will Reign Supreme in 2010
“Change” was promised in the 2008 Presidential election and the impatient natives are not seeing results fast enough, given lofty unemployment rates and unsuccessful implementation of other initiatives (thus far). Needless to say, the media is going to be awash in an orgy of political mudslinging and campaign promises that will overwhelm the airwaves for the balance of the year.
From a market standpoint, Republicans and Democrats, alike, do share some common ground…jobs. As a countervailing trend to the forces dragging down the economy, the unified focus on job creation should provide some support to the financial markets.
Unfortunately, the independence of the Federal Reserve is being dragged into the political ring as Ben Bernanke’s reappointment process cannot escape the Capitol Hill circus. Berkshire Hathaway (BRKA/B) CEO Warren Buffett has likely handicapped the market’s reaction to a failed Bernanke reappointment when he recently stated, “Just tell me a day ahead of time so I can sell some stocks.” If the fires of 2008 concerned you, you may want to have your fire alarm and water hose ready for action if Chairman Bernanke is shown the exit.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, and at the time of publishing had no direct positions in BRKA/B. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Our Nation’s Keys to Success
Politics is not a subject I love to debate, but unfortunately politics has a significant impact on economics, which I do care about dearly. I’m no expert on the politics of New York City’s Mayor Michael Bloomberg, but in reflecting on the past decade he highlights a few key areas of focus needed to advance our great nation:
“There are two things that we did not work on and, in fact, have gone the wrong direction during the last decade, which will dictate the economy for the next decade, and that’s immigration and education.”
I couldn’t agree more. With regard to the country’s stimulus program, we hear so much about shovel-ready projects and infrastructure spending. Rather than centering on the immediate gratification of low-paying job creation and building bridges to nowhere, more resources should be invested in education and recruitment of leading edge human capital. Without a competitive and educated workforce, high-paying 21st Century jobs of the future will be lost and outsourced to global challengers.

Bloomberg emphasizes this point by stating:
“Unless we give our young people the kind of education to compete in the global world, we cannot survive.”
Sure, education is a longer-term investment with no immediate pay-off, but in order to become (remain) competitive with other hungry nations, we need to improve our high school education system, which Microsoft Founder and Chairman Bill Gates calls “obsolete”.
National Suicide
I agree with Mayor Bloomberg that the isolationist immigration pendulum has swung too far in the paranoid direction. The recent airline bombing attempt by Yemeni Umar Farouk Abdulmutallab only fans the flames of fear more intensely. However, in order to attract the best and brightest, we need to relax immigration policies – at least loosen policies as they pertain to educated, law-abiding citizens who can assist our dynamic growing economy. I have no problems with “cherry-picking” immigrants. The foundation of capitalism is based on attracting and retaining the best cherries. Bloomberg notes the following:
“And immigration, we’re committing what I call national suicide. Somehow or other, after 9/11 we went from reaching out and trying to get the best and the brightest to come here, to trying to keep them out. In fact, we do the stupidest thing, we give them educations and then don’t give them green cards.”
If fear of job loss is scaring us from letting foreigners in our country, then we need ask ourselves who will pay for our massive debts, deficits and entitlements (i.e., Social Security and Medicare)? Aging demographics is a huge headwind we face (see demographics article) and a quick glance across the Pacific Ocean to our Japanese allies is proof enough of how destructive the graying of society can become.
Also, many ask the question, “Why should we give American jobs to foreigners?” The reality of the situation is we need a competitve work-force to create a competitive country, which can create more sustainable jobs. How many jobs (and tax-dollars) do you think Google co-founder Sergey Brin (Russian-born) has created for American workers? Or Intel’s former CEO Andy Grove (Hungarian-born); Yahoo’s co-founder Jerry Yang (Taiwanese-born); and Sun Microsystem’s co-founders Vinod Khosla (Indian-born) and Andreas von Bechtolsheim (German-born)? More than a few.
Energy Independence
In his Meet the Press Interview, Bloomberg weaves in another issue dragging down the economy – our dependence on foreign oil. Importing more than 2/3 of our oil from foreign nations, many of which harbor or sponsor U.S.-hating terrorists, is not a prudent long-term strategy when it involves such a critical and strategic resource.
“We’ve got to get, somehow or other, energy independence. And so regardless of whether you’re a greenie or not, the bottom line is we cannot keep funding our enemies,” Bloomberg adds.
As the saying goes, the three most important political issues for re-election are: 1) the economy; 2) the economy; and 3) the economy. Unfortunately, short-term sugar-high stimulus spending may help the economy in the short-run but can wear off quickly if not implemented properly. On the other hand, three key strategic areas of investment will lead to sustainable economic expansion, including education, immigration, and energy independence. With new bitter mid-term Congressional elections waiting for us in 2010, let’s hope the candidates take a lead from Mayor Michael Bloomberg by building on his ideas for a firmer economic foundation in the decade to come.
View Meet The Press Roundtable Interview with Mayor Bloomberg (Minute 2:40)
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds and GOOG, but at time of publishing had no direct positions in MSFT, JAVA, YHOO, or INTC. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Too Big to Fail (Review)
Some call Andrew Ross Sorkin’s new behind-the-scenes book about the financial crisis of 2008-2009 “Too Big to Read” due to its meaty page count at 624 pages (a tad more than my book). But actually, once you crack the first chapter of Too Big to Fail you become immediately sucked in. In creating the “fly on the wall” perspective covering the elite power brokers of Wall Street and Washington, Sorkin utilizes 500 hours of interviews with more than 200 individuals.
Through the detailed and vivid conversations, you get the keen sense of overwhelming desperation and self-preservation that overtakes the executives of the sinking financial system. Some of the chief participants failed, some were triumphant, and some were pathetically bailed out. History will ultimately be the arbiter of whether government and Wall Street averted, mitigated, postponed, or contributed to the financial collapse. Regardless, Sorkin brilliantly encapsulates this emotionally panicked period in our history that will never be erased from our memories.
Here are a few passages that capture the feeling and mood of the book:
Merger Musical Chairs
The terror-induced insanity of merger musical chairs is best depicted through the notepad of Timothy Geithner, then the president of the New York Federal Reserve Bank:
“On a pad that morning, Geithner started writing out various merger permutations: Morgan Stanley and Citigroup. Morgan Stanley and JP Morgan Chase. Morgan Stanley and Mitsubishi. Morgan Stanley and CIC. Morgan Stanley and Outside Investor. Goldman Sachs and Citigroup. Goldman Sachs and Wachovia. Goldman Sachs and Outside Investor. Fortress Goldman. Fortress Morgan Stanley. It was the ultimate Wall Street chessboard.”
AIG Bombshell
The book is also laced with financial nuggets to put the scope of the crisis in perspective. Here Sorkin examines the distressed call of assistance from AIG CEO, Bob Willumstad, to Timothy Geithner:
“A bombshell that Willumstad was confident would draw Geithner’s attention-was a report on AIG’s counterparty exposure around the world, which included ‘$2.7 trillion of notional derivative exposures, with 12,000 individual contracts.” About halfway down the page, in bold, was the detail that Willumstad hoped would strike Geithner as startling: “$1 trillion of exposures concentrated with 12 major financial institutions.’”
Bernanke’s Bumbled Spelling Bee
In setting the stage for the drama that unfolds, Sorkin also provides a background on the key players in the book. For example in describing Ben Bernanke you learn he was
“born in 1953 and grew up in Dillon South Carolina, a small town permeated by the stench of tobacco warehouses. As an eleven-year-old, he traveled to Washington to compete in the national spelling championship in 1965, falling in the second round, when he misspelled ‘Edelweiss.’”
TARP Tidbits
On how the precise $700 billion TARP (Troubled Asset Relief Program) figure was created, Sorkin describes the scattered thought process of the program designer Neel Kashkari:
“They knew they could count on Kashkari to perform some sort of mathematical voodoo to justify it: ‘There’s around $11 trillion of residential mortgages, there’s around $3 trillion of commercial mortgages, that leads to $14 trillion, roughly five percent of that is $700 billion.’ As he plucked numbers from thin air even Kashkari laughed at the absurdity of it all.”
Mercedes Moment
Mixed in with the facts and downbeat conversations are a series of humorous anecdotes and one-liners. Here is one exchange between Goldman Sachs CEO, Lloyd Blankfein, and his Chief of Staff Russell Horwitz:
“’I don’t think I can take another day of this,’ Horowitz said wearily. Blankfein laughed. ‘You’re getting out of a Mercedes to go to the New York Federal Reserve – you’re not getting out of a Higgins boat* on Omaha Beach! Keep things in perspective.’”
*Blankfein’s quote: A reference to the bloody D-Day battle.
Too Big to Fail is an incredible time capsule for the history books. Let’s hope we do not have to relive a period like this in our lifetimes. I wouldn’t mind reading another Andrew Ross Sorkin book…just not another one about a future financial crisis.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but did not have any direct positions in any stock mentioned in this article at time of publication (including GS, AIG, WFC, MS, and C). No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.
Plucking the Feathers of Taxpaying Geese
“The art of taxation consists in so plucking the goose as to get the most feathers with the least hissing.” ~Jean Baptist Colbert
With exploding deficits, multiple wars, healthcare reform, and a sluggish economy, there are two logical immediate choices on how to improve our current financial situation:
1) Cut spending. This is not a desirable option for politicians since benefit cuts to voters are not appreciated come re-election period.
2) Raise Taxes. Not desirable from a voter standpoint either, but the Obama administration has chosen to target the rich – the smaller voting population. This can of course backfire, when many of these wealthy individuals are campaign contributors or have ties to lobbyists who are backing the President’s agendas.
The tax-paying geese are getting fatter, but before the goose can be put in the oven, the feathers need plucking with the goal of minimizing hissing. Sure, I am an advocate for tax cuts like most taxpayers. I’m even a larger proponent, if Congress had the political gumption to cut spending to fund the tax drops. Unfortunately, politicians view expense reduction as suicide because cutting programs or benefits will only lead to fewer reelection votes. Congressmen are perfectly fine letting taxpayers live high on the hog for now, and just saddle future generations with our mounting debt problems.
What’s Fair?
The current strategy is based on taxing the wealthy to fund deficits, healthcare, wars, debt, etc. Since the rich represent a smaller proportion of voters, from the egotistical politician standpoint (reelection is paramount), this wealth distribution strategy appears more palatable to incumbent legislators. Democrats would rather focus on squeezing a narrower demographic footprint of voters versus an across the board tax increase, which would impact all taxpayers. Merely taxing the rich can certainly backfire however, especially if the wealthy demographic getting taxed is the exact population paying for the politicians’ reelection and lobbying agendas.
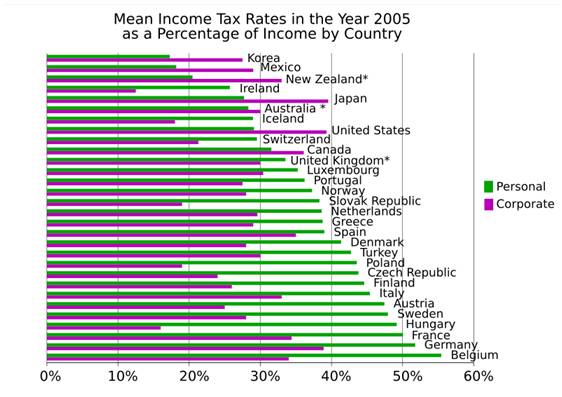
Source: Alan’s Money Blog (U.S. has high corporate tax rate)
But at what point is taxing the rich unfair and counterproductive? Currently the top 10% of the nation that earns more than $92,400 a year, pay about 72% of the country’s income taxes. Ari Fleischer, former G.W. Bush Press Secretary compares the current tax policy to an “inverted pyramid scheme” in a Wall street Journal Op-Ed earlier this year. Like an upside spinning top, the whirling pyramid is supported by a narrow, pointy pinnacle.
Fleischer goes onto add:
“According to the CBO, those who made less than $44,300 in 2001 — 60% of the country — paid a paltry 3.3% of all income taxes. By 2005, almost all of them were excused from paying any income tax. They paid less than 1% of the income tax burden. Their share shrank even when taking into account the payroll tax. In 2001, the bottom 60% paid 16.3% of all taxes; by 2005 their share was down to 14.3%. All the while, this large group of voters made 25.8% of the nation’s income. When you make almost 26% of the income and you pay only 0.6% of the income tax, that’s a good deal, courtesy of those who do pay income taxes.”
Cheaters Should Not Be Exempt (See Celebrity Tax Evader Article)
Certainly loopholes and undeserving credits for multinationals and the wealthy should be removed as well. The House of Representatives recently approved a $387 million boost for the IRS to fund a high-wealth unit focusing on trusts, real estate investments, privately held companies and other business entities controlled by rich individuals (read Reuters article). The IRS is also opening new criminal offices in Beijing, Panama City and Sydney to focus on international enforcement of tax cheaters. At the center of the IRS’ offshore effort is the legal cases against Swiss banking giant UBS (stands for Union Bank of Switzerland), which resulted in UBS agreeing to turn over almost 5,000 client names and pay $780 million to settle tax evasion charges.
Taxes in 2010 and Beyond
When it comes to future taxes, a lot of details remain up in the air. What we do know is that the 2001 Bush tax cuts are set to expire in 2010 and the Obama administration has indicated they want to raise taxes on the rich (those earning more than $250,000) and keep the cuts static for those in the lower paying tax brackets.
- Healthcare: If healthcare reform will indeed pass, those benefits won’t be free. The Obama administration is backing a House bill that creates a 5.4% surtax on income over $500,000 for single filers or $1 million for couples.
- Income Taxes: On the income tax front, Obama and some Democrats are pushing to have the two highest tax brackets revert back to the pre-2001 levels of 36% and 39.6%.
- Capital Gains: If the Obama administration gets its way, capital-gains tax rates would go back to 20% for wealthier individuals and qualified dividends would be taxed as ordinary income up to the top rate of 39.6%.
- Estate Taxes: The House passed a bill earlier this month that makes the 2009 estate tax provisions permanent (i.e., a 45% top marginal rate on estates larger than $3.5 million or $7 million for married couples). If the Senate were not to pass the bill, current law has the estate tax rate reverting to a 55% rate on estates worth more than $1 million after next year.
Given the exploding deficits and weary economy, which is recovering from a severe economic crisis, getting our tax policy situation back in order is critical. Having politicians make tough tax policy decisions runs contrary to their partisan reelection agendas, however our country needs to pluck more feathers from our taxpaying geese to face these monumental economic challenges…even if it requires listening to irritating hissing from our citizens.
Ari Fleischer WSJ Op-Ed From Earlier This Year
Article on Tax Policy Issues for 2010 and Beyond
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients own certain exchange traded funds, but at time of publishing had no direct positions in an security referenced, including UBS. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC “Contact” page.




 Investing Caffeine

