Posts tagged ‘chatgpt’
AI: Will the World Go Dead or Markets Continue to Surge Ahead?
The internet caught fire last month when 27-year-old Jacob Coxon resigned from AI juggernaut Anthropic over safety concerns. After working in pretraining model development for just four months, Coxon resigned from Anthropic and launched a national media tour warning of AI doomsday. But he’s not a solo alarmist: his boss, Anthropic CEO Dario Amodei, has also raised flags about AI safety. To compound matters, Coxon’s former alignment science lead colleague, 28-year-old Evan Hubinger, echoed those fears, publicly stating there is a greater than 10% chance that artificial intelligence could annihilate humanity within the decade.
It’s a chilling thought. Ask a friend, neighbor, coworker, or family member how they feel about data centers, job displacement, energy prices, or existential risk, and you’re bound to get an anxious response. This sentiment has entered the national zeitgeist as evidenced by the Saturday Night Live skit satirizing CEO Amodei last weekend, which can be watched by clicking here.
Yet, while AI dominates the headlines, other macroeconomic variables continue to shape the financial markets, including higher oil prices, shifting Federal Reserve policy, Middle Eastern geopolitical anxiety, and midterm election uncertainty. Investors, however, took a measured view of the noise. Here is how the major indices wrapped up last month:
NASDAQ: +1.9% (up +15.6% for the year)
S&P 500: -0.5% (up +11.8% for the year)
Dow Jones Industrial Average: -4.3% (up +5.9% for the year)
Alarmists and Doomsdayers Come Out in Force
Halloween is still weeks away, but that hasn’t stopped the doomsday prognosticators from trying to spook investors. Having invested for over 35 years, I’ve seen this movie before. Armageddon makes for great Hollywood scripts, but fortunately, it rarely translates to reality.
Nevertheless, a groundswell of fear has been created suggesting AI will trigger a cascade of catastrophes, including:
- Stealing everyone’s job
- Providing bad actors with nuclear weapon recipes
- Sparking massive cyberattacks and critical infrastructure collapses
- Fueling a potential geopolitical war via distributing misinformation
- Spawning AI-engineered pandemics or biological weapons
- Overwhelming the environment, draining resources, and skyrocketing electricity prices due to data center proliferation electricity prices due to data center proliferation
This isn’t the first time a technological leap has been forecasted to end in ruin. Remember the dreaded Y2K panic in 2000? Electrical grids were supposed to crash, ATMs and banks were predicted to go dark, air travel would grind to a halt, and hospital equipment failure would cause mass casualties. What actually happened? A big nothing burger. Life proceeded virtually unscathed.
An End-of-the-World History Lesson
Students of history understand that predictions for human death and extinction are nothing new. Here are a few examples:
 Nostradamus (1555): The renowned French astrologer made 942 predictions in Les Propheties, culminating in a famous, utterly failed prognostication of a world-collapsing catastrophe in 1999.
 Thomas Mathus (1798): The economist predicted that population growth would inevitably outpace food production, triggering permanent, widespread famine and societal collapse. Technology and the Green Revolution ended up proving him wrong.
 William Miller (1844): A 19th-century preacher-influencer with over 100,000 followers, Miller predicted Jesus Christ would return to earth to engulf the world in fire. When his initial date of March 21, 1844 failed and passed, he simply rescheduled it to October 22, 1844, which failed again.
 Paul Ehrlich (1968): In The Population Bomb, Ehrlich incorrectly forecasted that hundreds of millions would starve to death globally throughout the 1970s and 1980s.
 George Wald (1970): In late 1970, a Harvard Nobel laureate declared to a crowd at the University of Rhode Island that civilization would end within 15 to 30 years. Breaking news: we are still here.
 Al Gore (2008): The former Vice President stated on multiple occasions that polar ice caps could completely melt away within five years. That didn’t happen.
 Harold Camping (2011): The doomsday radio preacher predicted the end of the world would occur on May 21, 2011. When that failed, he pushed it to October. He passed away two years later at age 92.
 Jacob Coxon – Anthropic (2026): TBD.
From AI Boomsday to AI Doomsday
While some sit on the precipice of imaginary extinction, reality dictates that the rollout of artificial intelligence is powering an unprecedented industrial and economic revolution. The companies aggressively investing in and embracing AI are reaping the rewards – a point I emphasized in my previous article, The AI Genie is Out of the Bottle.
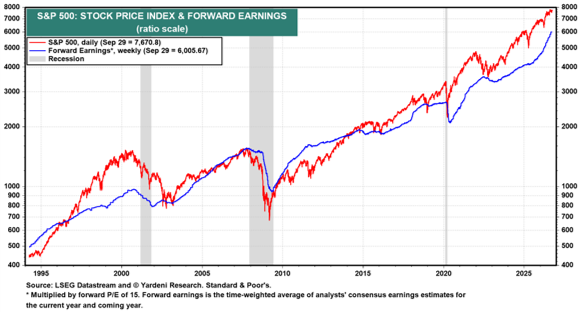
It’s no surprise that the Magnificent 7 (Apple, Amazon, Alphabet-Google, Meta-Facebook, Microsoft, Netflix, and Tesla) – the primary architects pouring hundreds of billions into AI infrastructure – are leading the charge. More specifically, the Magnificent 7 index (MAGS) was up +4.3% last month and +50.9% over the past two years. Is it a coincidence that both the stock market’s Forward Earnings (blue line) and the stock market index (red line) both inflected sharply upward (see below) following OpenAI’s release of ChatGPT bot in November, 2022? I think not.
Source: Yardeni.com
The AI Facts on the Ground While the mainstream media fixates on worst-case theoretical risks, look at the undeniable data driving the sector forward. Altimeter CEO, Brad Gerstner, shared compelling AI charts in a recent presentation:
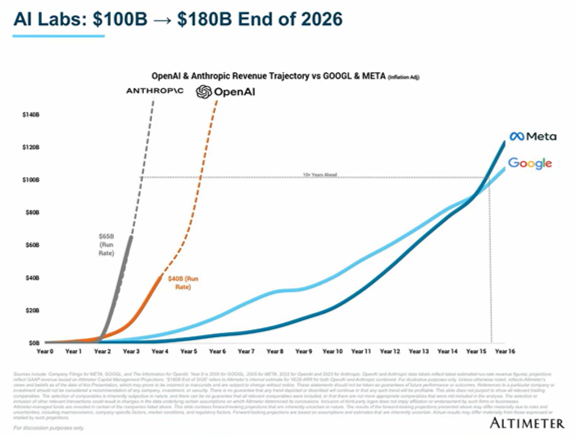
- Unprecedented Revenue Growth: Investors are witnessing the fastest revenue scaling of multiple companies in human history. It took Meta and Google over 15 years to reach $100 billion in revenue; Anthropic and OpenAI are projected to cross that milestone in roughly five years – a decade faster than their predecessors (see chart below).
Source: Altimeter (Brad Gerstner)
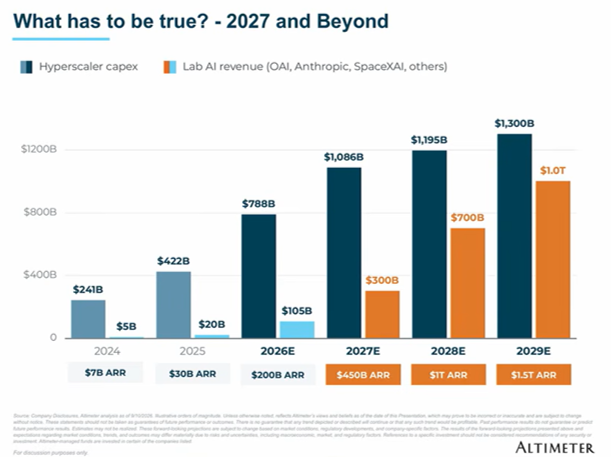
- Robust Enterprise CAPEX: Frontier model labs (OpenAI, Anthropic, SpaceXAI) are channeling customer revenues directly into purchasing or leasing “compute” (processing power, memory, and hardware infrastructure) from hyperscalers (Amazon, Microsoft, Google). Industry forecasts project AI Lab Annual Recurring Revenue (ARR) to reach $1.5 trillion, easily supporting the projected $1 trillion+ in annual CAPEX (Capital Expenditures) through 2029 (see chart below). Reaching $1 trillion in CAPEX is a reasonable projection if you consider worldwide information technology spending is expected to reach $6.4 trillion this year.
Source: Altimeter (Brad Gerstner)
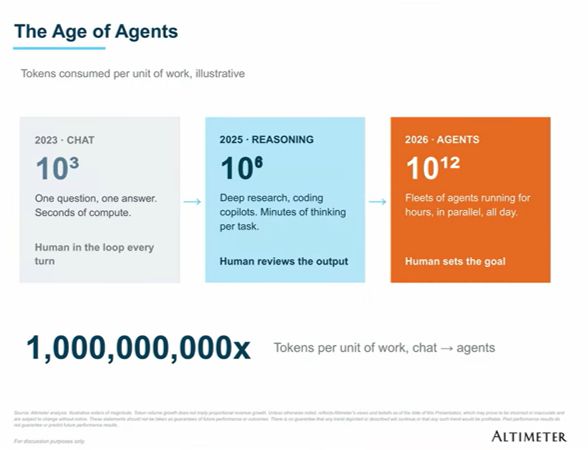
- Exploding Usage: We are still in the first inning of AI adoption, yet usage is skyrocketing as workflows shift from basic chat queries to inference processing and autonomous AI agents. Measured by data unit tokens processed, activity has scaled 1,000,000,000 (one billion-fold) since 2023 (see table below), driving the insatiable need for next-generation data centers.
Source: Altimeter (Brad Gerstner)
Guardrails and Regulation Can Mitigate Risks
While AI adoption surges, business and government are actively collaborating to implement sensible guardrails. Acknowledging legitimate concerns, tech titans and political leaders recently met at a White House AI Summit* to sign safety pacts and discuss regulatory frameworks. Furthermore, existing liability laws can and should hold companies accountable if they negligently release harmful products – just as automakers like Tesla should be held accountable if harmful autonomous vehicle are released. The high-profile anxiety surrounding AI is ultimately a net positive: it has forced tech CEOs to prioritize safety and placed Washington on high alert.
While alarmists continue to capture headlines with tales of extinction dread, financial markets and real-world innovation will continue to surge ahead.
*AI White House Summit attendees included Anthropic CEO Dario Amodei, SpaceX and Tesla CEO Elon Musk, Nvidia CEO Jensen Huang, Meta CEO Mark Zuckerberg, Amazon founder Jeff Bezos, Alphabet CEO Sundar Pichai, Microsoft CEO Satya Nadella, Advanced Micro Devices CEO Lisa Su, Palantir CEO Alex Karp and OpenAI President Greg Brockman.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (October 1, 2026). Subscribe Here to view all monthly articles.
Sidoxia Capital Management (SCM) and some of its clients hold positions in AAPL, AMZN, GOOGL, META, MSFT, TSLA, NVDA, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position NFLX, AMD, PLTR, or in any other security referenced in this article.
DISCLOSURE: No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Each investor’s situation is unique so please work with a professional financial adviser, tax accountant or legal representative, as applicable, to develop an individualized plan or address any questions you may have. Investing involves risk including the possibility of loss of one’s investment.
As We Give Thanks, AI and Mag 7 Take Cash to the Bank

Market volatility resurfaced last month as speculation intensified over whether an AI bubble may be forming—and potentially bursting. Yet despite the jitters, equity markets remain solidly positive for the year (S&P 500 +16.5%, NASDAQ +21.0%, Dow +12.2%) – see S&P 500 chart below. A significant portion of the gains have been powered in large part by ongoing strength in the Magnificent 7. Standouts such as NVIDIA (+31.8%) and Alphabet (+68.1%) have been instrumental in carrying the broader indices higher.

Even with these sizable year-to-date gains, memories of the 2000 Tech Bubble and 2008 Financial Crisis resurfaced and prompted investors to temporarily tap the brakes. Mid-month, the NASDAQ retreated roughly -9% from its October peak. After a month-end bounce, the S&P 500 finished essentially flat (+0.1%), the NASDAQ slipped -1.5%, and the Dow eked out a +0.3% increase.
OpenAI and the $1.4 Trillion Question
At the center of the AI controversy sits OpenAI, parent of the three-year-old technology toddler, ChatGPT (Generative Pre-trained Transformer), which now boasts more than 800 million global users (see chart below). The company reportedly runs at a $20 billion annual revenue pace, yet faces difficult questions about how it intends to fund its staggering $1.4 trillion AI infrastructure commitments.
Those concerns came to a head when tech investor Brad Gerstner pressed CEO Sam Altman on his podcast last month. Instead of answering how OpenAI plans to underwrite such an enormous buildout, Altman childishly shot back defensively:
“If you want to sell your shares, I’ll find you a buyer.” (See clip here — or full interview here)

Source: Digital Information World
OpenAI is a key player, but just one component in the vast—and rapidly expanding—web of global AI infrastructure. Gartner, a global research and advisory firm, forecasts $2 trillion of AI investment in 2026, while NVIDIA CEO Jensen Huang recently said:
“Over the next five years, we’re going to scale into… effectively a $3 to $4 trillion AI infrastructure opportunity.”
These provocative “Is this a bubble?” questions make for great headlines, but to truly evaluate AI sustainability, it’s wise to follow the classic Watergate guidance from of All the President’s Men character, Deep Throat (FBI Associate Director, Mark Felt), who tells journalist Bob Woodward to “follow the money,” if he wants to get to the bottom of the Watergate scandal.
The same principle applies to investors who follow the money – the picture looks very different from past bubbles.
Forget Pets.com—Today’s AI Buildout Is Being Funded by Cash-Rich Titans
Unlike the flimsy, profitless internet startups of the late 1990s—companies that raised billions based on “eyeballs” and cocktail-napkin business plans—the current AI buildout is being financed largely by profitable cash-generating giants.
Yes, some firms like Oracle (ORCL) are leaning on debt financing for data-center expansion. But the overwhelming majority of AI capex is being funded by customers and by the cash flow of the Magnificent 7, a group with the financial firepower to sustain multi-year spending without relying heavily on capital markets.
This dynamic alone separates today’s environment from classic bubble conditions.
Do the Magnificent 7 Really Deserve a $22 Trillion Valuation?
The Mag 7 represent only 1% of S&P 500 constituents yet account for a massive 35% of the index’s market value. That concentration understandably raises eyebrows, evoking historical parallels to the “Nifty Fifty” of the 1970s or the “Four Horsemen” of the 1990s.
But headline concentration can be misleading—because the fundamentals tell a very different story. Here are some of the major disparities:
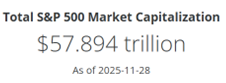
1.) Mag 7 Share of Profits Matches Their Share of Market Value: The Mag 7 collectively contribute $22 trillion of the S&P 500’s $58 trillion total value (below). Said differently, the market values and weightings of the Mag 7 equate to about $22 trillion and 37% of the S&P 500, respectively:
· Nvidia Corp: $4.3T & 7.0%
· Apple Inc.: $4.1 T & 6.7%
· Alphabet Inc.: $3.9 T & 6.3%
· Microsoft Corp.: $3.7 T & 5.9%
· Amazon.com Inc.: $2.5 T & 4.0%
· Meta Platforms Inc.: $1.6T & 2.6%
· Tesla Inc.: $1.4T & 2.3%
· TOTAL: $22T / 37%
Source: Slickcharts
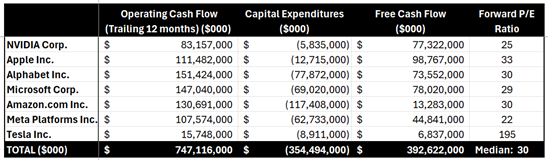
Conveniently (and importantly), the Mag 7’s roughly $747 billion in annual cash flow (see table below) is a good proxy for their profit contribution to the $2 trillion in S&P profits.
Source: SEC Filings & MarketSurge
The $747 billion in Mag 7 cash flows divided by the $2 trillion in S&P 500 coincidentally also equates to 37% ($747B/$2T).
These calculations of the Mag 7 are not bubble math—these calculation comparisons are rational math. Arguments could be made that Mag 7 market values are actually undervalued (not in bubble territory) and should appreciate to a higher percentage of the S&P 500 weightings because these 7 stocks are growing sales and profits faster than compared to the other “absentee” 493 stocks in the index.
2.) Mag 7 are Swimming in Cash: That $747 billion in annual cash flow is on track to hit a jaw-dropping $1 trillion, giving these firms ample capital to fund AI buildouts without substantially accessing the equity or credit markets. The ability to self-fund a multi-trillion-dollar infrastructure expansion is the opposite of bubble behavior.
3.) Valuations Are Elevated—but Far from Bubble Territory: During the 2000 Tech Bubble, many leading tech names traded at 100x+ earnings (See also: Rational or Irrational Exuberance. Today, the Mag 7 trade at a median forward P/E around 30x. Expensive? Historically, yes, versus long-term averages, but nowhere near historical extremes. Relative to growth, profitability, and cash flow, valuations are far more grounded today than during prior manias.
The bottom line is there is plenty to be thankful for and bubble fears are overstated. Despite pockets of AI froth, the underlying economic engine powering AI adoption is real, profitable, and well-capitalized. When investors follow the money, they discover:
· The Mag 7 generate over one-third of S&P 500 profits
· They generate and hold hundreds of billions in cash
· They largely fund their own AI capital expenditures
· Valuations remain far below bubble-era extremes
Investors have a lot to be thankful for. And while volatility will likely continue, the ingredients for a classic, catastrophic AI bubble are noticeably absent. For disciplined, long-term investing strategies like those employed at Sidoxia Capital Management, this environment still offers abundant opportunity—without the need to fear a pricked AI balloon anytime soon.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (Dec. 1, 2025). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in NVDA, AAPL, MSFT, GOOGL, AMZN, META, TSLA, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position in ORCL or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.
A.I. Field of Dreams

In the 1989 Academy Award–nominated film Field of Dreams, the lead character Ray Kinsella (played by Kevin Costner) hears a mysterious voice whisper, “If you build it, he will come.” Acting on blind faith, Ray builds a baseball diamond in the middle of his Iowa cornfield, risking financial ruin. Against all logic, the field draws a flood of visitors.
Today, a similar “field of dreams” is being built—not with corn, but with data centers. Instead of baseball players, it is artificial intelligence (AI) models, applications, and users who are coming.
The Market’s AI Momentum
The AI boom has already reshaped markets with all three benchmarks hitting record highs. Last month, the S&P 500 climbed +1.9%, while the NASDAQ rose +1.6% and Dow Jones Industrial Average surged +3.2%. Year to date, the indexes are up +10%, +11%, and +7%, respectively.
Behind this surge lies an unprecedented wave of AI infrastructure investment. Hyperscalers—Amazon.com (AMZN), Microsoft Corp. (MSFT), Google-Alphabet (GOOGL), Meta Platforms (META), and others—are pouring hundreds of billions into AI, much of it flowing directly to NVIDIA Corp. (NVDA), the undisputed leader in GPUs (Graphic Processing Units) powering the world’s AI engines. How large is the spending? NVIDIA CEO Jensen Huang estimates $3 trillion to $4 trillion will be spent this decade to fuel the AI revolution.

Source: Visual Capitalist
The Scale of AI’s Buildout
To put this into perspective:
- Amazon is projected to spend over $100 billion in 2025 alone, more than its cumulative capital expenditures from 2000–2020 combined.
Meta is constructing its $10 billion+ Hyperion data center in Louisiana—a sprawling 4 million sq. ft. complex across 2,250 acres, powered by a $4 billion natural gas plant. The footprint is so gargantuan it could cover much of Manhattan (see graphic below).

- xAI’s Colossus, a 750,000 sq. ft. data center in Memphis, Tennessee was completed in just 122 days—equivalent to building 418 homes in half the time it normally takes to construct one house (see slide below).

Source: BOND (Global Technology Investment Firm)
This breakneck pace of spending underscores the urgency and competitive pressure driving the global AI arms race.
The Origin of the AI Floodgates Opening

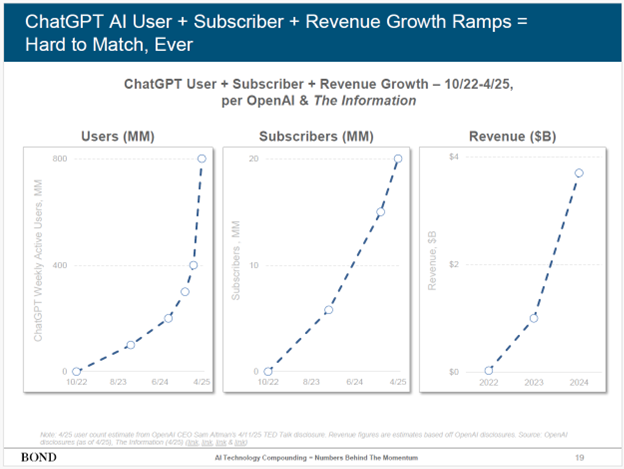
The spark was lit on November 30, 2022, when OpenAI released its LLM (large language model) called ChatGPT. Within two months, it amassed 100 million users.
Today, ChatGPT’s metrics have blasted much higher (see slide below):
- 800 million weekly active users
- 20 million paid subscribers
- $3.7 billion in revenue (as of April 2025)
Source: BOND (Global Technology Investment Firm)
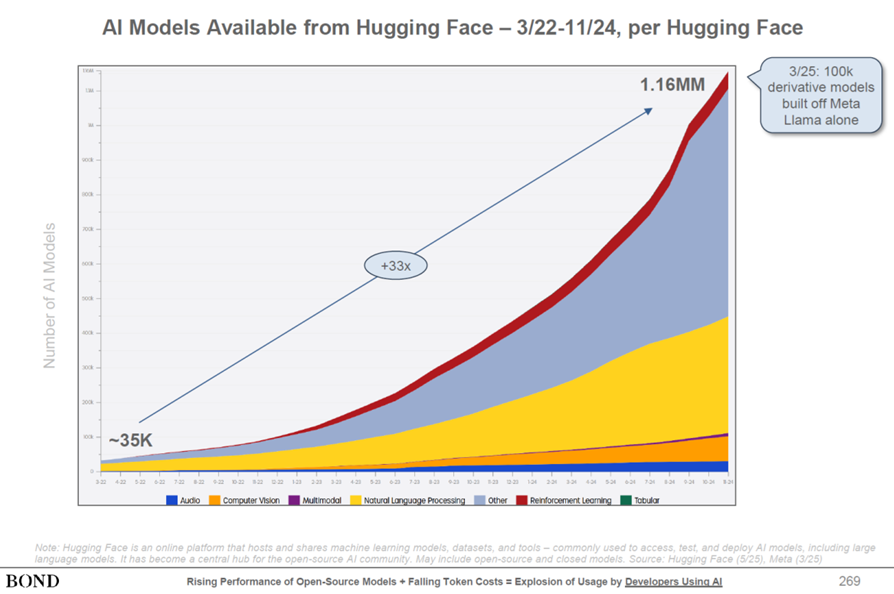
But OpenAI is far from alone. Google (Gemini), xAI (Grok), Anthropic (Claude), Meta (LLaMA), Amazon (Titan), Perplexity, and DeepSeek are all competing with their own LLMs. In total, over 1 million machine learning models now exist (see slide below) — each requiring costly compute power and pricey data centers.
Source: BOND (Global Technology Investment Firm)
Bubble or Productivity Breakthrough?
With trillions flowing into AI, a natural question arises: Is this a bubble?
Even OpenAI CEO Sam Altman admits we’re in an AI bubble :
“When bubbles happen, smart people get overexcited about a kernel of truth…Someone is going to lose a phenomenal amount of money… and a lot of people are going to make a phenomenal amount of money.”
Both realities can be true:
- Yes, hyperscalers are spending like “drunken sailors.”
- Yes, AI demand and productivity benefits are real and growing exponentially.
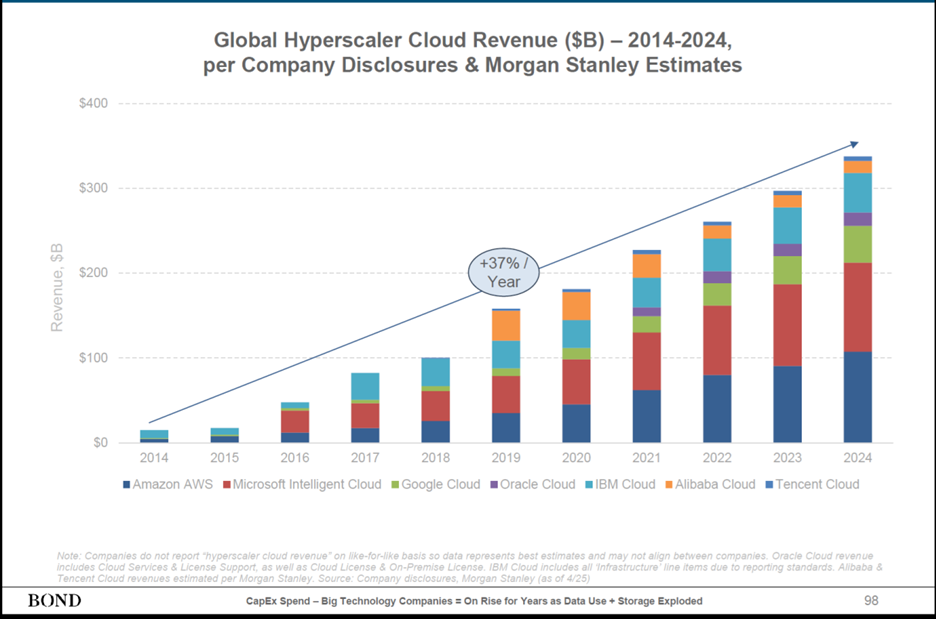
Consider the trajectory of global cloud revenues: from nearly $0 a decade ago to $300 billion today—a +37% CAGR (see chart below).
Source: BOND (Global Technology Investment Firm)
And the primary reason for cloud growth can be attributed to AI productivity benefits. A recent SAP survey found that workers using AI save nearly one hour per day on average. That’s transformative for companies: higher productivity without needing proportional hiring.
AI Use Cases Expanding Aggressively
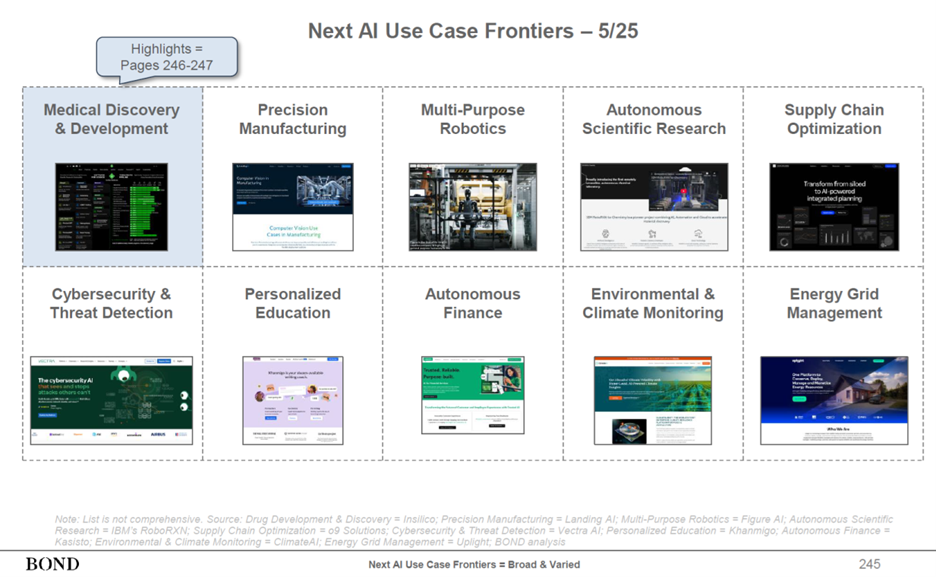
AI’s applications now span nearly every sector (see slide below):
- Technology – software engineering, code generation
- Customer Service & Marketing – customer support and call centers
- Transportation – autonomous vehicles and logistics
- Healthcare – drug discovery and development
- Supply Chains – precision manufacturing and optimization
- Automation – multi-purpose robotics
- Cybersecurity – threat detection and prevention
- Education – personalized lessons and curriculums
- Energy – grid optimization and demand forecasting
Source: BOND (Global Technology Investment Firm)
The New Field of Dreams
Throughout history, every great leap—printing press, steam engine, electricity, internet—has required massive upfront investment before the payoff arrived. AI is following the same path. Today, we are in the midst of building a new AI Field of Dreams. However, now, the data centers are the new baseball fields. And as with Ray Kinsella’s diamond, the masses are indeed coming.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (August 1, 2025). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in GOOGL, META, AMZN, MSFT, NVDA, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position in SAP or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.
Another Hot Month, Another Fresh Record

Summer is coming to a close, but the weather is not the only thing that remains hot. The stock market has been scorching hot as well. Both the S&P 500 and Dow Jones Industrial Average blazed to all-time record highs last month. In fact, both of these indexes have risen seven out of eight months this year, including gains in the last four consecutive months. More specifically, the S&P 500 was up +2.8% last month and +18.4% this year, while the Dow Jones has advanced +1.8% for the month and +10.3% for the year.
How can this surging bull market be in existence while undergoing a war between Russia and Ukraine; military conflict in Gaza; a nasty Japanese Yen Carry Trade unwind; a highly divisive upcoming presidential election; a weakening economy; and rising unemployment (see chart below)?

Source: Calafia Beach Pundit
For all investors and traders, there is never a shortage of issues to worry about, even when times are good. However, despite the long laundry list of concerns, there are plenty of opposing tailwinds supporting the upswell in stock prices, starting with growing record corporate profits with strength forecasted through 2026 (see chart below).

Source: Yardeni.com (Yardeni Research)
Another factor underpinning the strength of stocks has been the decline in the inflation rate. The latest headline inflation rate (CPI – Consumer Price Index) fell to 2.9% in July, and if you exclude shelter costs, inflation has fallen below the Federal Reserve’s 2% target rate.

Source: Calafia Beach Pundit
Conversely, the story was quite different in 2022 when the Federal Reserve began its crusade against out-of-control inflation (see chart below) by starting its first of 11 interest rate hikes that spanned from January 2022 through July of 2023. The net result was a stock market that tanked -19% in 2022. More recently, the Fed has clearly signaled that inflation is more under control with traders predicting a 100% probability of a -0.25% or -0.50% cut in the targeted Federal Funds interest rate on September 18th. The Federal Reserve Chairman Jerome Powell gave a dovish speech at the annual policy meeting in Jackson Hole, Wyoming strongly portending September action – the first cut in four years since the pandemic.

AI Arms Race on Spending
Another dynamic contributing to new stock market record highs is the boom in AI (Artificial Intelligence) spending by the technology behemoths like Amazon.com Inc. (AMZN), Microsoft Corporation (MSFT), Meta Platforms Inc. (META), and Google – Alphabet Inc. (GOOGL). As I have been talking and writing about for some time (see World of AI), there is an arms race in spending to create the next, latest-greatest large language model (LLM) like ChatGPT. The goal is to bring more efficiency and accuracy to businesses and provide consumers more pleasure and time savings at both work and home. As you can see from the chart below, the four colossal technology companies previously mentioned are currently on a run-rate of spending more than a mind-boggling $200 billion annually, much of that going to the king of AI GPU (Graphics Processing Unit) manufacturing, NVIDIA Corporation (NVDA).
Why are companies spending so much on AI? Because they agree with NVIDIA CEO, Jensen Huang, who last week stated, “Generative AI will revolutionize every industry.” Despite all the spoils migrating to NVIDIA, traders were still looking for warts on the AI supermodel when they reported 2nd quarter results last week. Nonetheless, NVIDIA still delivered its 5th consecutive quarter of greater than 100% revenue growth, while generating revenues of almost $100 billion over the last 12 months – not too shabby. Although greedy investors wanted more, the stock was still up +2% for the month and +141% so far this year.

Source: Sherwood News
While economic, political and geopolitical concerns have been boiling over around the world, the stock market continues to sizzle higher. Declining inflation and interest rates, escalating business profits, and spiking artificial intelligence expenditures across corporate America have kept stocks cooking to record highs. It’s been a sweltering summer but not yet too hot for investors to get roasted out of the stock market kitchen.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (September 3, 2024). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in individual stocks , certain exchange traded funds (ETFs), including AMZN, MSFT, META, GOOGL, NVDA, but at the time of publishing had no direct position in any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.
AI Revolution and Debt Ceiling Resolution

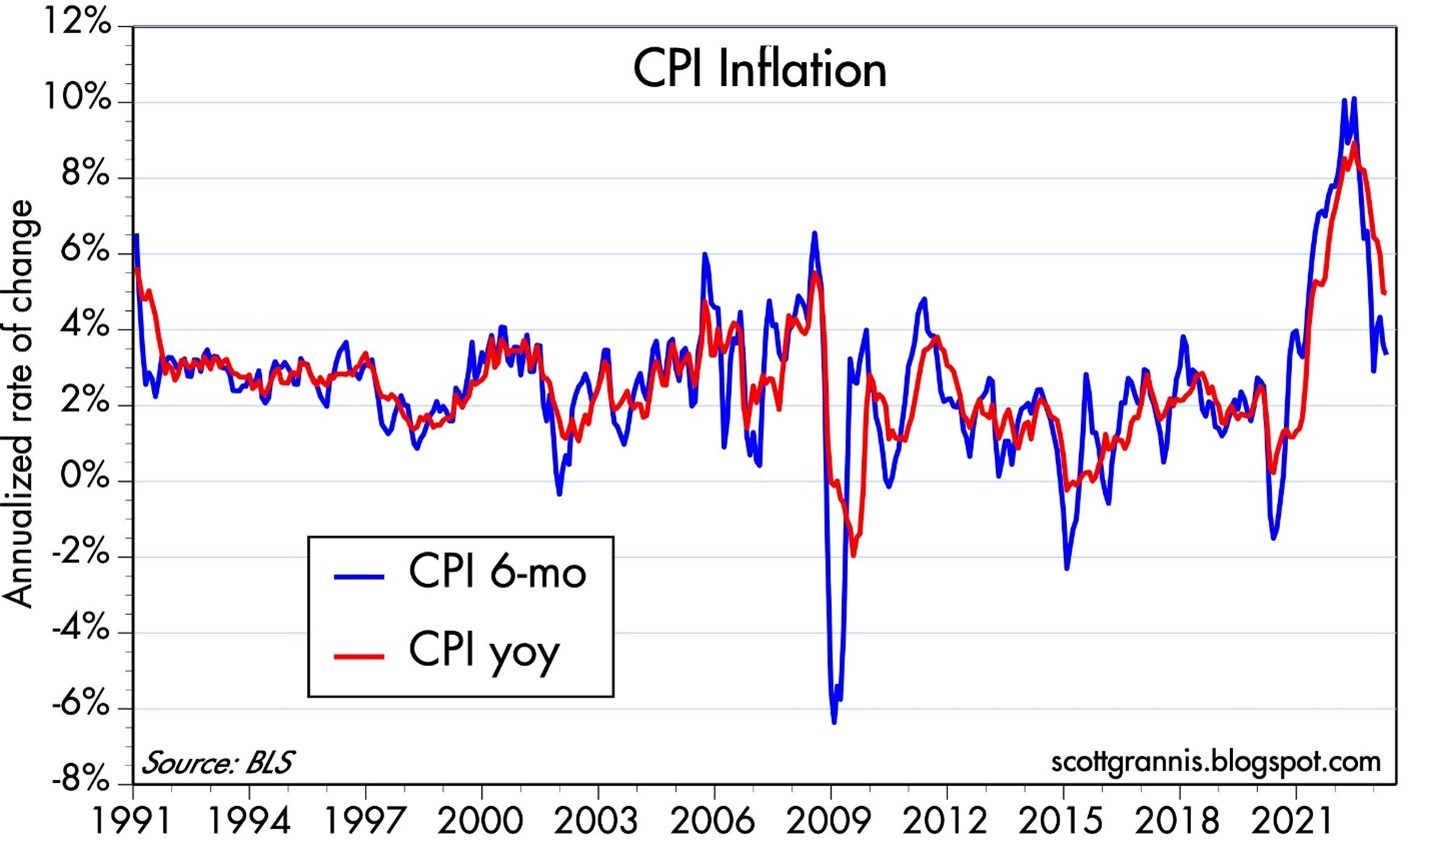
On the surface, last month’s performance of the stock market as measured by the S&P 500 index (+0.3%) seemed encouraging, but rather pedestrian. Fears of sticky-high inflation, more potential Federal Reserve interest rate hikes, contagion uncertainty surrounding a mini-banking crisis, along with looming recession concerns led to a -3.5% monthly decline in the Dow Jones Industrial Average (-1,190 points). The good news is that inflation is declining (see chart below) and currently the Federal Reserve is expected to pause from increasing interest rates in June (the first time in more than a year).
Source: Calafia Beach Pundit
Overall stock market performance has been a mixed-bag at best. Adding to investor anxiety, if you haven’t been living off-the-grid in a cave, is the debt ceiling negotiations. Essentially, our government has maxed out its credit card spending limit, but Republicans and Democrats have agreed in principle on a resolution for an expanded credit line. More specifically, the House of Representatives just approved to raise the debt ceiling by a resounding margin of 314 – 117. If all goes well, after months of saber rattling and brinksmanship, the bill should be finalized by the Senate and signed by the President over the next two days.
Beyond the Washington bickering, and under the surface, an artificial intelligence (AI) revolution has been gaining momentum and contributed to the technology-heavy NASDAQ catapulting +5.8% for the month and +23.6% for 2023. At the center of this disruptive and transformational AI movement is NVIDIA Corp., a leading Silicon Valley chip manufacturer of computationally-intensive GPUs (graphics processing units), which are used in generative AI models such as OpenAI’s ChatGPT (see NVIDIA products below). Adoption and conversations surrounding NVIDIA’s AI technology have been spreading like wildfire across almost every American industry, resulting in NVIDIA’s stratospheric stock performance (+36% for the month, +159% for the year, +326% on a 3-year basis).

Source: NVIDIA Corp. – the computing engines behind the AI revolution.
Why Such the Fuss Over AI?
Some pundits are comparing AI proliferation to the Industrial Revolution – on par with productivity-enhancing advancements like the steam engine, electricity, personal computers, and the internet. The appetite for this new technology is ravenous because AI is transforming a large swath of industries with its ability to enhance employee efficiency. By leveraging machine learning algorithms and massive amounts of data, generative AI enables businesses to automate repetitive tasks, streamline processes, and unlock new levels of productivity. A study released by MIT researchers a few months ago showed that workers were 37% more efficient using ChatGPT.
If you have created an account and played around with ChatGPT at all you can quickly realize there are an endless number of potential applications and use-cases across virtually all industries and job functions. Already, application of generative AI systems is disrupting e-commerce, marketing, customer service, healthcare, robotics, computer vision, autonomous vehicles, and yes, even accounting. Believe it or not, ChatGPT recently passed the CPA exam! Maybe ChatGPT will do my taxes next year?
Other industries are quickly being disrupted too. Lawyers may feel increased pressure when contracts or briefs can be created with a click of the button. Schools and teachers are banning ChatGPT too in hopes of not creating lazy students who place cheating and plagiarism over critical thinking.
At one end of the spectrum, some doomsday-ers believe AI will become smarter than humans, replace everyone’s job, and AI robots will take over the world (see Elon Musk warns AI could cause “civilization destruction”). At the other end of the spectrum, others see AI as a transformational tool to help worker productivity. As generative AI continues to advance, its impact on employee efficiency will only grow, optimizing processes, driving innovation, and reshaping industries for a more productive future. Embracing this transformative technology will be critical for businesses seeking to thrive in the new digital age.
2023 Stock Performance Explained – Index Up but Most Stocks Down
Although 2022 was a rough year for the stock market (i.e., S&P 500 down -19%), stock prices have rebounded by +20% from the October 2022 lows, and +9% this year. This surge can be in large part attributed to the lopsided performance of the top 1% of stocks in the S&P 500 index (Apple Inc., Microsoft Corp., Amazon.com Inc., NVIDIA Corp., and Alphabet-Google), which combined account for almost 25% of the index’s total value. These top 5 consumer and enterprise technology companies have appreciated on average by an astounding +60% in the first five months of the year and represent a whopping $9 trillion in value. It gets a little technical, but it’s worth noting these larger companies have a disproportionate impact on the calculation of the return percentages, and vice versa for the smaller companies. To put these numbers in context, Apple’s $2.8 trillion company value is greater than the Gross Domestic Product (GDP) of many entire countries, including Italy, Canada, Australia, South Korea, Brazil, and Russia.
On the other hand, if we contrast the other 99% of the S&P 500 index (495 companies), these stocks are down -1% each on average for 2023 (vs +60% for the top 5 mega-stocks). If you look at the performance summary below, you can see that basically every other segment of the stock market outside of technology (e.g., small-cap, value, mid-cap, industrial) is down for the year.
2023 Year-To-Date Performance (%)
S&P 500: +8.9%
S&P 500 (Equal-Weight): -1.2%
S&P Small-Cap Index: -2.3%
Russell 1000 Value Index: -2.0%
S&P Mid-Cap Index: -0.7%
Dow Jones Industrial: -0.7%
While most stocks have dramatically underperformed technology stocks this year, this phenomenon can be explained in a few ways. First of all, smaller companies are more cyclically sensitive to an economic slowdown, and do not have the ability to cut costs to the same extent as the behemoth companies. The majority of stocks have factored in a slowdown (or mild recession) and this is why valuations for small-cap and mid-cap stocks are near multi-decade lows (12.8x and 13.0x, respectively) – see chart below.

Source: Yardeni.com
The stock market pessimists have been calling for a recession for going on two years now. Not only has the recession date continually gotten delayed, but the severity has also been reduced as corporate profits remain remarkably resilient in the face of numerous economic headwinds. Regardless, investors can stand on firmer ground now knowing we are upon the cusp of an AI revolution and near the finish line of a debt ceiling resolution.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (June 1, 2023). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in NVDA, AAPL, MSFT, GOOGL, AMZN and certain exchange traded funds (ETFs), but at the time of publishing had no direct position in any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.




