Posts filed under ‘Fixed Income (Bonds)’
AI Gold Rush: Digging for Gold or Digging a Grave?
Grab your hard hats, pickaxes, and shovels. The artificial intelligence (AI) gold rush has attracted everyone from Silicon Valley prospectors to Wall Street treasure hunters. Hundreds of billions of dollars are being buried beneath concrete data centers, power plants, semiconductor factories, and cooling equipment. The million-dollar or trillion-dollar question: Are we digging for gold or digging our own financial grave?
October’s final trading days provided a reminder that even gold rushes can have cave-ins. Investors began questioning the economics of AI megaprojects, while election jitters, higher-for-longer interest rates, and a spectacular cryptocurrency heist added to the Halloween fright-fest. Here is how the major stock market indexes performed in October:
Dow Jones Industrial Average: +1.7% (+7.7% YTD)
S&P 500: -0.9% (+10.7% YTD)
Nasdaq Composite: -5.3% (+9.4% YTD)
The Nasdaq’s bruising month, which was capped by a -2.9% plunge on the last trading day of the month, contrasted with the Dow’s positive finish. The market didn’t suddenly abandon AI; it started demanding clearer ROI (return-on-investment) proof for the spending.
There’s Gold in Them Thar Data Centers
Consider the mind-boggling scale. Gartner forecasts $2.67 trillion of worldwide AI spending in 2026 and $3.64 trillion in 2027 , including infrastructure, software, services, and other categories. Separately, Gartner estimates nearly $1 trillion of AI infrastructure investment in 2026, plus another $6 trillion from 2027 through 2030. That’s enough capital to make even the California Gold Rush look more like a backyard lemonade stand.
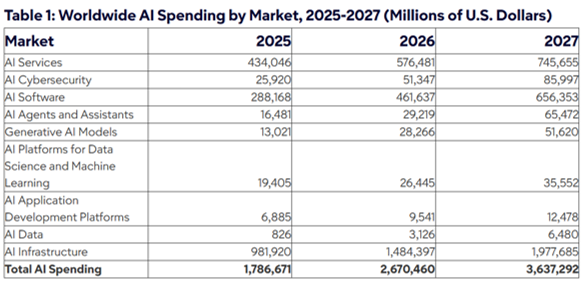
Source: Gartner
Unlike nineteenth-century prospectors, today’s miners aren’t searching for shiny rocks. They’re building the digital plumbing for applications ranging from drug discovery and manufacturing to customer service and autonomous software agents. Yet not every shovel seller, data center landlord, or GPU owner will strike it rich.
The Credit Canary Starts Chirping
The latest sell-off exposed a genuine concern: Can the AI boom earn an attractive return on the enormous capital needed to finance it? Alphabet expects roughly $195 billion – $205 billion of 2026 capital spending, while Amazon projects approximately $220 billion . Alphabet’s advertising revenue missed expectations and cash flow disappointed, raising questions about whether today’s expenditures will translate into tomorrow’s profits.
Here’s the irony: the cloud engines themselves have hardly sputtered. Google Cloud revenue soared +103% year over year, Amazon Web Services accelerated +39%, and Microsoft’s Azure advanced +48%. Microsoft’s cloud business also accelerated, helping distinguish it from worries about softness in portions of Alphabet’s and Amazon’s broader operations. The problem isn’t a lack of growth – it’s whether growth can outrun the cost of buying it.
Credit default swaps (CDS) are an insurance-like way of pricing corporate default risk. When spreads widen, investors demand greater compensation for potential losses. The accompanying chart shows investment-grade spreads around 64 basis points and high-yield spreads around 360, with renewed late-month nervousness. This is a warning light, not yet a five-alarm credit fire. Gartner nevertheless cautions that trillions of dollars of AI infrastructure spending could face future impairment if revenues fail to justify capital costs
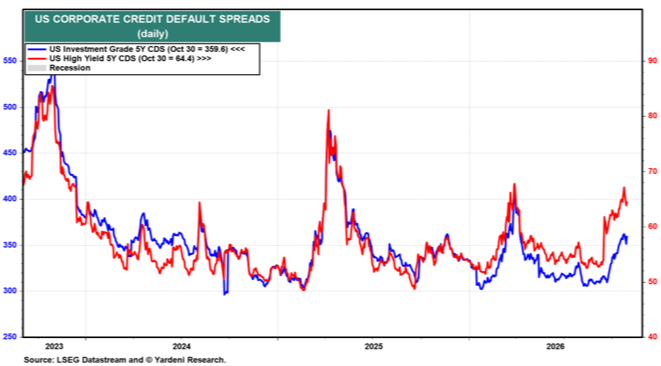
Source: Yardeni.com
The Economy Refuses to Read the Obituary
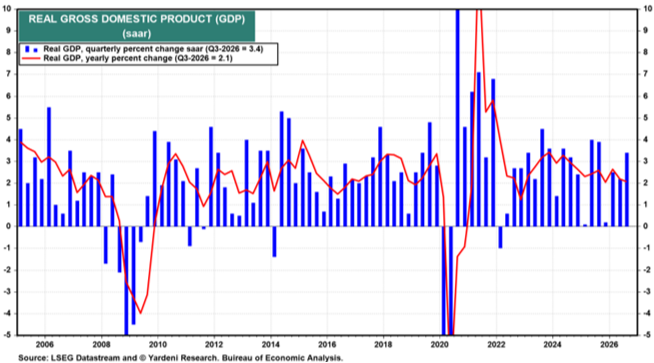
Meanwhile, the real economy continues to deliver surprisingly healthy results. Third-quarter gross domestic product expanded at a 3.4% annualized pace, accelerating from 2.2% in Q2. That’s not a recessionary-looking number, no matter how loudly the doomsdayers bang their drums.
Source: Yardeni.com
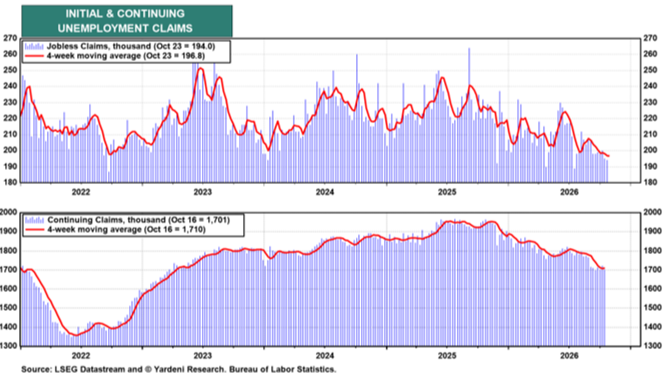
The labor market also looks remarkably resilient. New unemployment claims totaled just 194,000 in late October (see below), near the 189,000 July reading – the lowest level since 1969. Continuing claims eased to roughly 1.7 million. Hiring has slowed, but employers still appear reluctant to fire workers en masse. Call it a “low-hire, low-fire” expansion.
Source: Yardeni.com
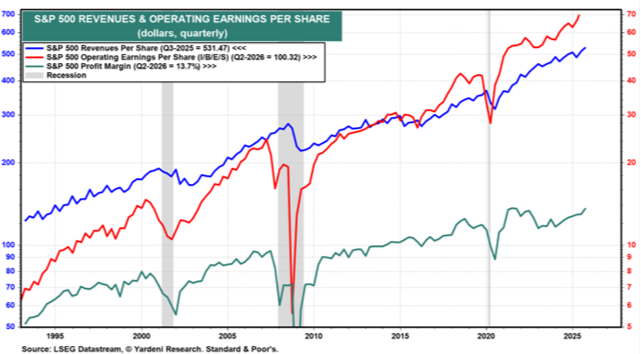
Corporate America is contributing another dose of optimism. S&P 500 revenues and operating earnings have climbed to new highs, while the chart below shows operating profit margins near 13.7%. FactSet likewise projects a 14.9% third-quarter net margin, near historical highs. AI-assisted productivity may be helping some businesses, although strong margins cannot all be credited to robots and algorithms.
Source: Yardeni.com
Rates, Inflation, and the Political Circus
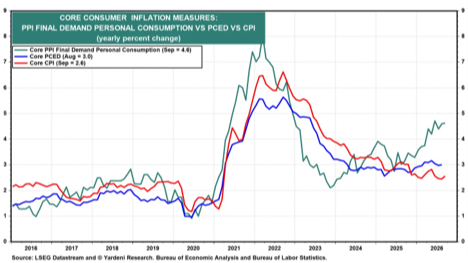
Inflation hasn’t vanished. September’s headline Consumer Price Index rose 3.7% (core CPE 3.1%) from a year earlier, while core CPI ran at 2.6% (see chart below) – well below the peak inflation scare of 2022 but still an uncomfortable distance from the Federal Reserve’s 2% objective. International government bond yields have moved materially higher over the past several years, even though several retreated during October’s flight to safety.
Source: Yardeni.com
At its October meeting, the Fed left its benchmark rate unchanged at 3.75% – 4.00% after September’s hike. Another quarter-point increase in December is widely anticipated, though not guaranteed. Higher borrowing costs raise the hurdle for every prospective AI project, especially those relying on debt rather than internally generated cash flow.
Add November 3rd’s midterm elections to the anxiety cocktail. A possible change in congressional control could complicate legislation, tax policy, oversight, and data-center permitting. Markets dislike uncertainty, but political gridlock is not necessarily a bad thing because controversial legislation gets jammed in the Congressional queue.
A $2 Trillion Dream and a $6 Billion Nightmare
For a measure of AI enthusiasm, consider Anthropic’s pending IPO (Initial Public Offering). Investors once discussed a possible $2 trillion valuation for its anticipated IPO, although Reuters reported in October that some had dialed expectations toward $1.5 trillion. Those numbers speak volumes about the excitement and risk surrounding frontier AI models.
Meanwhile, cryptocurrency investors got a different kind of October surprise: hackers stole approximately $6.3 billion from Binance, according to Reuters. The incident is a sobering reminder that new technology creates opportunities for criminals as well as entrepreneurs.
Keep Digging – But Bring a Map
Will some AI investments become expensive holes in the ground? Absolutely. History’s railroads, internet networks, and telecom booms produced both spectacular winners and bankruptcies. But their excesses also left behind infrastructure that transformed the economy.
Today’s difference is that much of the spending is backed by exceptionally profitable companies, while GDP, employment, and corporate earnings remain sturdy. The prudent response isn’t to throw every pickaxe into the river – or blindly buy every glittering nugget. Diversify across AI beneficiaries, avoid political portfolio bias, rebalance your portfolio, and remember that innovation compounds over years, not daily trading sessions.
The AI gold rush may bury a few reckless prospectors. For patient, disciplined investors, I still believe there’s plenty of gold left in those hills.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (November 1, 2026). Subscribe Here to view all monthly articles.
Sidoxia Capital Management (SCM) and some of its clients hold positions in AMZN, GOOGL, MSFT, NVDA, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position ANT or in any other security referenced in this article.
DISCLOSURE: No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Each investor’s situation is unique so please work with a professional financial adviser, tax accountant or legal representative, as applicable, to develop an individualized plan or address any questions you may have. Investing involves risk including the possibility of loss of one’s investment.
AI: Will the World Go Dead or Markets Continue to Surge Ahead?
The internet caught fire last month when 27-year-old Jacob Coxon resigned from AI juggernaut Anthropic over safety concerns. After working in pretraining model development for just four months, Coxon quit and launched a national media tour warning of AI doomsday. But he’s not a solo alarmist: his boss, Anthropic CEO Dario Amodei, has also raised flags about AI safety. To compound matters, Coxon’s former alignment science lead colleague, 28-year-old Evan Hubinger, echoed those fears, publicly stating there is a greater than 10% chance that artificial intelligence could annihilate humanity within the decade.
It’s a chilling thought. Ask a friend, neighbor, coworker, or family member how they feel about data centers, job displacement, energy prices, or existential risk, and you’re bound to get an anxious response. This sentiment has entered the national zeitgeist as evidenced by the Saturday Night Live skit satirizing CEO Amodei last weekend, which can be watched by clicking here.
Yet, while AI dominates the headlines, other macroeconomic variables continue to shape the financial markets, including higher oil prices, shifting Federal Reserve policy, Middle Eastern geopolitical anxiety, and midterm election uncertainty. Investors, however, took a measured view of the noise. Here is how the major indices wrapped up last month:
NASDAQ: +1.9% (up +15.6% for the year)
S&P 500: -0.5% (up +11.8% for the year)
Dow Jones Industrial Average: -4.3% (up +5.9% for the year)
Alarmists and Doomsdayers Come Out in Force
Halloween is still weeks away, but that hasn’t stopped the doomsday prognosticators from trying to spook investors. Having invested for over 35 years, I’ve seen this movie before. Armageddon makes for great Hollywood scripts, but fortunately, it rarely translates to reality.
Nevertheless, a groundswell of fear has been created suggesting AI will trigger a cascade of catastrophes, including:
- Stealing everyone’s job
- Providing bad actors with nuclear weapon recipes
- Sparking massive cyberattacks and critical infrastructure collapses
- Fueling a potential geopolitical war via distributing misinformation
- Spawning AI-engineered pandemics or biological weapons
- Overwhelming the environment, draining resources, and skyrocketing electricity prices due to data center proliferation electricity prices due to data center proliferation
This isn’t the first time a technological leap has been forecasted to end in ruin. Remember the dreaded Y2K panic in 2000? Electrical grids were supposed to crash, ATMs and banks were predicted to go dark, air travel would grind to a halt, and hospital equipment failure would cause mass casualties. What actually happened? A big nothing burger. Life proceeded virtually unscathed.
An End-of-the-World History Lesson
Students of history understand that predictions for human death and extinction are nothing new. Here are a few examples:
 Nostradamus (1555): The renowned French astrologer made 942 predictions in Les Propheties, culminating in a famous, utterly failed prognostication of a world-collapsing catastrophe in 1999.
 Thomas Mathus (1798): The economist predicted that population growth would inevitably outpace food production, triggering permanent, widespread famine and societal collapse. Technology and the Green Revolution ended up proving him wrong.
 William Miller (1844): A 19th-century preacher-influencer with over 100,000 followers, Miller predicted Jesus Christ would return to earth to engulf the world in fire. When his initial date of March 21, 1844 failed and passed, he simply rescheduled it to October 22, 1844, which failed again.
 Paul Ehrlich (1968): In The Population Bomb, Ehrlich incorrectly forecasted that hundreds of millions would starve to death globally throughout the 1970s and 1980s.
 George Wald (1970): In late 1970, a Harvard Nobel laureate declared to a crowd at the University of Rhode Island that civilization would end within 15 to 30 years. Breaking news: we are still here.
 Al Gore (2008): The former Vice President stated on multiple occasions that polar ice caps could completely melt away within five years. That didn’t happen.
 Harold Camping (2011): The doomsday radio preacher predicted the end of the world would occur on May 21, 2011. When that failed, he pushed it to October. He passed away two years later at age 92.
 Jacob Coxon – Anthropic (2026): TBD.
From AI Boomsday to AI Doomsday
While some sit on the precipice of imaginary extinction, reality dictates that the rollout of artificial intelligence is powering an unprecedented industrial and economic revolution. The companies aggressively investing in and embracing AI are reaping the rewards – a point I emphasized in my previous article, The AI Genie is Out of the Bottle.
It’s no surprise that the Magnificent 7 (Apple, Amazon, Alphabet-Google, Meta-Facebook, Microsoft, Netflix, and Tesla) – the primary architects pouring hundreds of billions into AI infrastructure – are leading the charge. More specifically, the Magnificent 7 index (MAGS) was up +4.3% last month and +50.9% over the past two years. Is it a coincidence that both the stock market’s Forward Earnings (blue line) and the stock market index (red line) both inflected sharply upward (see below) following OpenAI’s release of ChatGPT bot in November, 2022? I think not.
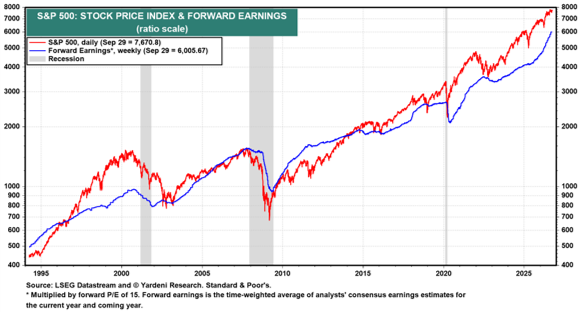
Source: Yardeni.com
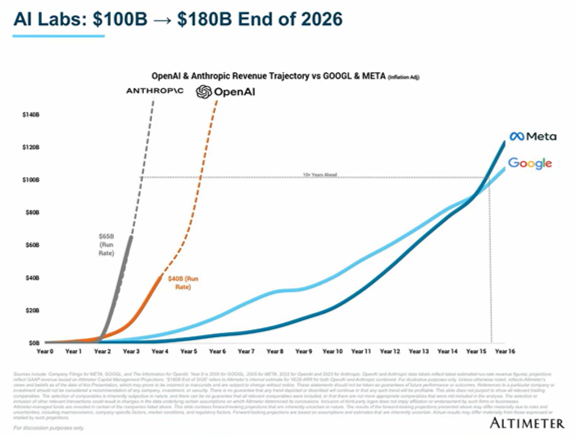
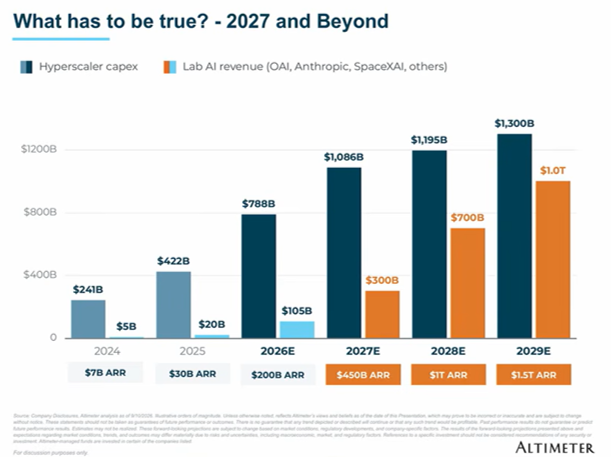
The AI Facts on the Ground While the mainstream media fixates on worst-case theoretical risks, look at the undeniable data driving the sector forward. Altimeter CEO, Brad Gerstner, shared compelling AI charts in a recent presentation:
- Unprecedented Revenue Growth: Investors are witnessing the fastest revenue scaling of multiple companies in human history. It took Meta and Google over 15 years to reach $100 billion in revenue; Anthropic and OpenAI are projected to cross that milestone in roughly five years – a decade faster than their predecessors (see chart below).
Source: Altimeter (Brad Gerstner)
- Robust Enterprise CAPEX: Frontier model labs (OpenAI, Anthropic, SpaceXAI) are channeling customer revenues directly into purchasing or leasing “compute” (processing power, memory, and hardware infrastructure) from hyperscalers (Amazon, Microsoft, Google). Industry forecasts project AI Lab Annual Recurring Revenue (ARR) to reach $1.5 trillion, easily supporting the projected $1 trillion+ in annual CAPEX (Capital Expenditures) through 2029 (see chart below). Reaching $1 trillion in CAPEX is a reasonable projection if you consider worldwide information technology spending is expected to reach $6.4 trillion this year.
Source: Altimeter (Brad Gerstner)
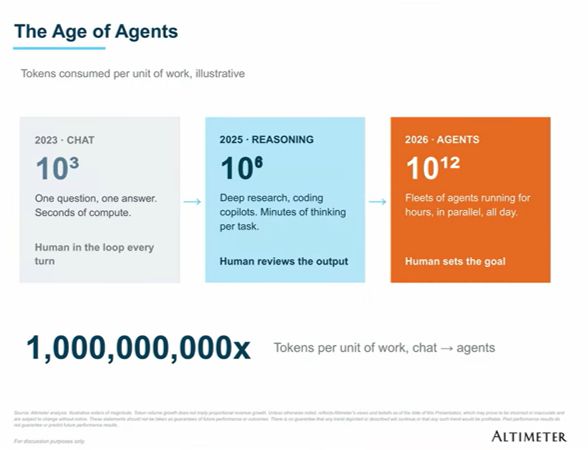
- Exploding Usage: We are still in the first inning of AI adoption, yet usage is skyrocketing as workflows shift from basic chat queries to inference processing and autonomous AI agents. Measured by data unit tokens processed, activity has scaled 1,000,000,000 (one billion-fold) since 2023 (see table below), driving the insatiable need for next-generation data centers.
Source: Altimeter (Brad Gerstner)
Guardrails and Regulation Can Mitigate Risks
While AI adoption surges, business and government are actively collaborating to implement sensible guardrails. Acknowledging legitimate concerns, tech titans and political leaders recently met at a White House AI Summit* to sign safety pacts and discuss regulatory frameworks. Furthermore, existing liability laws can and should hold companies accountable if they negligently release harmful products – just as automakers like Tesla should be held accountable if harmful autonomous vehicle are released. The high-profile anxiety surrounding AI is ultimately a net positive: it has forced tech CEOs to prioritize safety and placed Washington on high alert.
While alarmists continue to capture headlines with tales of extinction dread, financial markets and real-world innovation will continue to surge ahead.
*AI White House Summit attendees included Anthropic CEO Dario Amodei, SpaceX and Tesla CEO Elon Musk, Nvidia CEO Jensen Huang, Meta CEO Mark Zuckerberg, Amazon founder Jeff Bezos, Alphabet CEO Sundar Pichai, Microsoft CEO Satya Nadella, Advanced Micro Devices CEO Lisa Su, Palantir CEO Alex Karp and OpenAI President Greg Brockman.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (October 1, 2026). Subscribe Here to view all monthly articles.
Sidoxia Capital Management (SCM) and some of its clients hold positions in AAPL, AMZN, GOOGL, META, MSFT, TSLA, NVDA, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position NFLX, AMD, PLTR, or in any other security referenced in this article.
DISCLOSURE: No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Each investor’s situation is unique so please work with a professional financial adviser, tax accountant or legal representative, as applicable, to develop an individualized plan or address any questions you may have. Investing involves risk including the possibility of loss of one’s investment.
Big Debt and Massive AI Bet Not Yet a Threat
Government debt levels have reached stratospheric heights, and hundreds of billions in corporate borrowing are piling up to finance a gargantuan AI data center infrastructure buildout.
How have stock and bond investors responded to this unprecedented debt binge?
With a collective shrug.
For the month, the major stock indexes continued their march higher:
· S&P 500: +2.6%
· NASDAQ: +3.9%
· Dow Jones Industrial Average: +1.3%
Meanwhile, the bond market largely shrugged off hawkish rhetoric surrounding potential interest rate hikes from Federal Reserve Chairman Kevin Warsh following his speech at the closely watched Jackson Hole annual symposium.
More specifically, fixed-income performance held steady:
· U.S. Aggregate Bond (AGG): +0.0%
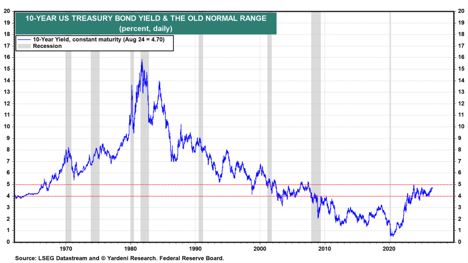
· 10-Year Treasury Note Yield: +0.3%(4.76%) Although interest rates have risen significantly from their post-pandemic lows, yields remain near historically manageable levels (see chart below) – especially when framed against the backdrop of robust corporate profit growth and broader economic resilience.
Source: Ed Yardeni
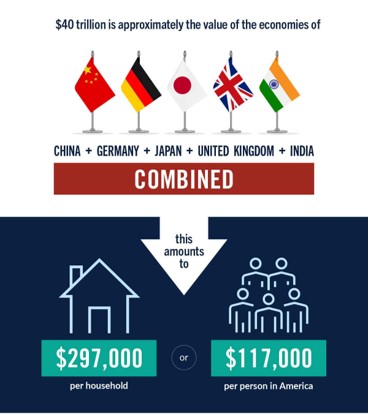
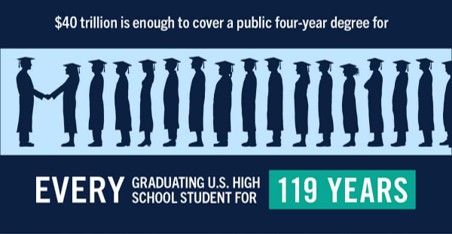
$40 Trillion Mountain of Debt As highlighted by the Peter G. Peterson Foundation, gross U.S. federal debt has officially breached the $40 trillion mark. To put that figure into perspective, here are a few insightful graphics (below).
Source: Peter G. Peterson Foundation
$40 trillion roughly equals the combined gross domestic product (GDP) of China, Germany, Japan, the UK, and India. It also translates to approximately $297,000 per U.S. household or $117,000 per person.
Source: Peter G. Peterson Foundation
Expressed another way, $40 trillion could cover four-year college tuition for every graduating high school senior in America for the next 119 years.
$40 Trillion in a Historical Perspective
Source: The Wall Street Journal
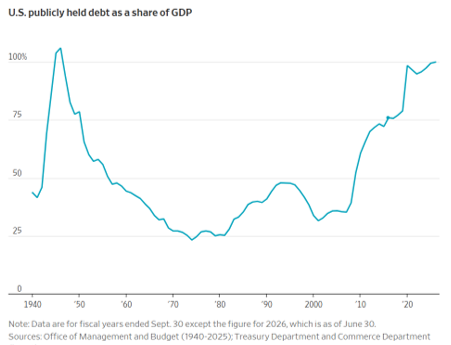
Measuring raw dollar debt over long spans of time can be misleading due to compound inflation. A far more accurate economic yardstick is calculating debt as a percentage of GDP (Gross Domestic Product). As shown above, national debt-to-GDP levels haven’t reached these heights in a generation – not since the massive fiscal spending surge needed to finance World War II.
Hand-wringing over national debt is hardly new. Over four decades ago, the front page of The New York Times (Sept 15, 1985) declared: “A $2 Trillion National Debt: Not Just Another Milestone.” The warnings then sounded identical to the alarms sounding today: “The $2 trillion figure reflects serious problems for government taxation and spending, as well as new strains on the economy.”
Just as in prior historical cycles, elevated debt ratios can eventually be brought back into balance. However, the longer policymakers kick the fiscal can down the road, the more difficult it will be to reverse the damaging trend. Mathematically, the remedy remains unchanged: the federal government must curb expenditures (Social Security, Medicare, and defense spending) and/or raise revenues (increase taxes).
How Can Stocks Prices Be at Record Highs?
Against a headline backdrop dominated by exploding federal debt, ongoing geopolitical conflict in the Middle East, Fed rate uncertainty, and AI data center backlash, how do equity markets keep hitting record highs?
It boils down to two fundamental drivers:
1) Surging Corporate Profitability
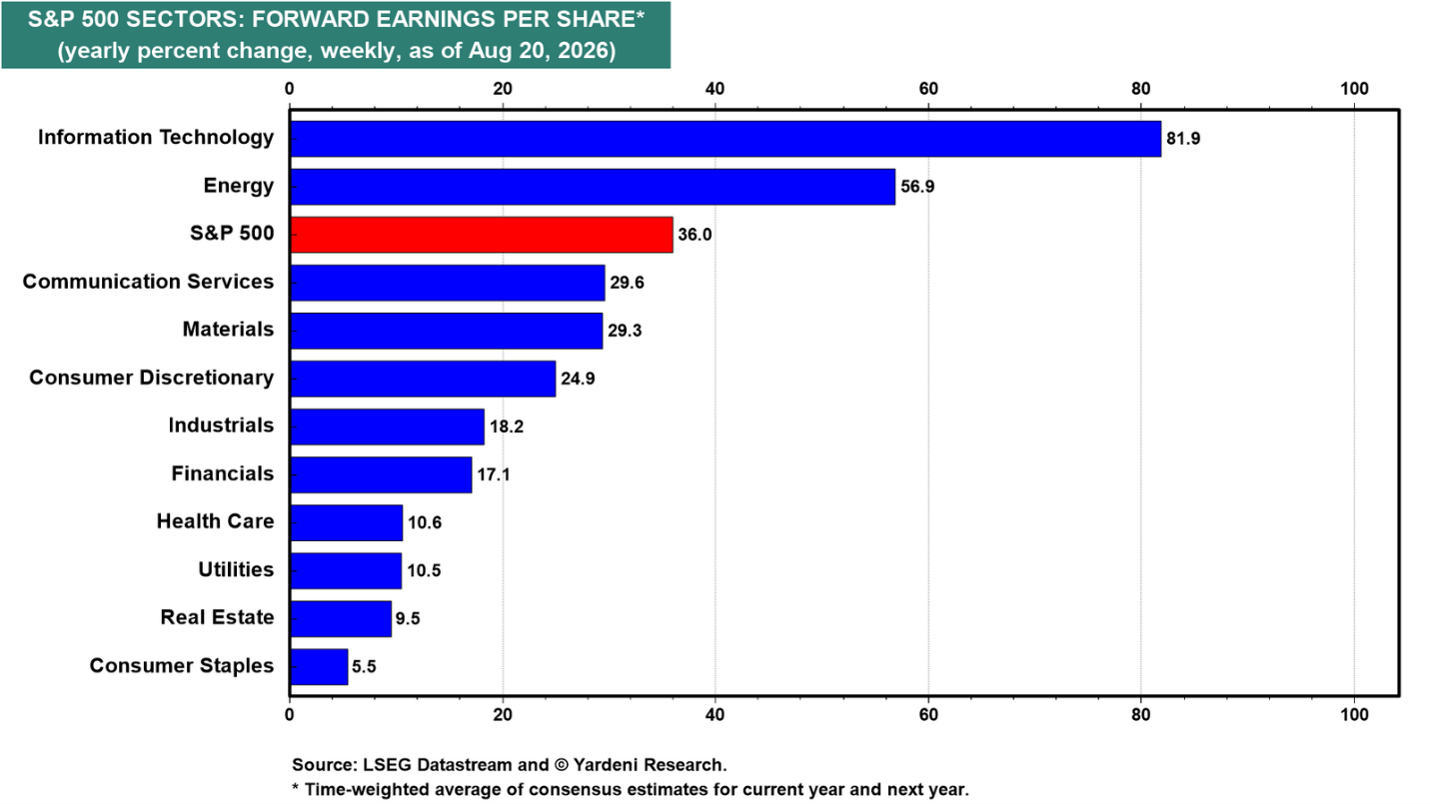
A solid underlying economy, anchored by healthy employment metrics (4.1% unemployment in July) is receiving a direct shot of adrenaline from the colossal capital investment flowing into artificial intelligence (see The Multi-Trillion AI Tsunami). Beyond reducing software coding overhead and customer support overhead via automated software agents, AI implementations are accelerating go-to-market timelines and driving faster top-line growth. The end result is an expanding waterfall of corporate profits, reflected in robust forward consensus estimates for +36% S&P 500 earnings growth (see chart below).
Source: Ed Yardeni
2) Mammoth AI Capex Converting to Revenues:
We remain in the early stages of the AI buildout, yet hyper-scalers and chipmakers are generating extraordinary top- and bottom-line expansion.
Consider NVIDIA Corp. (NVDA), sitting at the epicenter of the hardware buildout with a market valuation topping $5 trillion. The company recently posted nearly $100 billion in quarterly revenue while clearing over $50 billion in quarterly profit. Meanwhile, AI juggernaut Anthropic (founded just five years ago vs. NVIDIA 33 years ago), reported a $6.5 billion annual revenue run-rate in July, with internal projections pointing toward $190 billion to $200 billion by 2028. Reports indicate Anthropic is targeting a valuation as high as $2 trillion ahead of an anticipated public listing.
Airbnb: A Real-World AI Case Study
For skeptics questioning whether end-user enterprises are seeing concrete returns on their AI investments, look no further than the cloud computing divisions of major tech providers. Alphabet (GOOG), Amazon (AMZN), and Microsoft (MSFT) are collectively spending an estimated $615 billion in capital expenditures this year, which is backed by an impressive $1.4 trillion in combined remaining performance obligations (RPO) commitments from enterprise customers. The cloud divisions of the hyperscalers have achieved these whopping results with very minimal headcount growth (see AI Genie Out of the Bottle).
For the AI doubters, I would also direct you to the recent Q2 Shareholder report of Airbnb Inc. (ABNB), a Sidoxia Capital Management and personal investment. In the company’s Q2 Shareholder Letter, Co-Founder and CEO Brian Chesky detailed how fundamental integration of AI is translating into operational productivity.
“We’ve rebuilt Airbnb from the ground up to be an AI-native company, and it’s showing up in our results… On key initiatives, we’ve reduced the time from concept to delivery by as much as 60%. And compared to the same period last year, we’ve increased the number of features and improvements we’ve shipped this year by nearly 80%… The acceleration from AI allowed us to make hundreds of improvements across Airbnb for hosts and guests.”
These platform enhancements include:
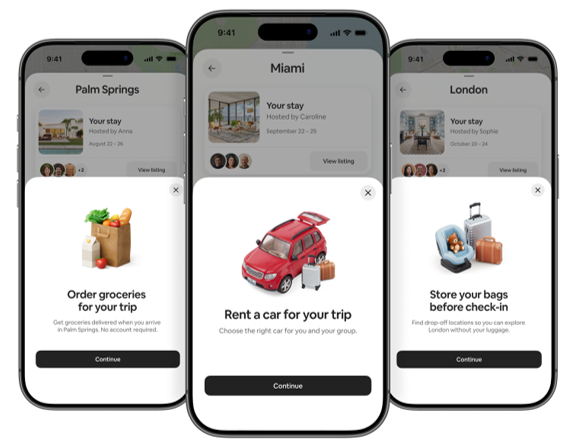
- Hotel Stays: Seamless integration of thousands of new boutiques and independent hotels to the platform.
- Grocery Delivery: Partnered with grocer-delivery leader, Instacart (another Sidoxia investment).
- Car Rentals: Integrated rental car bookings with major fleets (including Hertz, Avis, Budget, and Enterprise).
- Airport Pickups: Feature added to increase convenience for travelers.
- Luggage Storage: Logistic benefit provided to customers arriving before check-in times (CEO called this a “sleeper hit”).
Source: Airbnb
It’s not difficult to imagine a day, in the not-too-distant future, when a query to Airbnb asking to organize my trip to Italy can result in the app automatically coordinating my entire customized itinerary in seconds.
Beyond improving the customer experience, AI is simultaneously reshaping Airbnb’s unit economics. Their AI customer support assistant now operates in 50 countries, resolving nearly 45% of incoming support inquiries autonomously without human agent intervention and has been rated the best AI support assistant in travel. This automation has driven a -16% reduction in its cost-per-booking translating into huge savings for the company.
Skeptics should take note of the next leg of AI expansion. The next major phase will be driven by all the companies/industries racing to learn and implement AI, so businesses can experience similar benefits accomplished by Airbnb.
The Net-Net
There is never a shortage of macroeconomic worries, including $40 trillion in national debt, central bank shifts, or geopolitical friction. Yet over multi-year horizons, stock prices track earnings and innovation. Right now, accelerating corporate productivity and the massive early-stage deployment of AI infrastructure remain the primary engines pushing equity markets to new all-time record highs.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (September 1, 2026). Subscribe Here to view all monthly articles.
Sidoxia Capital Management (SCM) and some of its clients hold positions in NVDA, GOOGL, AMZN, MSFT, ABNB and certain exchange traded funds (ETFs), but at the time of publishing had no direct position in any other security referenced in this article.
DISCLOSURE: No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Each investor’s situation is unique so please work with a professional financial adviser, tax accountant or legal representative, as applicable, to develop an individualized plan or address any questions you may have. Investing involves risk including the possibility of loss of one’s investment.
AI Genie Out of the Bottle – Despite Attempts to Throttle
While geopolitics, interest rates, inflation, and economic growth constantly influence financial markets, the primary driver of stock prices over recent years remains the rapid global adoption of artificial intelligence. Ever since OpenAI’s ChatGPT sparked the AI revolution in November 2022, the technology landscape has been permanently altered. Although local pushback against the massive AI infrastructure rollout is intensifying, the AI genie is out of the bottle – and it cannot be put back in.
Data Center Angst, Chinese Competition, and Bubble Spending Concerns
Last month proved to be a choppy period for equity investors. In addition to escalating geopolitical tensions in the Middle East, markets were rattled by surging Chinese AI capabilities and semiconductor competition. The China tech rivalry is highlighted by the release of Moonshot’s Kimi K3 model and the IPO (Initial Public Offering) of chipmaker CXMT, the largest company trading on mainland China, valued near $500 billion.
The technology sector took the largest brunt of the selling pressure. The NASDAQ index fell -3.2% and the Magnificent 7-heavy QQQ index tumbled -6.6%. The S&P 500 index and Dow Jones Industrial Average had more modest moves, down -0.1% and up +0.3%, respectively for the month.
The AI Data Center Backlash
While consumers and businesses enjoy the instant productivity gains of AI software, a groundswell of community opposition is rising against the physical footprint required to power these tools. Critics frequently cite concerns over potential job losses, rising electricity bills, regional water consumption, rogue agent cyber-attacks, negative effects on residential property values, and other environmental damages.
A recent Gallup survey revealed that 71% of Americans oppose data center construction in their local communities. Currently, 15 states have enacted or proposed moratoriums/bans on new data center construction (see States Banning Data Centers).
While “NIMBY” (Not In My Back Yard) opposition may delay or defer localized builds, the overarching economic and strategic advantages of AI mean development will press forward. To win over reluctant municipalities, hyperscalers (including, Amazon, Google, Microsoft, and Meta) are offering tailored community benefit agreements, local grid investments, and environmental commitments (see Hyperscalers Put Community Investment First).
As Doug Sims, Managing Director at Green Finance & Economic Development, notes, hyperscalers are funding “investments in weatherization, home repairs, heat pumps, distributed solar and storage, and demand-management technologies.” These initiatives lower peak energy demand and reduce household costs while helping secure local permits. Communities that embrace this infrastructure stand to reap substantial long-term rewards in high-paying jobs and expand their local tax base.
Does AI Work? Is it Worth Trillions in Investment?
A central debate across Wall Street is whether the estimated $6 trillion in projected spending on AI chips, data centers, and power grid upgrades over the next five years will generate sufficient economic returns (see my previous article, The Multi-Trillion AI Tsunami).
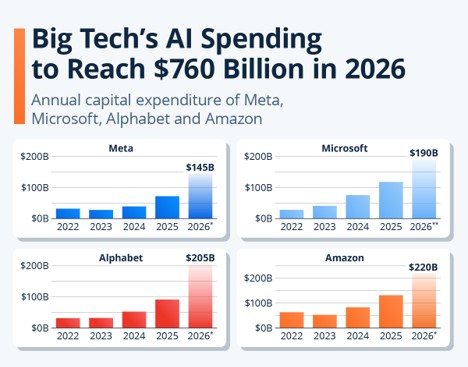
From my vantage point, the answer is a resounding yes. One need look no further than the massive $760 billion in combined capital expenditure projected for 2026 alone across Meta, Microsoft, Amazon, and Alphabet – an 84% increase over the $413 billion spent in 2025 (see chart below).
Source: Statista
Where’s the Beef?
Given these staggering capital outlays, investors are understandably asking when and where the payoff will materialize.
I may be dating myself but an iconic commercial introduced when I was a kid captures this sentiment. For any hamburger enthusiasts, you may remember the 1984 Wendy’s “Where’s the Beef?” commercial, in which three elderly customers examine a massive, fluffy bun only to find a tiny patty buried inside. Wall Street is currently looking at hyperscaler capital expenditures and asking the same question: “Where is the meat on this multi-billion-dollar AI burger?”
While free cash flow profiles are temporarily compressed by infrastructure buildouts, there is already plenty of high-protein evidence demonstrating that these investments are paying off:
· Accelerating Top-Line Cloud Revenues
· Record Commercial Backlogs/Remaining Performance Obligations (RPO)
· Substantial Productivity Gains
Let’s review the latest growth figures from the four major hyperscalers:
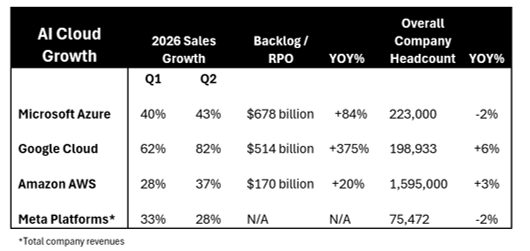
The $760 billion in spending by the “Big 4” hyperscalers is astounding but the backlogs (orders received but not fulfilled) for just the top three (Microsoft, Google, and Amazon) are even more gigantic at approximately $1.4 trillion (see Backlog/RPO column total in table above). If AI technology lacked real-world utility or failed to generate economic returns, enterprise customers would not be locking in massive orders in multi-year forward commitments. Despite achieving surging revenue growth, hyperscaler headcount growth remains remarkably subdued (see far-right column in table above). This is proof positive that internal AI deployment is unlocking operating leverage and efficiency.
Looking Ahead
We remain in the early innings of the enterprise AI adoption curve. Even if political maneuvering or regulatory friction slows the pace of data center construction in certain jurisdictions, it will simply extend the runway of this infrastructure super-cycle rather than trigger a boom-and-bust collapse. The AI genie has granted far more wishes than it has denied – and despite attempts to throttle its momentum, the AI transformation continues to march forward.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (August 3, 2026). Subscribe Here to view all monthly articles.
Sidoxia Capital Management (SCM) and some of its clients hold positions in AMZN, GOOGL, META, MSFT, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position in 688825.SS (CXMT), WEN, or any other security referenced in this article.
DISCLOSURE: No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Each investor’s situation is unique so please work with a professional financial adviser, tax accountant or legal representative, as applicable, to develop an individualized plan or address any questions you may have. Investing involves risk including the possibility of loss of one’s investment.
Stocks Soar as Profits Roar
The Geopolitical Dilemma: Iran Gone Wrong
It has been a volatile and unsettling period in the Middle East. Following more than a month of continuous bombing in Iran, the United States reached a tenuous ceasefire. While the active conflict has paused, the U.S. continues to maintain a financially crippling blockade against the Iranian regime.
If that geopolitical stress isn’t enough, oil prices remain elevated at $105 per barrel (WTI), roughly 57% above levels seen before the bombings began. Furthermore, gasoline prices hovering around the $4.40 per gallon threshold are acting like a brake that is slowing down global economic activity.
On the surface, this negative narrative sounds like a disastrous backdrop for financial markets. Yet, last month’s stock market performance tells a completely different story:
· S&P 500: +10.4%
· NASDAQ: +15.3%
· Dow Jones Industrial Average: +7.1%
Why the Disconnect?
Followers of my firm, Sidoxia Capital Management, and my blog, Investing Caffeine, know that geopolitics are rarely the primary drivers of long-term stock performance. Instead, we look to the “four legs of the Sidoxia stool”: profits, interest rates, valuations, and sentiments. For a deeper dive, check out my article: Don’t Be a Fool, Follow the Stool. The vital leg supporting the recent move in stocks has been soaring profits. As illustrated by data from Yardeni.com, S&P 500 profits (red line) are accelerating at a much steeper pace than those of the S&P 400 MidCap (blue line) and S&P 600 SmallCap (green line).
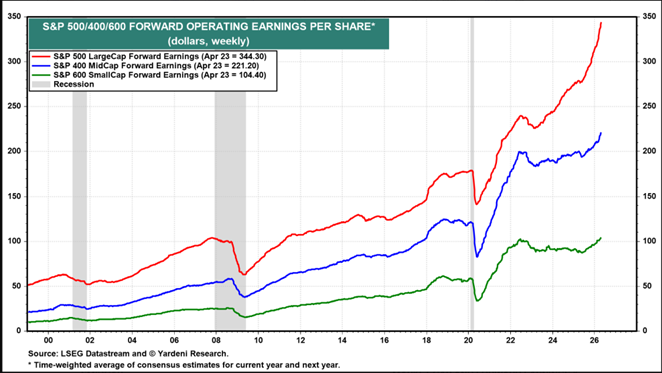
Source: Yardeni.com
A major contributor to this profit expansion is rising profit margins. Today, companies are earning a profit of approximately11 cents per dollar of sales, compared to just 5.5 cents during the 1970s and 1980s. The chart below highlights this phenomenon.
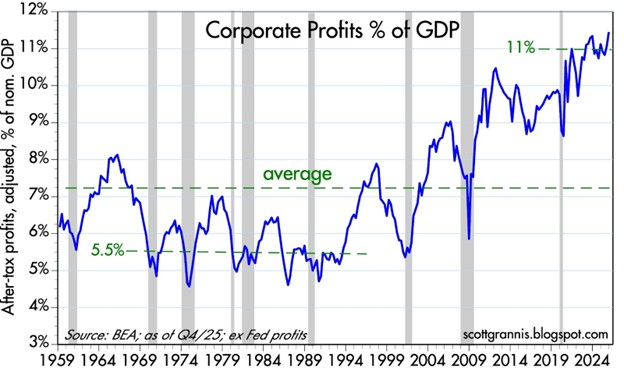
Source: Calafia Beach Pundit
The AI Productivity Revolution
What is driving much of this margin expansion? You guessed it: Artificial Intelligence.
We need to look no further than the mega-cap tech companies that reported Q1 financial results this week (Alphabet, Amazon, Microsoft, and Meta Platforms) to see how AI is helping companies cut costs and grow revenues:
- Combined, these four companies boast a revenue run-rate exceeding $1.7 trillion, with an accelerating growth rate above +22%.
- Meanwhile, headcount growth at these firms has remained virtually flat at < 2%. In fact, Meta and Microsoft recently announced a combined 20,000 in job cuts, raising concerns over an AI labor crisis.
These sales increases and expense reductions help explain last month’s surge in the performance of these stocks:
- Alphabet-Google (GOOGL): +33.9%
- Amazon.com Inc. (AMZN): +27.3%
- Microsoft Corp. (MSFT): +10.2%
- Meta Platforms Inc. (META): +6.8%
AI Driving the IPO Pipeline The AI boom is also creating massive value in the private markets. High-profile expected IPOs – including Elon Musk’s xAI, OpenAI (makers of ChatGPT), and Anthropic – are expected to exceed a combined $2 trillion in valuation. The graphic below shows the gargantuan size of these expected IPOs.
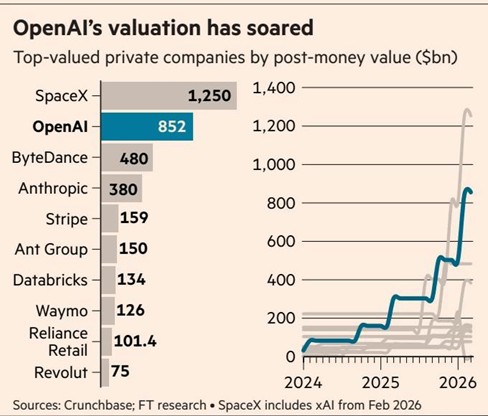
Source: Financial Times
The AI Train is Leaving the Station
AI is impacting every industry and every worker in some way, and this disruptive wave will undoubtedly displace some jobs. However, investors have the opportunity to jump on the train rather than be left behind.
As I noted in my recent article, The Saaspocalypse Has Arrived—or Has It?, if history repeats itself, the rollout of new technologies creates an influx of new industries and jobs that offset initial disruptions. If you work in an industry vulnerable to AI proliferation, taking advantage of the AI profit revolution can help offset potential financial disruption.
Of course, not everything is rainbows and unicorns. The Iranian conflict could still spiral out of control, which could quickly reverse recent stock market gains.
As I recapped for investors last month:
“History reminds us that while geopolitical shocks are terrifying in the moment, their impact on diversified portfolios is almost always temporary… In the world of investing, the best time to stay disciplined is exactly when everyone else is looking for the exit.”
Suffice it to say, geopolitics can and will impact short-term performance, but they rarely dictate long-term trends. When analyzing the market, it is crucial to remember a fundamental truth: When profits roar, stock prices often soar.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (May 1, 2026). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in GOOGL, META, AMZN, MSFT, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position in any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.
Bombs Away – Iran & Oil Spark an Explosive Month
The stock market felt the blast of geopolitical tension last month as all three major domestic indexes all retreated. In March, the S&P 500 fell -5.1%, the Dow Jones Industrial Average dropped -5.4%, and the NASDAQ slid -4.8%.
While a -5% monthly drop grabs headlines, perspective and context are key. Since the start of 2023, the S&P 500 remains up approximately +70% (excluding dividends). Even after the recent -7% pullback from January’s record highs, the index is still trading +35% above its April 2025 lows.
The Strait Has Created An Oil Gate
The primary catalyst for the market volatility is the escalating conflict involving the U.S., Israel, and Iran. Beyond the tragic human cost, the economic “bomb” has been the disruption of the Strait of Hormuz, which handles the flow of roughly 20% of the world’s oil supply.
Basic economics dictates that when supply is choked, prices skyrocket. We saw exactly that: WTI Crude spiked roughly +54% over the last month, surging from $67 to a peak near $103 per barrel (see chart below).
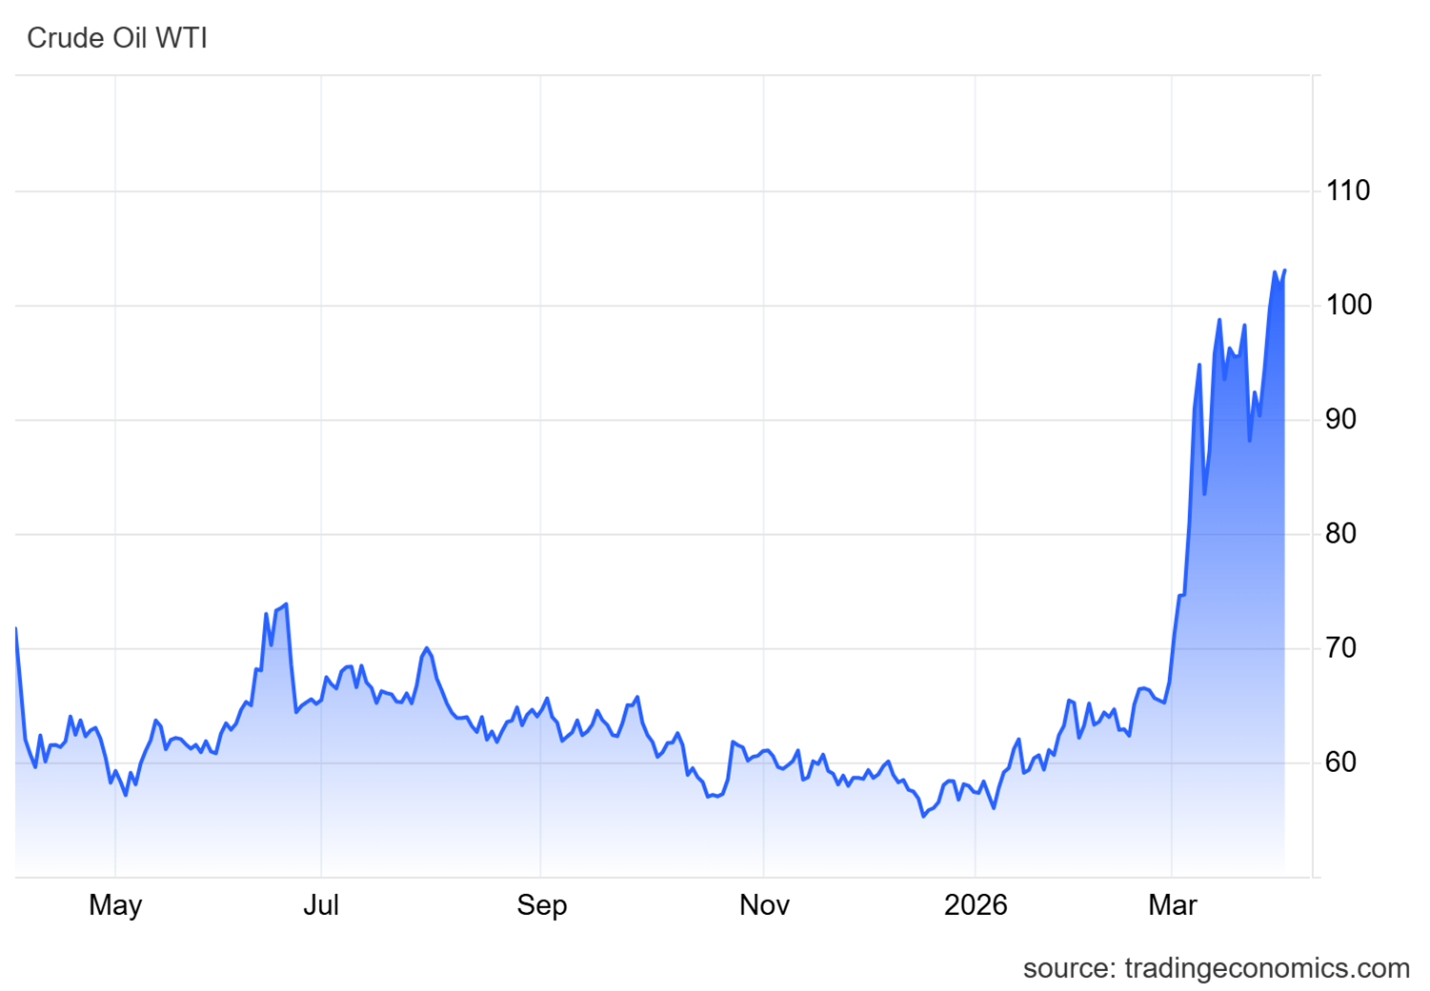
The “energy tax” from higher oil prices has introduced four major stressors for investors:
- Drained Consumer Wallets: Every extra dollar spent at the pump is a dollar not spent on groceries, healthcare, or retail. Since consumers disproportionately control the U.S. economy, cuts in discretionary spending on things like vacations, cars, and houses has a material negative impact on the nation’s financial output.
- Widespread Industrial Shock: High oil prices inflate costs for almost every physical industry, including airline fuel, trucking logistics, petroleum-based fertilizers, and construction inputs like asphalt and steel.
- Labor Market Cooling: The February jobs report was a wake-up call, showing a loss of -92,000 jobs (well below the expected gain of +130,000). While AI-driven displacement is a factor, the sudden spike in energy overhead has clearly contributed to employers pausing their hiring.
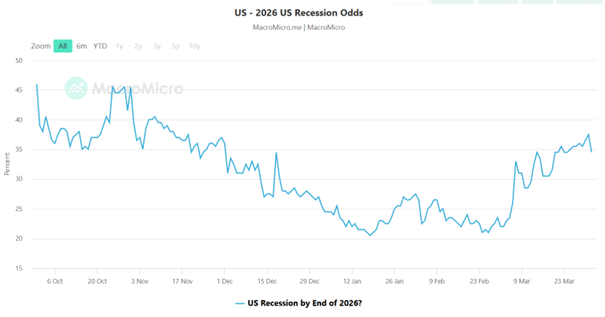
- Recessionary Red Flags: Prediction markets like Polymarket now place the probability of a U.S. recession by the end of 2026 at 34.5%, up significantly from just a few months ago (see chart below).
Source: MacroMicro & Polymarket
Geopolitical Noise vs. Market Reality
While current volatility feels unique, seasoned investors have seen this movie before. It is easy to forget that the S&P 500 slumped -21% last year as markets grappled with the administration’s aggressive tariff strategies, only to see prices roar back once the initial shock subsided. Even with the recent -7% pullback from January’s record highs, the S&P 500 remains +35% higher than the lows of April 2025.
Both the tariff friction and the Iranian conflict could be viewed as “self-inflicted” geopolitical maneuvers. While the long-term economic gains of these high-stakes decisions are still being debated, one short-term reality is certain: the November midterm elections are fast approaching.
History suggests that as elections loom, the administration will prioritize stability and “voter-friendly” economic conditions. We are already seeing a shift in rhetoric that suggests an “off-ramp” for the Iran conflict may be closer than the headlines imply. President Trump is addressing the nation today with an update on the current situation. When political capital is on the line, pragmatic pivots often follow unpopular volatility. What does this mean for investors? This means we are likely closer to the end of this Iranian conflict than we are to the beginning.
The Resilience of History
The last decade has been a relentless cycle of “unprecedented” global unrest. However, as the timeline below illustrates, geopolitical shocks have historically acted as speed bumps, not roadblocks, for long-term equity growth:
- 2026: Maduro Kidnapping (Venezuela)
- 2025: Operation Midnight Hammer (Iran)
- 2024: Collapse of the Assad Regime (Syria) & Moscow Terrorist Attack
- 2024: Houthi Red Sea Attacks
- 2023: Israel-Hamas Conflict
- 2022: Russia-Ukraine Invasion
- 2021: U.S. Withdrawal from Afghanistan
- 2017: North Korean “Fire and Fury”
- 2016: Brexit
- 2015: Paris Terrorist Attacks
The Bottom Line: Since the beginning of 2015, the S&P 500 has more than tripled (+217%). The data is clear: even in the face of horrific global events, the market’s primary engine – corporate innovation and earnings – tends to prevail. In the world of investing, a timeless (if cynical) truth remains: “When missiles fly, it’s time to buy!”
The Fed’s “Wet Towel”
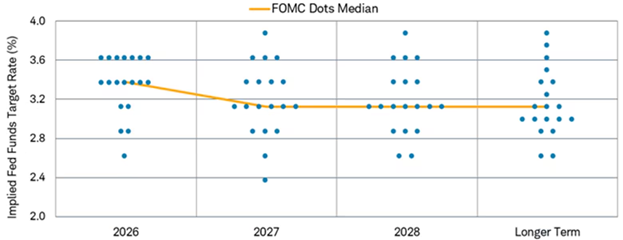
This oil-driven inflation has also doused hopes for aggressive monetary easing. At the start of the year, the appointment of Kevin Warsh as the incoming Fed Chairman (set to succeed Jerome Powell in May) led markets to price in multiple rate cuts. However, the March “dot plot” (see chart below) revealed a much more hawkish reality. The Federal Reserve now projects only one 25-basis-point cut for the remainder of 2026, bringing the target range to 3.25%–3.50%. Seven officials now see zero cuts this year, reflecting a “higher for longer” stance as they battle renewed energy-led inflation.
Source: Charles Schwab
The Sidoxia Strategy: Don’t Fear the Turbulence
History reminds us that while geopolitical shocks are terrifying in the moment, their impact on diversified portfolios is almost always temporary. Since 2015, the S&P 500 has more than tripled (+217%) despite a decade defined by the Russia-Ukraine war, the collapse of the Assad regime, and various “Operation Midnight Hammer” style conflicts.
As we look toward the November midterm elections, we expect political rhetoric to shift toward stabilization. President Trump has already signaled that an “offramp” for the Iranian conflict may be approaching, as high energy prices are rarely a winning campaign strategy. At Sidoxia, we aren’t distracted by the noise of the “bombs.” We continue to focus on fundamental valuations and opportunistically use this volatility to improve our clients’ positioning. In the world of investing, the best time to stay disciplined is exactly when everyone else is looking for the exit.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (Apr. 1, 2026). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in certain exchange traded funds (ETFs), but at the time of publishing had no direct position in any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.
The SaaSpocalypse Has Arrived…Or Has It?
Well, the new month has started with a bang. Financial markets have not only experienced a bang from another military strike on Iran, but also an explosion of AI paranoia. As hundreds of billions of AI investment dollars flood into the economy, fears are intensifying that the AI displacement of workers could have a detrimental impact on the economy and financial markets.
The Monthly Scorecard
It was a mixed performance in the market last month. Geopolitical headlines surrounding Iran and the Middle East are currently front and center, but under the surface, the real story isn’t just geopolitics—it’s a growing investor anxiety around artificial intelligence and its disruptive potential. Here’s what happened last month:
- S&P 500: -0.9%
- Dow Jones Industrial Average: +0.2%
- NASDAQ: -3.4%
The “SaaSpocalypse” and the Tech Identity Crisis
Software stocks are currently under assault, plunging -9.7% for the month and a staggering -22.8% for the start of the year (as measured by the IGV iShares Software index). Analysts are calling this the “SaaSpocalypse” (Software as a Service)—a phenomenon where the market fear is that AI is “eating” software companies.
High-profile casualties have added fuel to the fire. IBM, for example, suffered its worst trading day in 25 years, dropping -13% in a single day. Concerns came to light that new AI agent coding tools like Anthropic’s Claude Code could threaten IBM’s legacy dominance in COBOL-based mainframe systems.
Paranoia vs. Reality
This “AI Paranoia” has spread far beyond Silicon Valley, infecting industries like transportation, banking, travel, real estate, and food delivery. Two major catalysts fueled this fire:
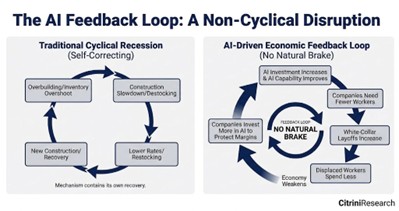
The Citrini Report: A viral, dystopian report from described an “avalanche” of white-collar firings (see chart below). The report argues that while the government may try to intervene with stimulus, it “won’t change the fact that an AI Claude agent can do the work of a $180,000 product manager for $200/month.”
Source: Citrini Research
- Corporate Reductions: High-profile cuts have validated these fears. Block Inc. (led by Jack CEO Dorsey, former Twitter Founder) announced it is slashing 40% of its workforce due to AI advancements, while Amazon recently eliminated 30,000 white-collar positions (10% of its corporate staff).
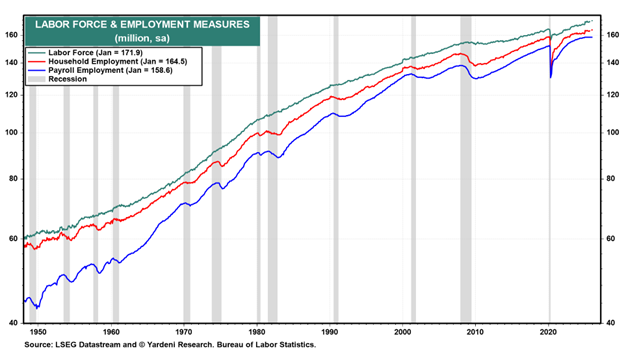
However, there is a silver lining to that perspective. While software jobs have flattened since ChatGPT arrived in late 2022, we have yet to see the “cliff dive” in total employment that many predicted. In fact, employment (165 million employed) and labor force (172 million) figures are near record levels, so we have not seen AI kill the economy quite just yet (see chart below).
Source: Yardeni Research and Bureau of Labor Statistics
The Great Rotation: Looking for “HALO”
As investors try to decipher the winners and losers, they are migrating away from technology and rotating into HALO stocks (Hard Asset, Low Obsolescence). These companies are seen as less susceptible to AI disruption. Evidence of this shift is clear in the outperformance of value, small-cap, and mid-cap stocks. Notably, the Dow Jones Industrial Average, an index heavy with hard asset exposure, just posted its 10th consecutive month of gains despite the broader technology stock volatility.
A Massive Bet on the Future
Despite the “bubble” murmurs, the AI juggernauts are doubling down. OpenAI just closed the largest private financing in history, raising $110 billion—including $50 billion from Amazon, $30 billion from NVIDIA, and $30 billion from SoftBank. The demand for compute and data centers remains insatiable, supported by the $700 billion being spent by the large hyperscalers (Amazon, Alphabet-Google, Microsoft, and Meta Platforms) this year.
Geopolitical and Legal Headwinds
Adding to the month’s complexity are external shocks:
- Middle East Tensions: Military strikes on Iran recently killed the Iranian Supreme Leader, Ali Khamenei, and other key leaders, injecting significant geopolitical risk.
- Tariff Uncertainty: The Supreme Court recently ruled against the IEEPA tariffs instituted by the Trump administration. While temporary alternatives are in place, the markets are waiting for a permanent solution to work through the courts.
Resilience in the Face of Technological Change
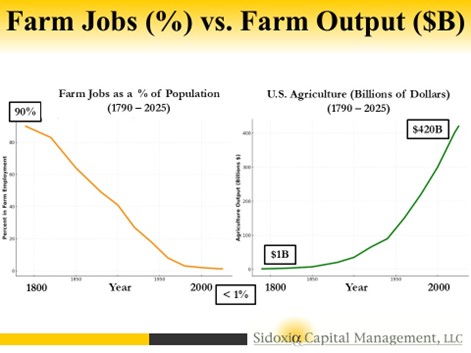
It is easy to get lost in the dystopian narrative, but history offers a more hopeful guide. Technology has been replacing human workers for centuries—from the looms of the Industrial Revolution to the tractors of the Agricultural Revolution – see chart below (1790 – 2025). In every instance, while specific roles were displaced, new industries emerged that not only soaked up the unemployed but expanded the labor force into areas we couldn’t have previously imagined (see also The Fallacy Behind Technological Innovation).
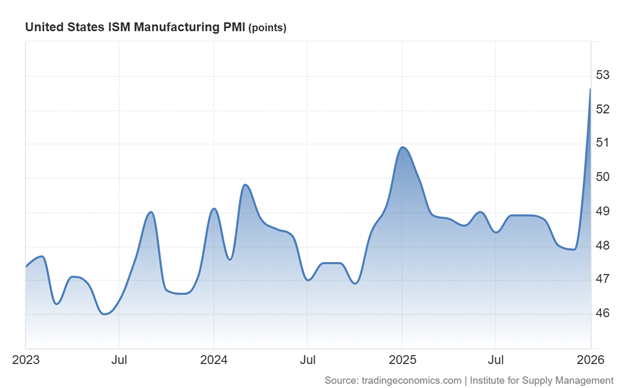
The reality today is that the economy remains remarkably strong. Employment data is resilient, labor force participation is near record levels, and corporate profits are breaking out to new all-time highs. Furthermore, the ISM Manufacturing PMI (Purchasing Managers Index) recently spiked to 52.6, signaling an expansion in a sector that had been declining for years (see chart below).
Source: Trading Economics
We are not witnessing the end of work, but rather a high-speed evolution. As we’ve seen before, the human capacity for innovation and adaptation usually outruns the machines.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (Mar. 2, 2026). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in AMZN, GOOGL, META, MSFT, NVDA, certain exchange traded funds (ETFs), but at the time of publishing had no direct position in IBM, XYZ or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.
Scary Headlines Abound as Dow Knocks on 50-Thou…What Now?
The Dow Jones Industrial Average first crossed the 40,000 milestone in mid-2024 (see Investing Caffeine – Dow 40,000), yet barely 18 months later, the index has notched another record closing high and is now knocking on the door of 50,000.
For the most recent month:
Dow Jones: +1.7%
S&P 500: +1.4%
NASDAQ: +1.0%
Remarkably, as we enter 2026 flirting with these major milestones, this marks the third consecutive year of double-digit gains across the major stock indices—despite what feels like a nonstop barrage of alarming and often unimaginable headlines.
And that’s the key point.
A World on Fire… According to the Headlines
• Greenland Takeover Threat: Over a year ago, President Trump declared U.S. control of Greenland an “absolute necessity” for national security amid rising Russian and Chinese Arctic influence. Last month, tensions escalated when a proposed tariff regime—starting at 10% and rising to 25%—was announced against Denmark and several European allies. Markets ultimately breathed a sigh of relief after tariffs and military threats were reversed following the announcement of a negotiated framework.
• Venezuelan Invasion: In early January, U.S. forces executed a high-precision raid of the Venezuelan capital of Caracas in the middle of the night, when President Nicolas Maduro was successfully extracted without any Americans killed. Maduro now faces narcoterrorism and corruption charges in federal court in Brooklyn. Meanwhile, Secretary of State Marco Rubio has spearheaded a plan that prioritizes the rebuilding of Venezuela’s oil infrastructure by seizing tankers and millions of barrels of sanctioned crude oil to finance the reconstruction.
• ICE Protests in Minnesota Turn Deadly: Immigration protests in Minnesota escalated last month, resulting in two high-profile fatalities as demonstrators clashed with federal ICE authorities (Immigration and Customs Enforcement).
• Government Shutdown (Again): A partial government shutdown began January 31, 2026, after six of twelve appropriations bills expired. Political gridlock—particularly surrounding DHS (Department of Homeland Security) and ICE funding—has once again sidelined Washington as lawmakers attempt to negotiate a resolution. House members gather back from recess on February 2nd in an attempt to end the budget standoff.
• Federal Reserve Leadership Uncertainty: Fed Chair Jerome Powell’s term expires in May. President Trump has nominated Kevin Warsh as his successor, criticizing “Too Late” Powell’s pace of rate cuts for years. Warsh, a former Fed Governor during the 2008 Financial Crisis, is widely respected but faces scrutiny regarding Fed independence, in part because he shares the President’s view that interest rates should be lower in the current environment. His Senate confirmation remains pending.
• Middle East Tensions in Iran: Following last year’s U.S. strikes on Iranian nuclear facilities, tensions have reignited amid reports of mass protester killings by Iran’s IRGC (Islamic Revolutionary Guard Corps). The U.S. has since mobilized substantial regional military assets, signaling possible intervention in support of regime change.
• Supreme Court Tariff Ruling Looms: The Supreme Court has yet to rule on the administration’s use of the International Emergency Economic Powers Act (IEEPA) of 1977 to impose sweeping global tariffs. A ruling against the government could trigger over $100 billion in retroactive refunds. The next decision window is February 20, 2026.
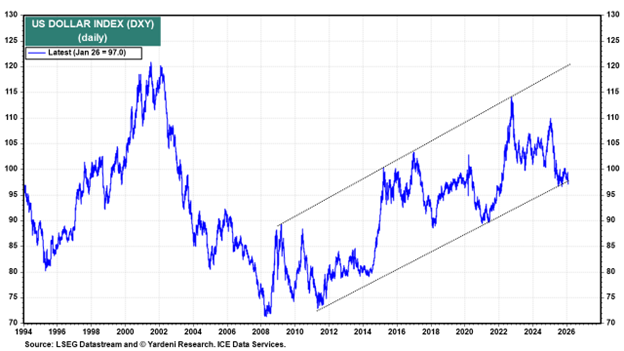
• U.S. Dollar Weakness: After declining roughly 10% in 2025, the dollar continued to weaken in January 2026 (-1%) – see chart below. Precious metals surged alongside the move—gold up +12% and silver +17% for the month—despite sharp end-of-month pullbacks.
• Cryptocurrency Collapse: Bitcoin has fallen roughly -38% from its October 2025 peak near $126,000 to about $78,000, once again challenging its “digital gold” and “store-of-value” narrative.
• Ongoing Ukraine War and Gaza Conflict: The Russia-Ukraine conflict drags into its fifth year, while violence persists in Gaza despite a loosely agreed ceasefire, with casualties continuing to rise.
Source: Yardeni Research
Don’t Believe the Hype
That’s a staggering amount of uncertainty. So how has the stock market responded?
By soaring.
S&P 500 Returns:
2023: +24.2%
2024: +23.3%
2025: +16.4%
The verdict on 2026 remains unwritten—but so far, the trend remains intact.
For most of my professional career, I’ve urged investors to tune out fear-driven media narratives (see Turn Off the TV). History repeatedly shows there is little correlation between scary headlines and long-term stock prices.
In fact, I’ve argued before that bad news can often be good news for markets (see Bad News is Good News). Conversely, in 2022 we witnessed strong employment and solid economic growth—yet both stocks and bonds suffered significant losses.
What Actually Moves Markets (“The Stool”)
Rather than reacting to noise, investors should focus on what truly drives long-term returns. At Sidoxia Capital Management, we emphasize four foundational forces (see Don’t Be a Fool, Follow the Stool):
1. Profits
2. Interest Rates
3. Sentiment
4. Valuations
These four legs of the “Sidoxia Stool” exert far more influence over market direction than daily headlines ever will.
While the current environment presents a mixed picture across these factors, monitoring them—rather than reacting emotionally to media narratives—offers investors far greater clarity on where markets may head next. And whether the Dow reaches 50,000… or 100,000 likely won’t be decided by headlines. It will be decided by fundamentals.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (Feb. 2, 2026). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in certain exchange traded funds (ETFs), but at the time of publishing had no direct position in any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.
Green Lights Everywhere… But Is It Time to Tap the Brakes?

The economic and market fundamentals appear to be flashing green lights everywhere. Growth is strong, inflation has cooled, and financial conditions have eased. Yet even with clear skies and open roads, experienced drivers know conditions can change quickly. It may not be time to slam on the brakes—but it could be time to keep a foot hovering nearby.
After the Federal Reserve aggressively applied the brakes in 2022 with seven rate hikes—taking the federal funds rate from 0.25% to 4.50%—the stock market declined nearly 19%. Since rates peaked at 5.50% in 2023, the Fed has cut rates six times, lowering them by a cumulative 1.75% to approximately 3.75%. Those cuts have helped pave the way for a smoother ride, providing a meaningful tailwind to equity markets.
That said, the most recent quarter-point cut produced mixed results. Last month, the Dow Jones Industrial Average rose +0.7%, the S&P 500 was essentially flat at –0.1%, and the NASDAQ lagged with a –0.5% decline.
Navigating the Winning Streak
We have encountered a few economic speed bumps along the way—tariffs and geopolitical events earlier in 2025, for example—but once investors realized those tariffs were more bark than bite (as I discussed previously in Tariff Sheriff), stocks resumed their impressive run. The market has now delivered three consecutive years of strong returns: 2023 (+24%), 2024 (+23%), and 2025 (+16%).
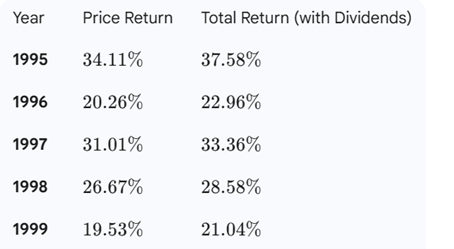
With these strong gains, today’s environment can feel like cruising on a national highway—clear roads, sunny skies, cruise control engaged, and little traffic in sight. The momentum could continue. Three strong years in a row do not rule out a fourth or fifth. In fact, the late 1990s offer a powerful reminder: from 1995 through 2000, the stock market averaged approximately 29% annual returns through the March 2000 peak (see table below). However, once the technology bubble burst, it took more than 13 years for the market to reclaim new year-end highs.
Source: Gemini
After more than three decades of investing, one lesson remains clear: trees can grow for years—but they do not grow to the sky forever. Bull markets often last longer than expected, but they eventually end.
Why the Forecast Looks Rosy
Several factors are supporting today’s strong market backdrop:
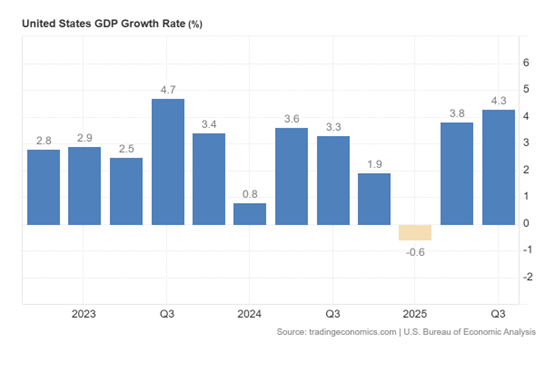
- Strong Economic Growth: Third-quarter GDP growth of 4.3% marked the fastest expansion in two years (see chart below)
Source: Trading Economics
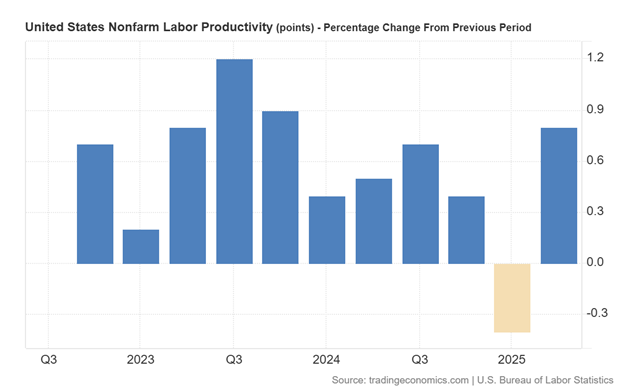
- AI-Driven Productivity: GDP growth has remained robust even as unemployment has risen from 4.0% earlier in the year to approximately 4.6% today. Growth outpacing employment is the definition of productivity, and the proliferation of artificial intelligence is accelerating this trend. Large companies such as Amazon.com (AMZN), Microsoft (MSFT), Alphabet-Google (GOOGL), and Meta Platforms (META) have reduced headcount significantly by tens of thousands in recent years while revenues and profits continue to surge (see also Mag 7 Takes Cash to the Bank).
Source: Trading Economics
- Taming Inflation: Crude oil prices have fallen roughly 20% over the last year, and Owner’s Equivalent Rent (which makes up about one-third of CPI inflation) has been steadily declining—both positive signals for inflation pressures ahead (see chart below).

Source: Calafia Beach Pundit
- Lapping Tariffs: Tariffs represented a one-time price increase. As we move into 2026, their inflationary impact should diminish as those increases roll off.
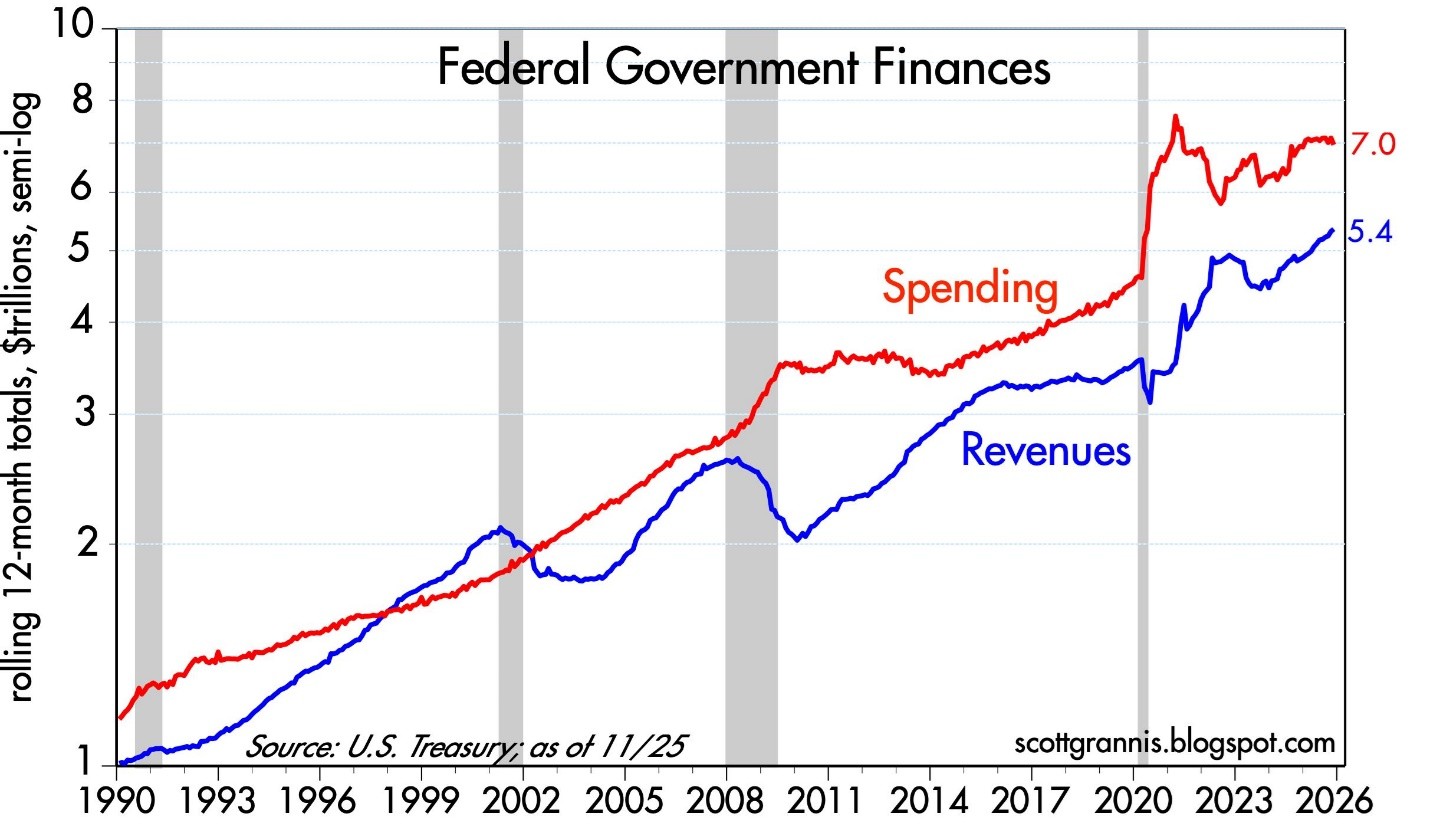
- Narrowing Budget Deficit: While debt and deficits remain headline risks, federal spending has been flat over the past year while revenues have increased roughly 10%, according to Scott Grannis (see chart below).
Source: Calafia Beach Pundit
- Tax Cuts & Higher Refunds Ahead: Many provisions of the One Big Beautiful Bill (OBBB) will be felt more fully in 2026, including 100% bonus depreciation for businesses, higher SALT deduction caps, increased standard deductions, no tax on tips or overtime, and a higher Child Tax Credit (CTC). Collectively, these could result in refunds up to $1,000 higher per individual.
Together, these factors could support continued market strength into 2026. But weather, road conditions, and markets can change quickly.
Reasons to Keep Your Foot Near the Brake Pedal
While the road looks smooth, several caution signs deserve attention:
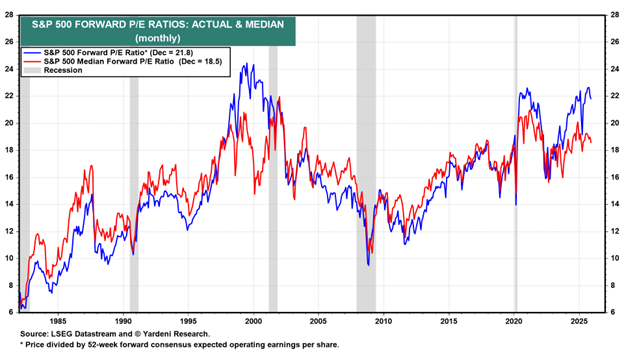
- Elevated Valuations: Forward price-to-earnings ratios (P/E) are at their highest levels since the late 1990s, outside of the brief post-COVID period. (see chart below).
Source: Yardeni Research
- Animal Spirits Are Back: Speculation has expanded well beyond traditional markets. Prediction platforms such as Kalshi, Polymarket, FanDuel, DraftKings, Robinhood, Coinbase, and others now allow bets on everything from political outcomes to economic data—further evidence of speculative behavior.
- Gold and Silver Speculation: Despite a relatively stable U.S. dollar over the past six months, gold rose +64% and silver catapulted +145% in 2025—moves difficult to justify by fundamentals alone (see chart below).

Source: MarketSurge
- Investor Complacency: The Volatility Index (VIX), often called the “fear gauge,” currently hovers near 15, well below its long-term average of 20. Historically, true fear doesn’t surface until readings exceed 25.
- Market Concentration: The “Magnificent 7” stocks represent roughly 1% of the companies in the S&P 500 but account for about 37% of the index’s weighting (see Mag 7 Takes Cash to the Bank)—a concentration reminiscent of the late 1990s. When leadership narrows, downturns can be sharper.
The Sidoxia View
At Sidoxia Capital Management, we have implemented all-weather, time-tested strategies through decades of both bull and bear markets. We believe diversification and disciplined risk management are essential—not fruitless prediction attempts. Rather than attempting to time short-term market moves, we focus on adapting portfolios to changing conditions and navigating inevitable financial potholes.
We don’t always get it right, but over the long run, this approach has allowed us to earn and retain the trust, loyalty, and confidence of our clients.
After three years of strong performance, it’s easy to assume clear roads and blue skies will continue indefinitely. But history teaches us that the most dangerous moments often occur when confidence is highest. This is not a call to abandon the journey—only a reminder to stay alert. When markets accelerate this quickly, discipline, diversification, and risk management matter more than ever.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (Jan. 2, 2026). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in MSFT, GOOGL, AMZN, META, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position in ORCL or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.
As We Give Thanks, AI and Mag 7 Take Cash to the Bank

Market volatility resurfaced last month as speculation intensified over whether an AI bubble may be forming—and potentially bursting. Yet despite the jitters, equity markets remain solidly positive for the year (S&P 500 +16.5%, NASDAQ +21.0%, Dow +12.2%) – see S&P 500 chart below. A significant portion of the gains have been powered in large part by ongoing strength in the Magnificent 7. Standouts such as NVIDIA (+31.8%) and Alphabet (+68.1%) have been instrumental in carrying the broader indices higher.

Even with these sizable year-to-date gains, memories of the 2000 Tech Bubble and 2008 Financial Crisis resurfaced and prompted investors to temporarily tap the brakes. Mid-month, the NASDAQ retreated roughly -9% from its October peak. After a month-end bounce, the S&P 500 finished essentially flat (+0.1%), the NASDAQ slipped -1.5%, and the Dow eked out a +0.3% increase.
OpenAI and the $1.4 Trillion Question
At the center of the AI controversy sits OpenAI, parent of the three-year-old technology toddler, ChatGPT (Generative Pre-trained Transformer), which now boasts more than 800 million global users (see chart below). The company reportedly runs at a $20 billion annual revenue pace, yet faces difficult questions about how it intends to fund its staggering $1.4 trillion AI infrastructure commitments.
Those concerns came to a head when tech investor Brad Gerstner pressed CEO Sam Altman on his podcast last month. Instead of answering how OpenAI plans to underwrite such an enormous buildout, Altman childishly shot back defensively:
“If you want to sell your shares, I’ll find you a buyer.” (See clip here — or full interview here)

Source: Digital Information World
OpenAI is a key player, but just one component in the vast—and rapidly expanding—web of global AI infrastructure. Gartner, a global research and advisory firm, forecasts $2 trillion of AI investment in 2026, while NVIDIA CEO Jensen Huang recently said:
“Over the next five years, we’re going to scale into… effectively a $3 to $4 trillion AI infrastructure opportunity.”
These provocative “Is this a bubble?” questions make for great headlines, but to truly evaluate AI sustainability, it’s wise to follow the classic Watergate guidance from of All the President’s Men character, Deep Throat (FBI Associate Director, Mark Felt), who tells journalist Bob Woodward to “follow the money,” if he wants to get to the bottom of the Watergate scandal.
The same principle applies to investors who follow the money – the picture looks very different from past bubbles.
Forget Pets.com—Today’s AI Buildout Is Being Funded by Cash-Rich Titans
Unlike the flimsy, profitless internet startups of the late 1990s—companies that raised billions based on “eyeballs” and cocktail-napkin business plans—the current AI buildout is being financed largely by profitable cash-generating giants.
Yes, some firms like Oracle (ORCL) are leaning on debt financing for data-center expansion. But the overwhelming majority of AI capex is being funded by customers and by the cash flow of the Magnificent 7, a group with the financial firepower to sustain multi-year spending without relying heavily on capital markets.
This dynamic alone separates today’s environment from classic bubble conditions.
Do the Magnificent 7 Really Deserve a $22 Trillion Valuation?
The Mag 7 represent only 1% of S&P 500 constituents yet account for a massive 35% of the index’s market value. That concentration understandably raises eyebrows, evoking historical parallels to the “Nifty Fifty” of the 1970s or the “Four Horsemen” of the 1990s.
But headline concentration can be misleading—because the fundamentals tell a very different story. Here are some of the major disparities:
1.) Mag 7 Share of Profits Matches Their Share of Market Value: The Mag 7 collectively contribute $22 trillion of the S&P 500’s $58 trillion total value (below). Said differently, the market values and weightings of the Mag 7 equate to about $22 trillion and 37% of the S&P 500, respectively:
· Nvidia Corp: $4.3T & 7.0%
· Apple Inc.: $4.1 T & 6.7%
· Alphabet Inc.: $3.9 T & 6.3%
· Microsoft Corp.: $3.7 T & 5.9%
· Amazon.com Inc.: $2.5 T & 4.0%
· Meta Platforms Inc.: $1.6T & 2.6%
· Tesla Inc.: $1.4T & 2.3%
· TOTAL: $22T / 37%
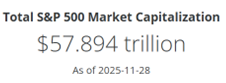
Source: Slickcharts
Conveniently (and importantly), the Mag 7’s roughly $747 billion in annual cash flow (see table below) is a good proxy for their profit contribution to the $2 trillion in S&P profits.
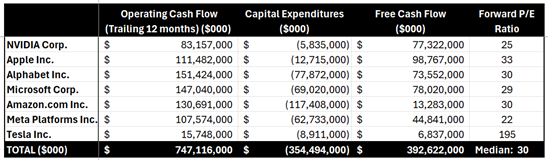
Source: SEC Filings & MarketSurge
The $747 billion in Mag 7 cash flows divided by the $2 trillion in S&P 500 coincidentally also equates to 37% ($747B/$2T).
These calculations of the Mag 7 are not bubble math—these calculation comparisons are rational math. Arguments could be made that Mag 7 market values are actually undervalued (not in bubble territory) and should appreciate to a higher percentage of the S&P 500 weightings because these 7 stocks are growing sales and profits faster than compared to the other “absentee” 493 stocks in the index.
2.) Mag 7 are Swimming in Cash: That $747 billion in annual cash flow is on track to hit a jaw-dropping $1 trillion, giving these firms ample capital to fund AI buildouts without substantially accessing the equity or credit markets. The ability to self-fund a multi-trillion-dollar infrastructure expansion is the opposite of bubble behavior.
3.) Valuations Are Elevated—but Far from Bubble Territory: During the 2000 Tech Bubble, many leading tech names traded at 100x+ earnings (See also: Rational or Irrational Exuberance. Today, the Mag 7 trade at a median forward P/E around 30x. Expensive? Historically, yes, versus long-term averages, but nowhere near historical extremes. Relative to growth, profitability, and cash flow, valuations are far more grounded today than during prior manias.
The bottom line is there is plenty to be thankful for and bubble fears are overstated. Despite pockets of AI froth, the underlying economic engine powering AI adoption is real, profitable, and well-capitalized. When investors follow the money, they discover:
· The Mag 7 generate over one-third of S&P 500 profits
· They generate and hold hundreds of billions in cash
· They largely fund their own AI capital expenditures
· Valuations remain far below bubble-era extremes
Investors have a lot to be thankful for. And while volatility will likely continue, the ingredients for a classic, catastrophic AI bubble are noticeably absent. For disciplined, long-term investing strategies like those employed at Sidoxia Capital Management, this environment still offers abundant opportunity—without the need to fear a pricked AI balloon anytime soon.
Wade W. Slome, CFA, CFP®
Plan. Invest. Prosper.
This article is an excerpt from a previously released Sidoxia Capital Management complimentary newsletter (Dec. 1, 2025). Subscribe Here to view all monthly articles.
DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in NVDA, AAPL, MSFT, GOOGL, AMZN, META, TSLA, and certain exchange traded funds (ETFs), but at the time of publishing had no direct position in ORCL or any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page.